
Copper-Gold Ratio: Industrial Metal Versus Safe Haven, Monthly Since 1992
Copper-Gold Ratio: the price of copper divided by the price of gold, a market-implied growth and risk indicator. An Eco3min monthly composite since 1992, tracking the cyclical-versus-defensive metals balance. CSV download.
The Copper-Gold Ratio is an Eco3min monthly composite that divides the price of copper, an industrial metal driven by manufacturing and construction demand, by the price of gold, a non-yielding safe-haven asset. Calculated as copper (USD per metric ton) divided by gold (USD per troy ounce) and scaled by 1000 for readability, the Copper-Gold Ratio runs monthly from January 1992 to present. Both prices come from the World Bank’s Commodity Price Data (the Pink Sheet). When copper outperforms gold, the market is pricing growth and risk-on flows; when gold outperforms copper, the market is pricing slowdown or systemic fear. The ratio has historically tracked the direction of Treasury yields and PMI readings closely enough to be cited as a cross-asset macro signal in institutional research.
Dataset: Copper-Gold Ratio (1992–2026) · Updated 2026-10-01
Data provided as is, with no warranty of accuracy or timeliness. Check any figure against the primary source cited on this page before using it. Terms: legal notice.
Loading data…
Source: World Bank, Commodity Price Data (The Pink Sheet) · CC BY 4.0 · Ratio: Eco3min calculation
Macro Takeaway
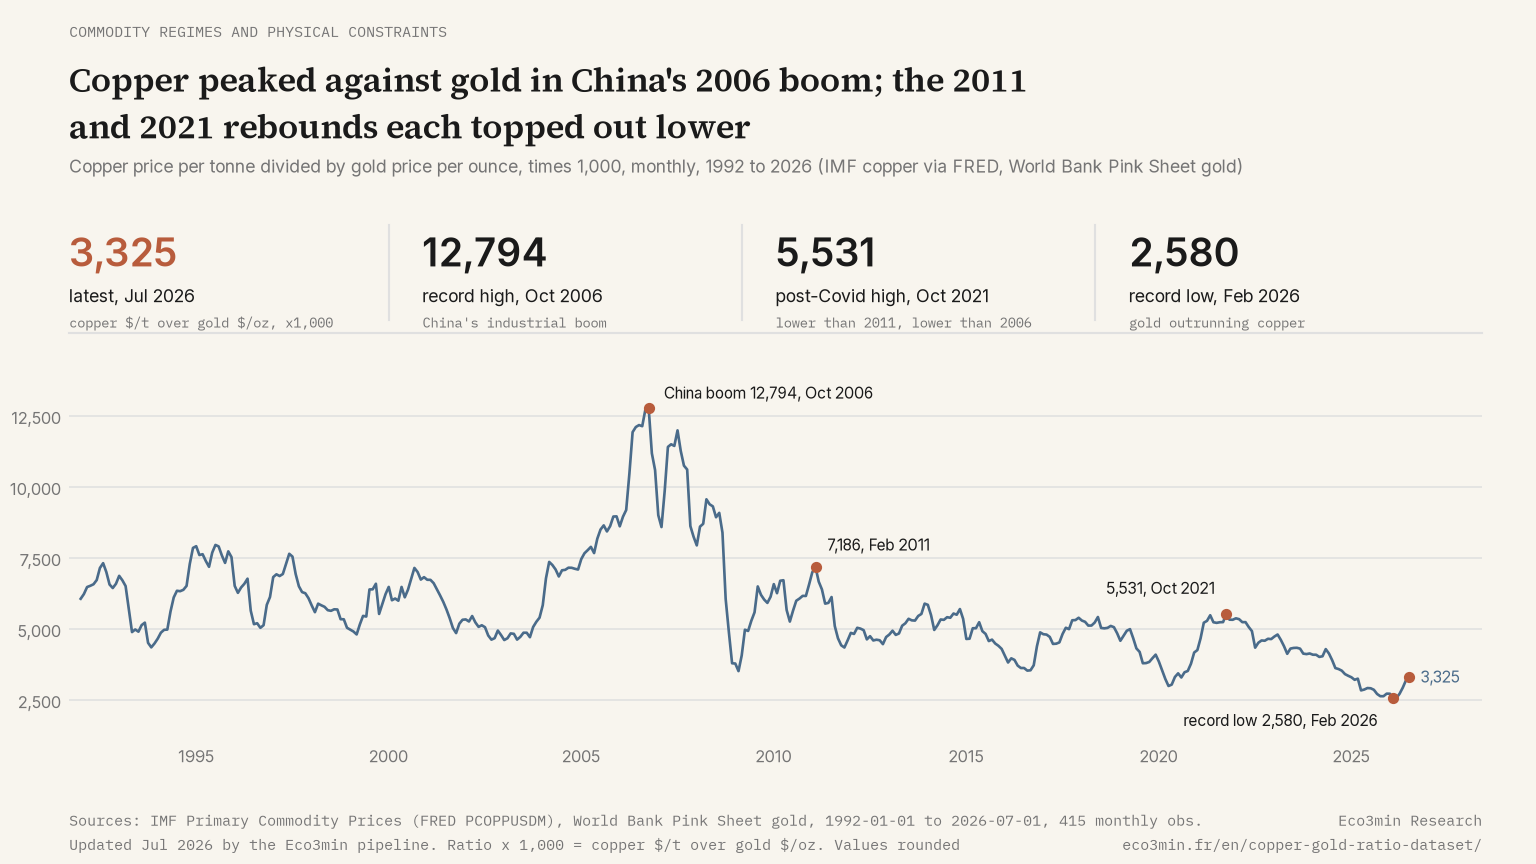
The Copper-Gold Ratio compresses two distinct market signals into a single number: cyclical demand expectations (via copper) and safe-haven demand (via gold). That safe-haven leg of the ratio is the subject of the case for gold as a reserve hedge and de-dollarization gauge. When the ratio rises, it suggests market participants are reallocating from defensive to cyclical commodities; when it falls, the reverse. Over the 1992–2026 sample, the ratio peaked at 12,799 in October 2006, at the height of the China-driven commodity supercycle. It reached its sample low of 2,580 in February 2026, as central-bank gold demand outpaced copper. Intermediate troughs cluster around recessions and financial stress (2001–2002, 2008–2009, 2020).
Cross-referencing the Copper-Gold Ratio with the WTI crude oil price, the US Dollar Index, and the copper price history situates it within the broader commodity-and-growth complex. Correlation with Treasury yields is well-documented in the literature but varies across regimes, particularly when one of the two metals is driven by idiosyncratic factors (Chinese inventory cycles for copper, central-bank reserve diversification for gold).
Construction & Components
The Copper-Gold Ratio is a simple price ratio between two commodities measured in different units, with a scaling factor applied for readability. No deflation or seasonal adjustment is used.
Formula:
Copper-Gold Ratio = (Copper Price [USD/metric ton] / Gold Price [USD/troy ounce]) × 1000
Components:
- Copper price: World Bank Pink Sheet, column “Copper”, which is the London Metal Exchange (LME) settlement price for grade A copper averaged across the month, in USD per metric ton. Used as published, without unit conversion. Source frequency: monthly.
- Gold price: World Bank Pink Sheet, column “Gold”, in USD per troy ounce. Since June 2025 it is the average of daily spot rates, and before that it was the average of the London afternoon fixing (99.5% fine). Source frequency: monthly.
Frequency reconciliation: Both components are natively monthly and come from the same Pink Sheet release, so no interpolation or aggregation step is required. Observations are matched by month (dated the first day of the month in the file) and the ratio is computed directly. The ×1000 scaling turns raw quotients between about 2.6 and 12.8 into readings between about 2,580 and 12,800 over the sample.
Coverage: January 1992 to present, 416 monthly observations to August 2026. The Pink Sheet copper column starts in January 1960; the Eco3min file keeps observations from January 1992 onward, the start used by most Eco3min commodity price files.
Dataset Overview
| Indicator | Copper-Gold Ratio (1992–2026) |
|---|---|
| Geography | Global |
| Frequency | Monthly |
| Period | 1992–2026 |
| Variables | date, copper_price, gold_price, copper_gold_ratio |
| Format | CSV, Excel (XLSX) |
| Sources | World Bank: Commodity Price Data (The Pink Sheet), Monthly Prices, columns “Copper” and “Gold”; ratio computed by Eco3min |
| Licence | World Bank data under CC BY 4.0 (World Bank Terms of Use for Datasets); Eco3min grants no licence of its own |
| Last updated | 2026-10-01 |
Dataset Variables
The CSV and Excel files contain the following columns.
| Column | Type | Description |
|---|---|---|
date | Date (YYYY-MM-DD) | Observation date |
copper_price | Float | Copper price (USD per metric ton) |
gold_price | Float | Gold price (USD/oz) |
copper_gold_ratio | Float | Copper/Gold ratio (×1000) |
Column names match the CSV headers exactly.
Where the Latest Ratio Sits in the Distribution
Because the ratio has trended down since 2006, a reading that looks low against the full record can be ordinary against the last decade. This tool places the latest copper to gold ratio inside the distribution of monthly readings for the window you choose, and reports its percentile rank, the window median and the dated extremes.
The August 2026 ratio of 3,248 sits at the 4th percentile of the 416 months since January 1992, whose median is 5,304, and at the 27th percentile of the last five years, median 4,125. The record high is 12,799 in October 2006, the low 2,580 in February 2026.
Download the Complete Dataset
The full dataset is available in CSV and Excel formats.
Data provided as is, with no warranty of accuracy or timeliness. Check any figure against the primary source cited on this page before using it. Terms: legal notice.
Direct CSV Access: Eco3min Structured Dataset
https://eco3min.fr/dataset/copper-gold-ratio.csv
This URL returns the complete pre-computed ratio in CSV format. It can be used directly in pandas, R, curl, or any data tool. The two components are columns of the World Bank Pink Sheet, published as a monthly Excel workbook on the World Bank’s commodity markets page under CC BY 4.0. The ratio itself is an Eco3min calculation that the World Bank does not publish.
Using the Dataset in Python
import pandas as pd

url = "https://eco3min.fr/dataset/copper-gold-ratio.csv"
df = pd.read_csv(url, parse_dates=["date"])

print(df.head())
print(df["copper_gold_ratio"].describe())
Using the Dataset in R
library(readr)

url <- "https://eco3min.fr/dataset/copper-gold-ratio.csv"
df <- read_csv(url)

head(df)
summary(df$copper_gold_ratio)
Both examples load the dataset directly from the URL, no download or API key required.
Methodology
The Copper-Gold Ratio is recomputed monthly by an Eco3min pipeline on GitHub Actions that reads the copper and gold columns of the World Bank Pink Sheet workbook after each monthly release. Both prices are used as published, copper in USD per metric ton and gold in USD per troy ounce, without unit conversion. The two series are matched by month and divided, with the ×1000 scaling applied. The World Bank updates the Pink Sheet on the second business day of each month.
Both inputs are monthly averages of daily spot prices, which smooths intra-month volatility but means the composite cannot detect short-lived dislocations.
Data Quality & Provider Notes
Since both components come from the same World Bank release, latency for the Copper-Gold Ratio is that of the Pink Sheet, which publishes each month’s averages on the second business day of the following month.
Both components are revised infrequently, but the World Bank can correct recent months or replace a series, and it lists those changes in the notes of the Pink Sheet workbook. The Eco3min pipeline rebuilds the whole file at each release to keep the composite consistent with the latest source data. The gold column changed basis in June 2025. Since then it is the average of daily spot rates, and before that it was the average of the London afternoon fixing.
Source change on 30 September 2026. Until that date the copper column of this file reproduced another publisher’s series; the whole copper history was then rebuilt from the Pink Sheet column, so copper prices and ratios downloaded earlier can differ slightly.
A daily-frequency Copper-Gold Ratio can be constructed from Comex futures or LBMA gold fixings combined with LME copper, but it diverges from the monthly composite during high-volatility weeks. The breakdown is provided in this analysis of silver volatility gold ratio. The monthly version is the standard reference used in published macro research and is more comparable across long-horizon backtests.
What This Index Captures (And What It Doesn’t)
The Copper-Gold Ratio is a parsimonious cross-asset macro signal: a single number that summarizes the relative pricing of two metals with opposite cyclical exposures. Its appeal is its simplicity; its limitations come from the same source.
What it captures:
- The relative pricing of cyclical (copper) versus defensive (gold) commodity demand
- Coincident shifts in global growth expectations as priced by physical-commodity markets
- Long-horizon comparability across commodity supercycles, since both metals span the same historical window
- A simple cross-check on whether Treasury yields, equity-cyclicals, and PMI readings are pointing in consistent directions
What it does NOT capture (common misinterpretations):
- A direct timing signal. Historical correlation with Treasury yields is well-documented but unstable across regimes. Periods of structural divergence (2011–2015, 2020–2022) are not rare and can persist for years.
- Pure growth expectations. Copper prices are influenced by Chinese inventory and stimulus cycles, supply-side shocks (Chilean strikes, Peruvian disruption), and the energy transition demand for electrification. Gold prices reflect real rates, dollar strength, and central-bank reserve flows. The ratio mixes all of these.
- Equity-market direction. The ratio is a commodity-derived signal, not an equity indicator. Mapping it onto sector rotations or risk-on/risk-off equity flows is an inferential step, not a direct read.
- Causal information. The Copper-Gold Ratio is a price ratio, not a forecast. It coincides with growth signals rather than leading them: it tells you what is priced now, not what will happen next.
The Copper-Gold Ratio is best used as one cross-asset confirmation among several in a broader macro-regime framework, not as a standalone allocation signal.
Historical Regimes
The Copper-Gold Ratio spans more than three decades, from January 1992 to today. Regime classification is approximate, since both metals exhibit long cycles with overlapping drivers. The full account is given in copper and oil as macro bellwethers.
- 1992–2002: Disinflation-era range. Annual averages held between roughly 5,000 and 7,600 with no sustained trend, through the US expansion, the Asian crisis and the 2001 recession.
- 2003–2008: China supercycle. Copper appreciated dramatically as Chinese infrastructure investment surged; the ratio reached its sample high of 12,799 in October 2006. Gold also rose, but more slowly. From January 2003 to October 2006, copper gained 355% and gold 64%. More context: Iron ore versus copper as a China signal.
- 2008–2009: GFC collapse. The ratio fell from 9,544 in April 2008 to 3,515 in February 2009 as copper lost 62% and gold held up. Among the cleanest regime transitions in the series.
- 2011–2019: Post-crisis decline, then range. The ratio halved from 7,177 in February 2011 to 3,546 in August 2016, as copper lost 52% while gold ended close to its February 2011 level. It then moved between about 3,600 and 5,400 through 2019. Period of mild divergence with Treasury yields.
- 2020–2022: Reflation-then-fear. Sharp drop in March and April 2020 (low of 3,005 in April 2020), sharp recovery to 5,531 in October 2021 on stimulus and the green-energy demand narrative, then renewed weakness as China stimulus disappointed in 2022 (4,354 in July 2022).
- 2023–2026: Electrification-versus-fear tension. The ratio has reflected two opposing forces: structural copper demand from electrification and EVs versus persistent gold strength tied to central-bank reserve diversification and elevated geopolitical risk. Gold has had the upper hand over this stretch: the ratio set its sample low of 2,580 in February 2026 and averaged 2,921 over the first eight months of that year.
Related Macroeconomic Datasets
The Copper-Gold Ratio sits within a broader commodity-and-growth complex. Cross-checking with individual commodity prices and the dollar-cycle helps isolate which component is driving any given regime shift.
- Copper Price History: the cyclical numerator
- WTI Crude Oil Price: the other major industrial-cyclical commodity
- Brent Crude Oil Price: global oil benchmark
- Real Crude Oil Price: WTI adjusted for CPI inflation
- Natural Gas Price History: energy demand complement
- US Dollar Index (DTWEXBGS): dollar cycle context for commodity pricing
Macroeconomic Dataset Hub
This dataset is part of the Eco3min macro-financial data repository.
Explore the Eco3min Dataset Hub
Sources
- World Bank: Commodity Price Data (The Pink Sheet), Monthly Prices, column “Copper” (CC BY 4.0)
- World Bank: Commodity Price Data (The Pink Sheet), Monthly Prices, column “Gold” (CC BY 4.0)
- London Metal Exchange (LME) settlement price, the market basis of the Pink Sheet copper series
Dataset Reference
Last updated — 6 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Data on this page: the series are collected automatically from the sources cited, then formatted or calculated by Eco3min (units, frequency, derived calculations). They may differ from the official release because of producer revisions, update lags, rounding or processing errors. They are provided as is, with no warranty of accuracy, completeness or timeliness. Before any professional, contractual or regulatory use, and before any financial decision, check the values against the primary source. To the extent permitted by law, the publisher accepts no liability for the consequences of using these data without that check.
Source terms. This dataset is an Eco3min ratio: the World Bank Pink Sheet copper price (USD per metric ton) divided by the Pink Sheet gold price (USD per troy ounce), times 1000, a transformation made by Eco3min. The copper_price and gold_price columns reproduce the Pink Sheet columns unmodified. World Bank data, licensed by the World Bank under Creative Commons Attribution 4.0 (CC BY 4.0) with the additional terms of the World Bank Terms of Use for Datasets; attribution to the World Bank is required. Eco3min grants no licence of its own on these data. Full terms.