
Macroeconomic Datasets & Financial Data Repository
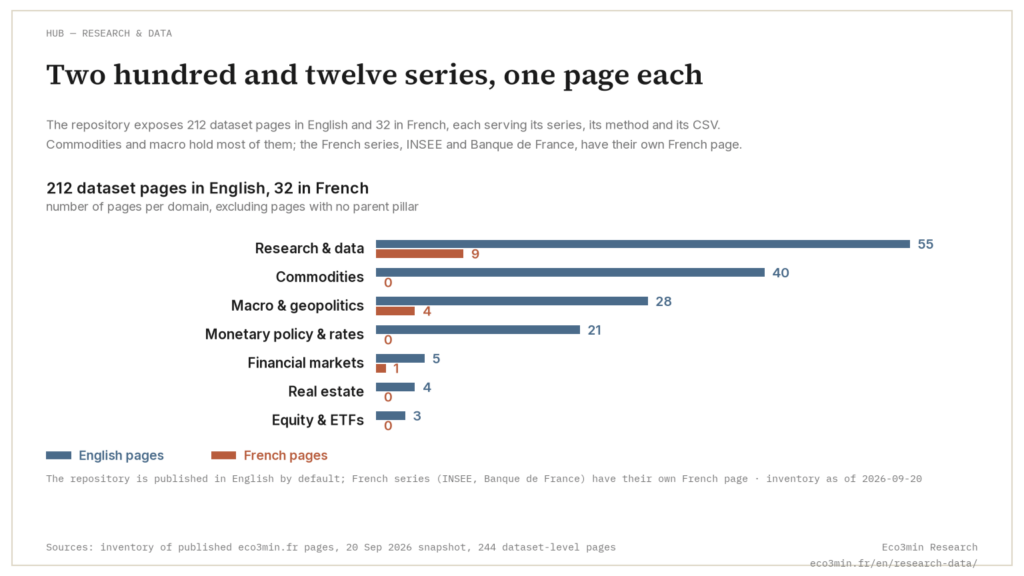
99 macro-financial datasets and 34 research studies, 1871 to 2026, built from FRED, BLS, World Bank and BEA data and from the other producers named on each page. Every dataset includes key statistics, Python/R code snippets, historical regime analysis and, where the licence allows, a file to download (CSV and Excel). Learn how to read macro-financial indicators.
Daily updates (Mon–Sat, 08:00 UTC). Eco3min text and analysis: CC BY 4.0. Data, files and charts remain subject to their producer’s terms, stated on each page; Eco3min grants no licence over third-party data. For topical macro research, see the Macro Watch.
Today’s macro regime Regime dashboard Classification methodology
Featured
- New · Topical research FREco3min Macro Watch
- Research study FRThe US Dollar at the Onset of Global Crises (1973–2023)
- Proprietary indicatorEco3min US Inflation Regime Score2004–2026 · monthly · Eco3min, from St. Louis Fed, BLS
- Pillar guide FRUS Inflation: complete guide
US Equities
US benchmark indices, volatility, long-term valuations, and the non-linear relationship between real rates and equity multiples.
11 datasets · 4 studies
- Study FRUS Real Interest Rates vs CAPE Ratio (1963–present)
- Study FRThe Contrarian's Almanac: Why Buying Fear Has Outperformed Since 1990
- Study FREvery S&P 500 Crash Since 1950
- Study FRDoes Tech Fall Harder in Bear Markets? US Tech vs the Market, 1971–2026
- S&P 500 Historical Returns1928–2025 · annual · Eco3min, from Aswath Damodaran, BLS
- S&P 500: total return index1871–2026 · monthly · Eco3min, from Robert Shiller
- Nasdaq Composite1971–2026 · daily · Nasdaq · page only
- VIX Volatility Index1990–2026 · daily · Cboe · page only
- S&P 500 CAPE Ratio1881–2026 · monthly · Robert Shiller
- Excess CAPE Yield1881–2026 · monthly · Eco3min, from Robert Shiller, Federal Reserve Board
- S&P 500 P/E Ratio1871–2026 · monthly · Eco3min, from Robert Shiller
- S&P 500 Earnings Yield1871–2026 · monthly · Eco3min, from Robert Shiller
- S&P 500 Dividend Yield1871–2026 · monthly · Eco3min, from Robert Shiller
- US Equity Risk Premium1871–2026 · monthly · Eco3min, from Robert Shiller, Federal Reserve Board
- Big Tech CapEx as % of Revenue2015–2026 · quarterly · Eco3min, from SEC EDGAR filings
Interest Rates & Yield Curve
Treasury yields across the curve, Fed funds rate, mortgage rates, spreads and real rates, with recession signals anchored in the term structure.
15 datasets · 8 studies
- Study FREquity Risk Premium: 2-Year vs 10-Year Treasury1976–2026
- Study FRThe Hidden Tax on Safety: How "Risk-Free" Assets Destroyed More Wealth Than Most Crashes
- Study FRYield Curve Inversion History (2s10s Spread)
- Study FRUS Real Interest Rates History (1962–present)
- US 10-Year Treasury Yield (DGS10)1962–2026 · daily · Federal Reserve Board
- US 2-Year Treasury Yield (DGS2)1976–2026 · daily · Federal Reserve Board
- US 3-Month Treasury Bill (DTB3)1954–2026 · daily · Federal Reserve Board
- US 30-Year Treasury Yield (DGS30)1977–2026 · daily · Federal Reserve Board
- Federal Funds Rate1954–2026 · monthly · Federal Reserve Board
- 10Y–2Y Spread (T10Y2Y)1976–2026 · daily · St. Louis Fed
- 10Y–3M Spread (T10Y3M)1982–2026 · daily · St. Louis Fed
- US Term Premium (10-Year Treasury)1962–2026 · monthly · New York Fed
- 30-Year Mortgage Rate1971–2026 · weekly · Freddie Mac · page only
- Real 10-Year Treasury Yield (DGS10 – CPI)1962–2026 · monthly · Eco3min, from Federal Reserve Board, BLS
- Real 2-Year Treasury Yield (DGS2 – CPI)1976–2026 · monthly · Eco3min, from Federal Reserve Board, BLS
- Real Federal Funds Rate1954–2026 · monthly · Eco3min, from Federal Reserve Board, BLS
- Real Corporate Bond Yield: Moody's BAA1953–2026 · monthly · Eco3min, from Moody's, BLS · page only
- Mortgage Spread: 30Y vs 10Y Treasury1971–2026 · weekly · Eco3min, from Freddie Mac, Federal Reserve Board · page only
- Curve Slope: 10Y Treasury vs Fed Funds1962–2026 · monthly · Eco3min, from Federal Reserve Board
- Study The Fed's Track Record: 70 Years of Rate Decisions1954–2026 FR
- Study The Worst Bear Market You've Never Heard Of: How the 30Y Treasury Lost 53% FR
- Study The 2-Year Treasury Leads Fed Pivots (1976–2026) FR
- Study Reverse-Engineering the NY Fed Recession Probability Model FR
Inflation & Prices
Consumer prices, producer prices, the Fed’s preferred measures, real wages, and market-implied inflation expectations. See also the complete US inflation guide and the Eco3min Inflation Regime Score.
12 datasets · 5 studies
- Study FRUS Inflation Is Not Linear: 110 Years of Purchasing Power Destruction
- Study FRUS Inflation Breakeven Term Structure
- Study FRPCE vs CPI Inflation Gap: Why the Fed Prefers PCE (1960–2026)
- Study FRWTI Shocks Amplify Existing Inflation (They Don't Create It)
- US CPI Inflation History (CPIAUCSL)1948–2026 · monthly · BLS
- Core CPI Inflation (ex-food & energy)1958–2026 · monthly · BLS
- PCE Inflation1960–2026 · monthly · BEA
- Core PCE Inflation1960–2026 · monthly · BEA
- Trimmed Mean PCE Inflation: Dallas Fed1978–2026 · monthly · Dallas Fed
- 5-Year Breakeven Inflation (T5YIE)2003–2026 · daily · St. Louis Fed
- 10-Year Breakeven Inflation (T10YIE)2003–2026 · daily · St. Louis Fed
- US Producer Price Index: PPI1914–2026 · monthly · BLS
- US Real Wage Growth2007–2026 · monthly · Eco3min, from BLS
- US Employment Cost Index Growth2002–2026 · quarterly · BLS
- US Unit Labor Costs Growth1948–2026 · quarterly · BLS
- Eco3min US Inflation Regime Score2004–2026 · monthly · Eco3min, from St. Louis Fed, BLS
- Study Core CPI vs Headline CPI: Three Episodes of Sustained Divergence (1957–2026) FR
Labor Market & Employment
The Fed’s dual mandate in data: unemployment, payrolls, and high-frequency leading indicators.
13 datasets · 3 studies
- Study FRThe US Productivity-Pay Gap Under Four Conventions1964–2026
- Study FRThe Most Revised Number in Finance: How NFP Revisions Mislead Markets at Turning Points
- Study FRWeekly Initial Jobless Claims as a Recession Signal
- US Unemployment Rate1948–2026 · monthly · BLS
- Weekly Initial Jobless Claims1967–2026 · weekly · US Department of Labor
- Nonfarm Payrolls: NFP1939–2026 · monthly · BLS
- Sahm Rule Recession Indicator1959–2026 · monthly · Claudia Sahm
- US Job Openings: JOLTS2000–2026 · monthly · BLS
- US Quits Rate: JOLTS2000–2026 · monthly · BLS
- US Hires: JOLTS2000–2026 · monthly · BLS
- US Layoffs & Discharges: JOLTS2000–2026 · monthly · BLS
- Beveridge Curve: Openings per Unemployed2000–2026 · monthly · Eco3min, from BLS
- US Continued Jobless Claims1967–2026 · weekly · US Department of Labor
- US U-6 Unemployment Rate1994–2026 · monthly · BLS
- US Labor Force Participation Rate1948–2026 · monthly · BLS
- US Employment-Population Ratio1948–2026 · monthly · BLS
Real Economy & Activity
GDP, industrial production, manufacturing surveys, and consumer sentiment: the hard and soft data that define the business cycle.
11 datasets · 1 study
- US GDP Growth Rate1947–2026 · quarterly · BEA
- US Real GDP Level1947–2026 · quarterly · BEA
- US Industrial Production Index1919–2026 · monthly · Federal Reserve Board
- Chicago Fed National Activity Index: CFNAI1967–2026 · monthly · Chicago Fed
- Consumer Sentiment: U. of Michigan1952–2026 · monthly · University of Michigan · page only
- US Personal Savings Rate1959–2026 · monthly · BEA
- US Federal Debt to GDP1966–2026 · quarterly · OMB, St. Louis Fed
- US Total Public Debt1966–2026 · quarterly · US Treasury
- US Federal Interest Payments1947–2026 · quarterly · BEA
- US Interest Payments to GDP1947–2026 · quarterly · Eco3min, from BEA
- US Labor Productivity Growth1948–2026 · quarterly · BLS
Liquidity & Monetary Policy
Fed balance sheet, money supply, bank reserves, TGA, reverse repo: the plumbing of the financial system. Includes the net liquidity index and “stealth easing” classification.
9 datasets · 6 studies
- Study FRWhere the M2-to-GDP Ratio Stands: US Percentiles Since 1959
- Study FRThe Liquidity Illusion: Why the Fed Balance Sheet Is Not Market Liquidity2003–2026
- Study FRThe Great Offset: How ON RRP Neutralized the Largest QT in History
- Study FRDebt Ceiling: How TGA Drainage Acts as a Liquidity Injection
- Fed Balance Sheet (WALCL)2002–2026 · weekly · Federal Reserve Board
- M2 Money Supply1959–2026 · monthly · Federal Reserve Board
- M2 Growth Rate: YoY1960–2026 · monthly · Federal Reserve Board
- M2 / GDP Ratio1959–2026 · quarterly · Eco3min, from Federal Reserve Board, BEA
- Fed Balance Sheet / GDP Ratio2002–2026 · quarterly · Eco3min, from Federal Reserve Board, BEA
- Treasury General Account (TGA)2002–2026 · weekly · Federal Reserve Board
- Overnight Reverse Repo (ON RRP)2003–2026 · daily · New York Fed
- US Bank Reserves at the Fed1959–2026 · monthly · Federal Reserve Board
- Net Liquidity Index (WALCL – TGA – RRP)2003–2026 · weekly · Eco3min, from New York Fed, Federal Reserve Board
- Study M2 and US Inflation: Testing the Monetarist Regime (Friedman) FR
- Study Fed Balance Sheet: Detailed Operational History (2002–2026) FR
Credit & Financial Conditions
Corporate bond spreads, lending standards, leverage ratios, recession risk indicators, and the Chicago Fed NFCI composite index.
9 datasets · 3 studies
- Study FRBaa Credit Spread vs Stock Market Peaks (1953–2026)
- Study FRThe 0.5 NFCI Rule: Auditing the Financial Stress Threshold
- Study FRThe BBB-ification of Corporate America (1996–2026)
- US High Yield Credit Spread (BAMLH0A0HYM2)2023–2026 · daily · ICE Data Indices · page only
- Investment Grade BBB Spread (BAMLC0A4CBBB)2023–2026 · daily · ICE Data Indices · page only
- Financial Conditions Index: NFCI1971–2026 · weekly · Chicago Fed
- US Bank Lending Standards: SLOOS1990–2026 · quarterly · Federal Reserve Board
- Credit Spread vs VIX Divergence2023–2026 · daily · ICE Data Indices, Cboe · page only
- US Corporate Debt to GDP1947–2026 · quarterly · Eco3min, from Federal Reserve Board, BEA
- US Household Debt to GDP1947–2026 · quarterly · Eco3min, from Federal Reserve Board, BEA
- US Credit Card Delinquency Rate1991–2026 · quarterly · Federal Reserve Board
- US Consumer Loan Delinquency Rate1987–2026 · quarterly · Federal Reserve Board
Housing & Real Estate
Real housing prices and mortgage rates: the credit cycle as experienced by US households. The ultimate test of the monetary transmission mechanism.
6 datasets · 1 study
- US Real Housing Price Index1975–2026 · quarterly · Eco3min, from FHFA, BLS
- US Real Mortgage Rate1971–2026 · monthly · Eco3min, from Freddie Mac, BLS · page only
- US Mortgage Delinquency Rate1991–2026 · quarterly · Federal Reserve Board
- US Housing Starts1959–2026 · monthly · Census Bureau, HUD
- US Building Permits1960–2026 · monthly · Census Bureau, HUD
- US New Home Sales1963–2026 · monthly · Census Bureau, HUD
Commodities, Metals & Crypto
Energy (nominal and real), industrial and precious metals, weighted dollar index, alternative monetary assets (gold, silver, Bitcoin, Ethereum), and the dollar’s role in global crises.
13 datasets · 3 studies
- Study FRThe US Dollar at the Onset of Global Crises (1973–2023)
- Study FRThe Oil Burden Index: Why 4% of GDP Is the Recession Threshold (1970–2026)
- Study FRThe WTI–Brent Spread (1987–2026): It Was Always Oklahoma, Not the Middle East
- US Dollar Index: DTWEXBGS2006–2026 · daily · Federal Reserve Board
- WTI Crude Oil Price1986–2026 · daily · EIA
- Brent Crude Oil Price1987–2026 · daily · EIA
- Real Oil Price: WTI CPI-Adjusted1986–2026 · monthly · Eco3min, from EIA, BLS
- Natural Gas Price: Henry Hub1997–2026 · daily · EIA
- Copper Price History1992–2026 · monthly · World Bank
- Gold Price History1960–2026 · monthly · World Bank
- Real Gold Price (CPI-Adjusted)1960–2026 · monthly · Eco3min, from World Bank, BLS
- Silver Price History1960–2026 · monthly · World Bank
- Gold/Oil Ratio1986–2026 · monthly · Eco3min, from World Bank, EIA
- Copper/Gold Ratio1992–2026 · monthly · Eco3min, from World Bank
- Bitcoin Price History2014–2026 · daily · Coinbase · not reproduced
- Ethereum Price History2016–2026 · daily · Coinbase · not reproduced
No result. Try another term, or the A–Z index.
Pillar guides: long-form frameworks
The Eco3min site is built around 4 pillar guides articulating the relationships between key concepts. Each pillar guide complements the data and the studies above.
📚 Inflation pillar guide
110 years of US inflation: regimes, transmission mechanisms, measures, and reading grid. Anchored in the Eco3min Inflation Regime Score.
Read the guide📚 Commodities pillar guide
Energy, metals, agricultural commodities, and their transmission channels into macro cycles. The links between commodity prices and recessions.
Read the guide📚 Monetary policy pillar guide
The Fed’s tools, the dual mandate, the QE/QT cycle, the transmission to financial conditions and the real economy. Includes the dollar in the global system.
Read the guide📚 Financial markets pillar guide
Equities, bonds, volatility, credit cycle, and how these markets interact across business cycles. Links to indicators above.
Read the guideCrisis episodes: Our overview of crisis episodes.
🇫🇷 French version available: all Eco3min datasets and studies have a French equivalent. Read this hub in French at /donnees-analyses-macro-financieres/.
Methodology, sources and licence
All datasets and studies on Eco3min follow the same documented and reproducible pipeline. Primary sources cited, transparent code, automatic updates.
Data sources
Public macro series come from the FRED API (St. Louis Fed), the BLS, the World Bank, the BEA, and Yale Department of Economics (Shiller). Corporate data come from the SEC EDGAR XBRL API. No paid sources, no proprietary scraping.
Automatic pipeline
Two Python pipelines (FRED + ECB) run via GitHub Actions every business day at 08:00 and 09:30 UTC. They generate cleaned CSV + XLSX, compute regime statistics, and update the WordPress REST API to refresh the JSON-LD dateModified. Open-source code on GitHub.
Composites & ratios
Composite series (Net Liquidity Index, Eco3min Inflation Regime Score, real Treasury yields, M2/GDP, S&P 500/M2, etc.) are computed by Eco3min from the underlying FRED series. The aggregation formula is documented in the methodology section of each dataset.
License & citation
Eco3min text and analysis: CC BY 4.0, with attribution: “Eco3min Research, [year]” + link to the source page. Data, files and charts remain subject to their producer’s terms, stated on each page; Eco3min grants no licence over third-party data. Citation block at the bottom of this page.
All datasets, A to Z99
- 10-Year Breakeven Inflation (T10YIE)
- 10Y–2Y Spread (T10Y2Y)
- 10Y–3M Spread (T10Y3M)
- 30-Year Mortgage Rate
- 5-Year Breakeven Inflation (T5YIE)
- Beveridge Curve: Openings per Unemployed
- Big Tech CapEx as % of Revenue
- Bitcoin Price History
- Brent Crude Oil Price
- Chicago Fed National Activity Index: CFNAI
- Consumer Sentiment: U. of Michigan
- Copper Price History
- Copper/Gold Ratio
- Core CPI Inflation (ex-food & energy)
- Core PCE Inflation
- Credit Spread vs VIX Divergence
- Curve Slope: 10Y Treasury vs Fed Funds
- Eco3min US Inflation Regime Score
- Ethereum Price History
- Excess CAPE Yield
- Fed Balance Sheet (WALCL)
- Fed Balance Sheet / GDP Ratio
- Federal Funds Rate
- Financial Conditions Index: NFCI
- Gold Price History
- Gold/Oil Ratio
- Investment Grade BBB Spread (BAMLC0A4CBBB)
- M2 / GDP Ratio
- M2 Growth Rate: YoY
- M2 Money Supply
- Mortgage Spread: 30Y vs 10Y Treasury
- Nasdaq Composite
- Natural Gas Price: Henry Hub
- Net Liquidity Index (WALCL – TGA – RRP)
- Nonfarm Payrolls: NFP
- Overnight Reverse Repo (ON RRP)
- PCE Inflation
- Real 10-Year Treasury Yield (DGS10 – CPI)
- Real 2-Year Treasury Yield (DGS2 – CPI)
- Real Corporate Bond Yield: Moody's BAA
- Real Federal Funds Rate
- Real Gold Price (CPI-Adjusted)
- Real Oil Price: WTI CPI-Adjusted
- S&P 500 CAPE Ratio
- S&P 500 Dividend Yield
- S&P 500 Earnings Yield
- S&P 500 Historical Returns
- S&P 500 P/E Ratio
- S&P 500: total return index
- Sahm Rule Recession Indicator
- Silver Price History
- Treasury General Account (TGA)
- Trimmed Mean PCE Inflation: Dallas Fed
- US 10-Year Treasury Yield (DGS10)
- US 2-Year Treasury Yield (DGS2)
- US 3-Month Treasury Bill (DTB3)
- US 30-Year Treasury Yield (DGS30)
- US Bank Lending Standards: SLOOS
- US Bank Reserves at the Fed
- US Building Permits
- US Consumer Loan Delinquency Rate
- US Continued Jobless Claims
- US Corporate Debt to GDP
- US CPI Inflation History (CPIAUCSL)
- US Credit Card Delinquency Rate
- US Dollar Index: DTWEXBGS
- US Employment Cost Index Growth
- US Employment-Population Ratio
- US Equity Risk Premium
- US Federal Debt to GDP
- US Federal Interest Payments
- US GDP Growth Rate
- US High Yield Credit Spread (BAMLH0A0HYM2)
- US Hires: JOLTS
- US Household Debt to GDP
- US Housing Starts
- US Industrial Production Index
- US Interest Payments to GDP
- US Job Openings: JOLTS
- US Labor Force Participation Rate
- US Labor Productivity Growth
- US Layoffs & Discharges: JOLTS
- US Mortgage Delinquency Rate
- US New Home Sales
- US Personal Savings Rate
- US Producer Price Index: PPI
- US Quits Rate: JOLTS
- US Real GDP Level
- US Real Housing Price Index
- US Real Mortgage Rate
- US Real Wage Growth
- US Term Premium (10-Year Treasury)
- US Total Public Debt
- US U-6 Unemployment Rate
- US Unemployment Rate
- US Unit Labor Costs Growth
- VIX Volatility Index
- Weekly Initial Jobless Claims
- WTI Crude Oil Price
Frequently asked questions
What’s the difference between this hub and the Macro Watch?
This hub aggregates the evergreen resources: 99 macro-financial datasets (updated daily via FRED) and 34 research studies developing reference analytical frameworks (yield curve, real rates, liquidity illusion, oil burden, NY Fed probit recession model, BBB-ification, etc.). The Macro Watch publishes topical studies every Tuesday, anchored on a recent market or policy event and placed in their long historical context. The two layers are complementary.
What is the Eco3min US Inflation Regime Score?
The Eco3min Score is a monthly proprietary composite indicator classifying the US inflation regime across five dimensions: CPI trend, core dynamic, market expectations, wage pressure, and monetary signal. Its methodology is open and reproducible. It sits within the analytical framework developed in the complete US inflation guide.
What’s the best leading indicator of a US recession?
The yield curve (10Y–2Y spread) has preceded every US recession since 1976 with a 6 to 24 month lead. High Yield credit spreads have also widened before every major equity drawdown since 1997, with a median lead of 7 months. The study Five Recession Rules Tested empirically compares accuracy, lag and false positives across five distinct rules, and the NY Fed probit model reconstructs the official probability over 35 years of daily Treasury data.
Where can I download macroeconomic datasets in CSV?
This hub indexes 99 macroeconomic dataset pages, most of which offer a CSV download, almost always with an Excel version. They cover inflation, interest rates, equity markets, liquidity, credit conditions, housing, commodities, and employment. Series under restrictive licences (Cboe, the University of Michigan, Freddie Mac, ICE BofA, Moody’s, Nasdaq, Coinbase) link to the primary source. Data come mainly from FRED, BLS, the World Bank and BEA (other producers are named on each dataset page), are automatically updated, and remain subject to their producer’s terms, stated on each dataset page; Eco3min text and analysis: CC BY 4.0.
What is the Net Liquidity Index and how is it computed?
The Net Liquidity Index equals total Fed assets (WALCL) minus the Treasury General Account (TGA) minus the reverse repo facility (ON RRP). It measures the effective liquidity of the financial system and is tracked by macro analysts such as Darius Dale and Raoul Pal. The full weekly dataset since 2003 is available, computed by Eco3min from three distinct FRED series.
How does M2 money supply growth predict inflation?
The M2 growth rate has historically led CPI inflation by 12 to 18 months. The unprecedented +27% YoY growth in February 2021 preceded 9.1% CPI inflation in June 2022. The subsequent contraction to −4.7%, the first sustained M2 drop since the 1930s, foreshadowed the disinflation that followed. The study M2 and US Inflation: Testing the Monetarist Regime documents the breakdown of this relationship after ~1990 and its post-2020 resurgence.
What’s the difference between CPI and PCE inflation?
CPI uses fixed consumption baskets while PCE uses dynamically updated weights that account for consumption substitution. Core PCE, the Fed’s official 2% target measure, typically sits 30 to 50 basis points below core CPI. The study PCE vs CPI Inflation Gap decomposes the sources of this divergence (weights, formula, scope). To go further: complete US inflation guide.
What is the real interest rate and why does it matter?
The real interest rate is the nominal yield minus inflation. When negative, lenders effectively pay borrowers, encouraging leverage and risk-taking. The real 10-year Treasury yield has ranged from +9.4% (Volcker era, 1982) to −6.4% (2022 inflation shock).
Cite this data
If you use Eco3min datasets in your research, articles or analyses, please cite them as follows:
https://eco3min.fr/en/research-data/
Eco3min text and analysis: CC BY 4.0, with attribution. Data remain subject to their producer’s terms, stated on each page. Individual citations available on each data page.
Last updated — 13 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.