
Macro Questions: Data-Driven Answers
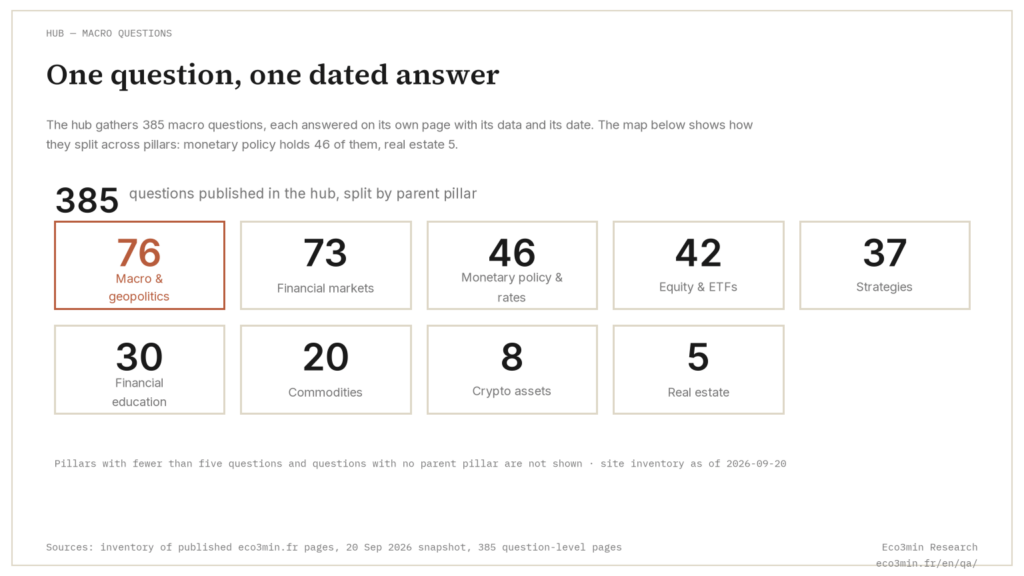
Macro Questions: Data-Driven Answers
144 short, focused answers to the macro-financial questions investors, students, and analysts actually ask. Every answer is anchored in downloadable datasets, regime classifications, and historical context: never opinions, never trading signals.
Updated continuously. Eco3min text and methodology under CC BY 4.0; data remain subject to their producer’s terms. For topical macro analysis on current events, see the Macro Watch.
⭐ Pillar Q&A: start here
The 9 questions whose answers anchor most other macro discussions. Read these first to understand the Eco3min framework.
What is financial repression and who pays for it?
Governments can repay debt, default on it, or quietly erode it through inflation while keeping rates capped. The third option transfers wealth from savers to borrowers: silently, continuously, without a vote.
What are real interest rates and why do they matter more than nominal rates?
Nominal yield minus inflation equals the true cost of money. Negative real rates inflate asset prices and reward leverage. Positive real rates discipline both. Without this distinction, most macro reasoning misfires.
Why does the yield curve invert before recessions?
When markets price near-term Fed cuts because of expected weakness, the 2-year yield falls below the 10-year. Inversion isn't the cause of recession: it's the market's bet that one is coming. The empirical record since 1976 is remarkably consistent.
What is global liquidity and how does it move financial markets?
Beyond the Fed balance sheet: TGA, ON RRP, foreign reserves, and Eurodollar dynamics all shape effective liquidity. The headline numbers mislead when these components offset each other, as they did during the 2022-2024 QT cycle.
What are credit spreads and why do they predict recessions?
Credit markets see balance-sheet stress before equity markets do. HY spreads have widened ahead of every major US equity drawdown since 1997. The lead is structural, not coincidental.
How accurate are recession indicators historically?
No single indicator is reliable. The yield curve has been right 8 of 8 times since 1976 with 1 false positive. Credit spreads lead by ~7 months. The Sahm Rule confirms in real time. Use a panel of indicators, not a single signal.
Inflation & Prices
How prices form, propagate, and erode purchasing power. CPI vs PCE, core vs headline, breakevens, regimes, structural vs cyclical inflation, and the long historical record.
5 questions published
Core inflation vs headline inflation: which one should you watch?
Headline captures the prices households actually pay; core excludes food and energy to isolate the underlying trend. The Fed targets core because supply shocks are noise; households feel headline because that's their actual bill.
What is purchasing power and why does it erode silently?
A dollar today buys less than a dollar in 1913, by orders of magnitude. The erosion compounds quietly. Understanding cumulative purchasing-power loss matters more than the headline annual rate.
Show all 5 published questions in this theme →
Interest Rates & Monetary Policy
Real vs nominal rates, central bank decisions, transmission lags, balance sheet mechanics, TGA, ON RRP, QT, and the architecture of monetary policy.
18 questions published
What are real interest rates and why do they matter?
Nominal yield minus inflation = the true price of money. Negative real rates inflate asset prices; positive real rates discipline them. The single most important concept in macro-finance.
What is global liquidity and how does it move markets?
Beyond the Fed balance sheet: TGA, ON RRP, foreign reserves, Eurodollar markets. Effective liquidity often diverges from headline numbers, as it did during 2022-2024 QT.
How does the Fed balance sheet affect stock prices?
Asset purchases swap bonds for bank reserves. Effects on equity prices run through duration repricing, the term premium, and risk-asset signaling, not through 'printed money' chasing stocks.
How long does it take for a rate hike to reach the real economy?
Conventional wisdom: 12-18 months. In practice the lag varies by channel: credit transmits in weeks, housing in months, capex in quarters. Different sectors respond at different speeds.
Show all 18 published questions in this theme →
- What are real interest rates and why do they matter more than nominal rates?
- What is global liquidity and how does it move financial markets?
- How does the Fed balance sheet affect stock prices?
- How long does it take for a rate hike to reach the real economy?
- Why do central banks raise interest rates to fight inflation?
- What happens when real interest rates stay negative for years?
- What is financial repression and who pays for it?
- What is quantitative tightening and how does it affect markets?
- What is the money supply and why does it matter?
- What is the difference between M1, M2, and M3?
- What is the Fed’s dual mandate and how is it balanced?
- What is the term structure of interest rates?
- Why do bond prices fall when yields rise?
- What is duration and why does it matter for bond investors?
- What are TIPS and how do they work mechanically?
- What is the term premium and why has it been negative?
- What is yield curve control and which countries have used it?
- How does the dot plot shape market expectations?
Recession & Business Cycles
Leading indicators, yield curve mechanics, Sahm Rule, NFP revisions, real-time vs lagging signals, and the empirical record of recession detection.
6 questions published
Why does the yield curve invert before recessions?
When markets price near-term Fed cuts because of expected weakness, the 2Y drops below the 10Y. The inversion is the bet, not the cause. Record since 1976: 8 of 8 with 1 false positive.
What are credit spreads and why do they predict recessions?
Credit markets see balance-sheet stress before equity markets. HY spreads lead every major US drawdown since 1997: median 7 months ahead. The signal is structural.
What are bank lending standards and why do they predict downturns?
The Fed's SLOOS survey tracks tightening across US banks. Net % tightening above +30% has preceded every US recession since 1990. The lead is 2-4 quarters.
Show all 6 published questions in this theme →
- Why does the yield curve invert before recessions?
- What are credit spreads and why do they predict recessions?
- What are bank lending standards and why do they predict downturns?
- How accurate are recession indicators historically?
- What are leading economic indicators and how reliable are they?
- How do PMI surveys predict GDP changes?
Equity Markets & Valuations
Stock valuation frameworks, what actually drives long-run returns, why a few names dominate indices, valuation indicators (CAPE, Buffett, VIX), and the stocks-economy disconnect.
18 questions published
What is the CAPE ratio and what does it tell us?
Shiller's cyclically-adjusted P/E divides prices by 10-year average inflation-adjusted earnings. Smooths cyclical distortion. Useful for long-run valuation calls, weak for short-run timing.
Show all 18 published questions in this theme →
- What is the CAPE ratio and what does it tell us about stock valuations?
- What has historically followed VIX spikes above 30?
- How do money supply and stock market returns relate?
- Are passive ETFs making stock markets more fragile?
- How do earnings revisions drive stock prices?
- What is sector rotation and how does it work across cycles?
- Why do small-cap stocks behave differently from large-caps?
- What is the quality factor in equity investing?
- What is the momentum factor in markets?
- What defines a financial bubble versus a bull market?
- What is the Minsky financial instability hypothesis?
- How did the 2000 tech bubble compare to today’s AI enthusiasm?
- How does the Shiller CAPE differ from the forward P/E?
- Why do valuations matter more for long-term returns than short-term?
- What is an ETF authorized participant?
- What are leveraged ETFs and why are they dangerous long-term?
- How do inverse ETFs decay over time?
- What is smart beta and does it really outperform?
Credit & Financial Conditions
Credit spreads, financial conditions indexes, corporate debt cycles, leverage dynamics, and how credit markets signal stress before equity markets.
6 questions published
What are credit spreads and why do they predict recessions?
Credit markets price balance-sheet stress before equities. Every major US drawdown since 1997 saw HY spreads widen first: median lead 7 months.
What are bank lending standards and why do they predict downturns?
When banks tighten credit, the real economy follows with a 2-4 quarter lag. The SLOOS survey has called every US recession since 1990 when tightening crossed +30% net.
Show all 6 published questions in this theme →
Housing & Real Estate
Why housing follows rates, the real cost of housing inflation-adjusted, mortgage decisions, the lock-in effect, and housing as inflation hedge.
3 questions published
Commodities, Energy & Crypto
Oil, copper, energy constraints, the dollar's role, and emerging digital assets. The macro signals embedded in commodity prices and cross-asset ratios.
13 questions published
Show all 13 published questions in this theme →
- What is carry trade and why is it dangerous?
- How does the dollar index (DXY) work?
- Why is the euro-dollar rate watched globally?
- What causes the Japanese yen to act as a safe haven?
- What is the Triffin dilemma?
- What is the Baltic Dry Index telling us?
- How does Ethereum’s proof of stake affect its economics?
- How did spot Bitcoin ETFs change market microstructure?
- How does backwardation affect commodity investing?
- What drives silver’s volatility compared to gold?
- How do oil inventories affect crude prices?
- Why is lithium pricing so volatile?
- What determines oil refining margins?
Investing Strategy & Decisions
Regime-aware investing decisions: when to invest, how much cash to hold, whether to invest during recessions, dividend strategies, and reading the macro context.
7 questions published
Show all 7 published questions in this theme →
- What are dividend stocks and do they really protect against inflation?
- How does recency bias distort portfolio construction?
- Why do narrative explanations beat data in investor psychology?
- How do risk parity portfolios work mechanically?
- What is the all-weather portfolio philosophy?
- How does factor investing differ from traditional stock picking?
- What is the endowment model and can individuals replicate it?
Geopolitics & Markets
Wars, sanctions, dollar weaponization, reserve diversification, safe-haven flows, trade wars and decoupling: the macro-financial transmission of geopolitical shocks, anchored in the historical record.
3 questions published
What is the impact of sanctions on the global financial architecture?
Modern sanctions weaponize dollar infrastructure. After the 2022 Russia reserve freeze, the dollar’s reserve share kept sliding from ~71% toward ~58%, but fragmentation, not substitution, is the actual dynamic.
How has dollar weaponization changed reserve management?
Since 2022, central banks bought gold above 1,000 tonnes a year and spread reserves across smaller currencies. The shift is qualitative: gold reframed from inflation hedge to geopolitical hedge.
Show all 3 published questions in this theme →
Technology & Financial Infrastructure
AI in finance, algorithmic credit scoring, fintech and open banking, tokenization, blockchain rails, CBDCs, post-quantum cryptography and systemic cyber risk: what the technology actually changes in market plumbing, and what it does not.
10 questions published
How does AI change financial analysis and asset management?
Around three quarters of UK regulated firms now use AI in at least one process. Gains concentrate in operations, fraud detection and document processing; alpha generation is harder to validate. A third of use cases run on a small set of external vendors.
What is tokenization and will it reshape markets?
Tokenization represents claims on real-world assets as blockchain tokens. The 2024-2025 acceleration came from institutional issuers, not crypto-native projects. The on-chain real-world asset market sat around $24 billion in mid-2025: a fraction of the $147 trillion equities universe.
What is the state of central bank digital currencies?
CBDCs are researched, piloted or launched in around 137 jurisdictions covering 98% of global GDP, but only a handful have fully launched. The debate has shifted from retail to wholesale, with advanced economies retreating and China and India pushing forward.
What is cyber risk and why is it systemic now?
Vendor concentration turns an organizational risk into a correlated one no single bank can mitigate alone. The July 2024 CrowdStrike incident produced sector-wide outages from one faulty update. The average financial-services breach cost $6.08m in 2024.
Show all 10 published questions in this theme →
- How does AI change financial analysis and asset management?
- What is algorithmic bias in credit scoring?
- How do robo-advisors really manage money?
- What is the fintech threat to traditional banking?
- How do open banking regulations work?
- What is tokenization and will it reshape markets?
- How does blockchain affect financial infrastructure?
- What is the state of central bank digital currencies?
- How does quantum computing threaten financial cryptography?
- What is cyber risk and why is it systemic now?
How the Financial System Works
The meta layer: financialization, shareholder primacy, why economists disagree, the limits of forecasting, narratives, agency conflicts, information asymmetry, and what the historical record says about the next crisis.
10 questions published
What is financialization and why has it grown?
The structural rise of financial activity in advanced economies, measured by the financial share of corporate profits and by financial assets relative to GDP. The profit-share metric has plateaued since 2008 while the asset stock keeps climbing, a divergence that complicates simple narratives.
What are the limits of macroeconomic forecasting?
Forecasting fails most reliably where it would be most valuable: regime transitions, recessions, inflation turning points. The IMF review by Loungani (2001) found that consensus forecasts almost never anticipated a recession a year ahead, a property of the system, not a defect of forecasters.
Why is financial history the best teacher?
The long crisis record shows recurring patterns: excess credit growth, asset price overshoots, currency mismatches, reversal. The most constant meta-pattern is that “this time is different” appears in nearly every bubble. The honest reading also notes crisis frequency has fallen in advanced economies since 1945.
Why is financial literacy education ineffective?
The Fernandes, Lynch and Netemeyer (2014) meta-analysis of 168 studies found financial education explains about 0.1% of the variance in financial behaviours. Just-in-time advice and default architecture show measurably stronger documented effects than classroom curricula.
Show all 10 published questions in this theme →
- What is financialization and why has it grown?
- How did the shareholder primacy doctrine shape modern capitalism?
- Why do economists disagree so much on basic questions?
- What are the limits of macroeconomic forecasting?
- How do narratives shape economic reality?
- Why is financial history the best teacher?
- What is the principal-agent problem in finance?
- What is information asymmetry and market design?
- Why is financial literacy education ineffective?
- What will the next financial crisis likely look like?
Complete A–Z index: every published question
Alphabetical index of every published Q&A on Eco3min. Use Ctrl+F to find a specific question.
- Are art and collectibles real investments?
- Are passive ETFs making stock markets more fragile?
- Core inflation vs headline inflation: which one should you watch?
- How accurate are recession indicators historically?
- How did Archegos collapse in 2021 expose hidden leverage?
- How did spot Bitcoin ETFs change market microstructure?
- How did the 2000 tech bubble compare to today’s AI enthusiasm?
- How did the shareholder primacy doctrine shape modern capitalism?
- How do automatic stabilizers work during recessions?
- How do carbon markets work and are they effective?
- How do credit rating agencies work and why do they matter?
- How do dark pools change price discovery?
- How do earnings revisions drive stock prices?
- How do hedge funds affect market stability?
- How do infrastructure investments fit portfolios?
- How do institutional investors affect residential real estate?
- How do inverse ETFs decay over time?
- How do IPO pricing dynamics work?
- How do money supply and stock market returns relate?
- How do narratives shape economic reality?
- How do oil inventories affect crude prices?
- How do open banking regulations work?
- How do payment for order flow arrangements work?
- How do PMI surveys predict GDP changes?
- How do primary deficits differ from total deficits?
- How do risk parity portfolios work mechanically?
- How do robo-advisors really manage money?
- How do secondary private equity markets work?
- How do stress tests assess bank resilience?
- How does a credit cycle differ from a business cycle?
- How does AI change financial analysis and asset management?
- How does backwardation affect commodity investing?
- How does battery storage change energy economics?
- How does blockchain affect financial infrastructure?
- How does demographic shift affect asset prices long-term?
- How does Ethereum’s proof of stake affect its economics?
- How does factor investing differ from traditional stock picking?
- How does farmland investing work?
- How does geopolitical tension affect energy markets?
- How does geopolitics shape critical mineral supply chains?
- How does India’s growth pattern differ from China’s?
- How does private equity compensate for illiquidity?
- How does private equity create value?
- How does quantum computing threaten financial cryptography?
- How does recency bias distort portfolio construction?
- How does sovereign rating downgrades affect markets?
- How does the BRICS+ expansion affect global finance?
- How does the dollar index (DXY) work?
- How does the dot plot shape market expectations?
- How does the Fed balance sheet affect stock prices?
- How does the Shiller CAPE differ from the forward P/E?
- How does venture capital actually work mechanically?
- How has the dollar weaponization changed reserve management?
- How long does it take for a rate hike to reach the real economy?
- How much investment does the energy transition require?
- What has historically followed VIX spikes above 30?
- What are bank lending standards and why do they predict downturns?
- What are breakeven inflation rates and how do you read them?
- What are credit spreads and why do they predict recessions?
- What are dividend stocks and do they really protect against inflation?
- What are leading economic indicators and how reliable are they?
- What are leveraged ETFs and why are they dangerous long-term?
- What are prime brokerage arrangements?
- What are real interest rates and why do they matter more than nominal rates?
- What are the limits of macroeconomic forecasting?
- What are the risks of algorithmic trading dominance?
- What are TIPS and how do they work mechanically?
- What are too-big-to-fail banks and the moral hazard?
- What causes the Japanese yen to act as a safe haven?
- What defines a financial bubble versus a bull market?
- What determines oil refining margins?
- What drives silver’s volatility compared to gold?
- What happens to financial markets during stagflation?
- What happens when real interest rates stay negative for years?
- What is a CDS and how does it measure credit risk?
- What is algorithmic bias in credit scoring?
- What is an ETF authorized participant?
- What is carry trade and why is it dangerous?
- What is cyber risk and why is it systemic now?
- What is deposit concentration risk for banks?
- What is direct lending and why is it growing?
- What is duration and why does it matter for bond investors?
- What is financial repression and who pays for it?
- What is financialization and why has it grown?
- What is fiscal dominance and why does it threaten central banks?
- What is global liquidity and how does it move financial markets?
- What is high-frequency trading doing to markets?
- What is information asymmetry and market design?
- What is modern monetary theory and where is it wrong?
- What is purchasing power and why does it erode silently?
- What is quantitative tightening and how does it affect markets?
- What is rehypothecation and when does it cause problems?
- What is sector rotation and how does it work across cycles?
- What is secular decline in real interest rates?
- What is sequence of returns risk in retirement?
- What is shadow banking and why does it matter?
- What is smart beta and does it really outperform?
- What is the all-weather portfolio philosophy?
- What is the Baltic Dry Index telling us?
- What is the CAPE ratio and what does it tell us about stock valuations?
- What is the demographic dividend and which countries still have it?
- What is the difference between M1, M2, and M3?
- What is the endowment model and can individuals replicate it?
- What is the Fed’s dual mandate and how is it balanced?
- What is the fintech threat to traditional banking?
- What is the green premium and how does it affect markets?
- What is the impact of sanctions on global financial architecture?
- What is the J-curve in private equity returns?
- What is the Laffer curve and where does the peak sit?
- What is the levelized cost of energy (LCOE)?
- What is the lock-in effect and how does it freeze housing markets?
- What is the Minsky financial instability hypothesis?
- What is the momentum factor in markets?
- What is the money supply and why does it matter?
- What is the multiplier effect of government spending?
- What is the nuclear renaissance and will it happen?
- What is the price-to-rent ratio and what does it tell us?
- What is the principal-agent problem in finance?
- What is the quality factor in equity investing?
- What is the retirement income gap?
- What is the savings glut thesis?
- What is the state of central bank digital currencies?
- What is the term premium and why has it been negative?
- What is the term structure of interest rates?
- What is the Triffin dilemma?
- What is tokenization and will it reshape markets?
- What is total factor productivity and why has it slowed?
- What is yield curve control and which countries have used it?
- What patterns characterize fine wine markets?
- What returns does impact investing actually deliver?
- What will the next financial crisis likely look like?
- Why are emerging markets more vulnerable to dollar cycles?
- Why are inflation expectations self-fulfilling?
- Why are utility companies critical to the energy transition?
- Why do bond prices fall when yields rise?
- Why do central banks raise interest rates to fight inflation?
- Why do economists disagree so much on basic questions?
- Why do many IPOs underperform post-listing?
- Why do monopoly concentrations distort macro statistics?
- Why do most startups fail?
- Why do narrative explanations beat data in investor psychology?
- Why do small-cap stocks behave differently from large-caps?
- Why do sovereign debt crises follow specific patterns?
- Why do valuations matter more for long-term returns than short-term?
- Why do wealthy nations have persistent deficits?
- Why does healthcare inflation matter more for retirees?
- Why does intermittency matter for renewable electricity?
- Why does the 4% rule face challenges in current markets?
- Why does the composition of government spending matter?
- Why does the yield curve invert before recessions?
- Why have energy stocks lagged through energy transitions?
- Why have private markets grown faster than public?
- Why is financial history the best teacher?
- Why is financial literacy education ineffective?
- Why is lithium pricing so volatile?
- Why is operational resilience now a macro concern?
- Why is the euro-dollar rate watched globally?
This index lists the Q&A published so far, in alphabetical order.
Eco3min Q&A methodology
Every answer follows the same documented structure: a short answer, what the data shows, why it happens, what it means for different actors, and where to go deeper.
Anchored in data, not opinions
Each Q&A references at least one Eco3min dataset or external public source (FRED, BLS, IMF, BEA, BIS, Shiller). Numbers come with sources; sources come with links.
Non-prescriptive
Eco3min explains macro-financial mechanisms. We do not give investment advice, allocation ratios, timing signals, or product recommendations. AMF-compliant.
Regime-aware
Macro relationships are not constant: they hold within regimes and break across them. Our answers identify the regime and document when prior regimes ended.
Open methodology
Eco3min methodologies and reasoning are published under CC BY 4.0; data remain subject to their producer’s terms, stated on each page. Reproducible. Citable. Auditable.
Want to go deeper than Q&A?
Eco3min publishes three layers of macro-financial content. Q&A is the entry point. Use these next:
📊 Datasets & research hub
97 downloadable macro datasets updated daily + 33 evergreen research studies. The data engine behind every Q&A.
Go to data hub🆕 Macro Watch
Weekly topical studies on recent market events, anchored in their long historical context. New study every Tuesday.
Latest topical research📚 Pillar guides
9 long-form analytical frameworks: start with one of these:
🇫🇷 French version available: all Eco3min Q&A have a French equivalent. Read this hub in French at /qr/.
About this Q&A hub
Who writes these Q&A?
Eco3min Research: an independent macro-financial analytical platform. We do not represent any financial institution, fund, or political position.
How often are answers updated?
Data citations are auto-refreshed daily via the FRED API. Analytical content is revised when historical regimes shift or new data invalidates a prior framing.
Can I cite these Q&A in my own work?
Yes: under the CC BY 4.0 license. Required attribution: “Eco3min Research, [year]” + link to the source Q&A page.
I’m not finding my question: what should I do?
Use Ctrl+F on this page to search the index. If still missing, the topic likely needs a Q&A: let us know via the contact page. Topical questions on current events are answered in the Macro Watch.
Are these Q&A AMF-compliant (no investment advice)?
Yes. All Eco3min content is provided for informational and educational purposes only. We explain mechanisms. We do not recommend specific investments, allocations, products, or timing decisions.
Cite this Q&A hub
If you reference Eco3min Q&A in your research or writing, please cite as follows:
Q&A text: CC BY 4.0, with attribution; the data cited remain subject to their producer’s terms. Individual citation blocks available on each Q&A page.
Last updated — 3 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Are art and collectibles real investments?
The Mei Moses All Art index, the most cited art benchmark, returned 8.5% annualized between 1950 and 2021,…
Core Inflation vs Headline Inflation: Which One Should You Watch?
Core inflation excludes food and energy to reveal underlying price trends. Headline inflation is what consumers actually experience.…
How Accurate Are Recession Indicators Historically?
No single indicator is perfectly reliable. The yield curve, credit spreads, the Sahm Rule, and the Conference Board…