
Crypto-Assets: Liquidity Cycles, Real Rates and Financial Integration
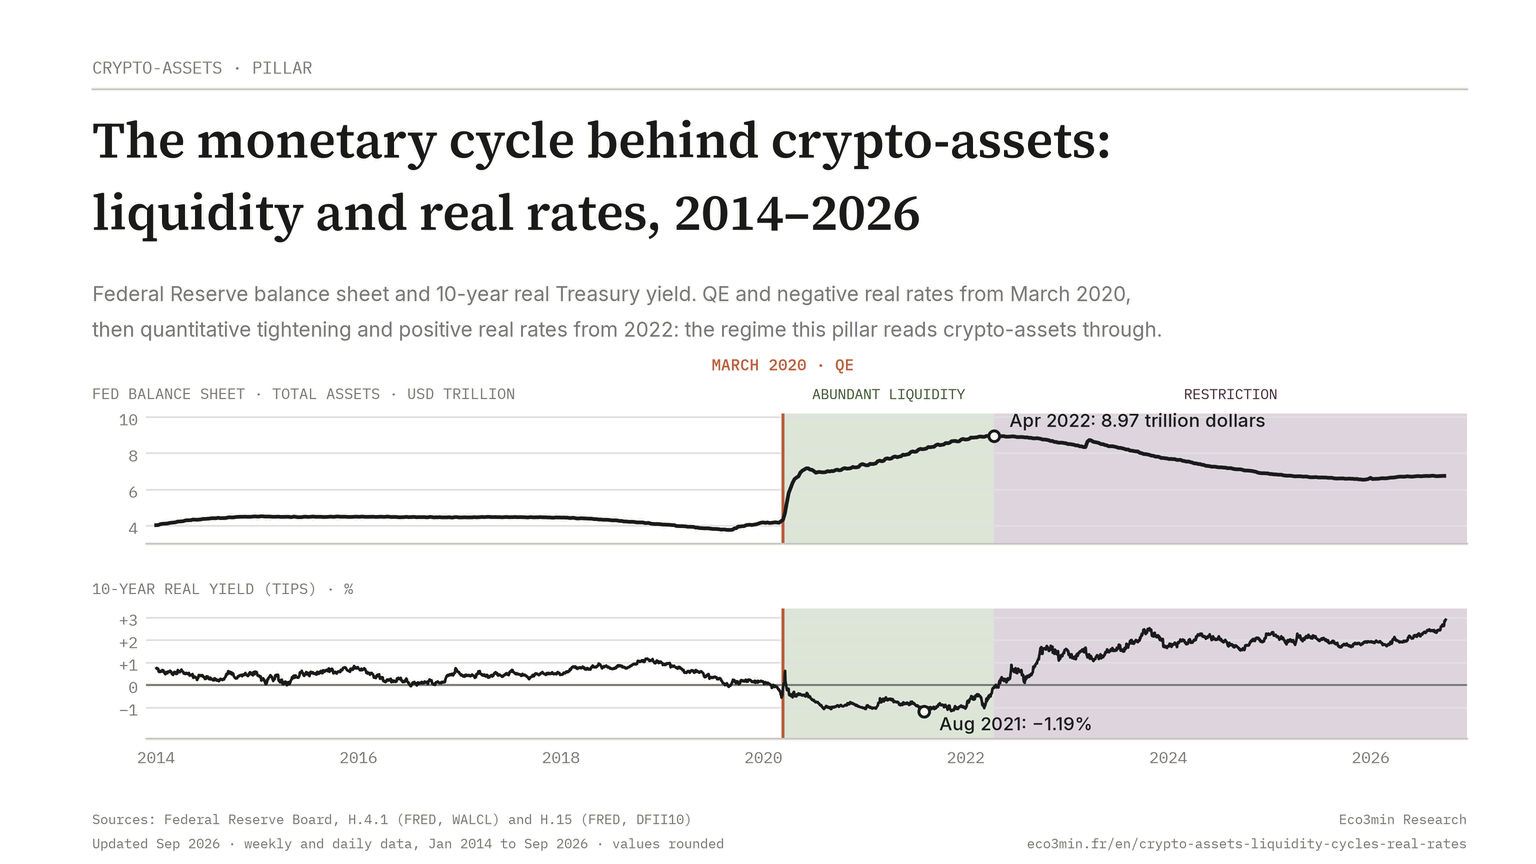
Sources: Federal Reserve Board, H.4.1 (FRED, WALCL) and H.15 (FRED, DFII10) · eco3min.fr
Liquidity cycles, real rates and financial integration: the macro drivers that shape crypto-asset valuation.
Crypto-assets do not escape the monetary cycle. They amplify its effects.
The more crypto-assets become institutionalized, the more macro-dependent they become. The original promise, a parallel monetary system decoupled from central banks and financial cycles, has collapsed when faced with real capital flows. Crypto-assets are not an alternative system; they have become an amplified extension of the existing financial system, whose valuation is governed by the same forces as long-duration traditional assets: global liquidity, real interest rates and risk appetite. The correlation between Bitcoin and the Nasdaq 100 reached 0.80 at the peak in 2022 (Bloomberg): a level that invalidates any claim of decoupling. Spot Bitcoin ETFs approved in January 2024 (SEC) attracted massive net inflows from their first months (Bloomberg), integrating Bitcoin directly into institutional circuits and mechanically strengthening its dependence on the traditional liquidity cycle. Total crypto market capitalization lost nearly three quarters of its value between its November 2021 peak and its December 2022 trough, then more than tripled by the end of 2024 (CoinGecko), in step with the global liquidity cycle rather than with any specific technological breakthrough. Directly related: Our bitcoin-versus-ethereum comparison.
To understand the economic and financial mechanisms driving crypto-assets, from liquidity cycles to valuation dynamics, see our investing for beginners hub.
This pillar proposes a strictly macroeconomic reading grid for crypto-assets, without promotion, techno-enthusiasm, or simplification. The objective is not to analyse blockchain technology or to evaluate speculative potential, but to formalize how crypto-assets interact with liquidity cycles (analysed in the sub-pillar Liquidity and financial conditions), real rates (developed in the Monetary policy pillar), market dynamics (covered in the Financial markets pillar) and geopolitical fragmentation (analysed in the sub-pillar Structural geopolitics). Product innovation and infrastructure dimensions are treated in the sub-pillar Financial innovation.
I: Nature: three categories, three economic functions
Crypto-assets denote digital assets built on distributed ledgers (blockchain) that enable exchange or representation of value without a centralized intermediary. It is important to distinguish three categories that do not share the same economic function, sensitivity to the cycle or risk profile.
Bitcoin: a fixed-supply digital monetary-like asset
Bitcoin behaves not as money but as a fixed-supply digital monetary-like asset (21 million units, cap embedded in the protocol). Its market capitalization exceeded a trillion dollars at the end of 2024 (CoinGecko), the same order of magnitude as Spain’s GDP. Its programmed scarcity, censorship-resistance and quadrennial halving (50% issuance reduction, last in April 2024) make it a privileged object of analysis in a context of U.S. fiscal deficits of 6–7% of GDP (CBO) and questions about monetary sustainability.
But Bitcoin is not a reliable inflation hedge: that narrative collapsed in 2022. Its empirical behaviour reveals a dominant sensitivity to real rates and liquidity: Bitcoin lost more than three quarters of its value between November 2021 and November 2022 (CoinGecko), during the Fed’s monetary tightening phase. It more than doubled in 2023, when financial conditions eased. That easing, measured by the Goldman Sachs Financial Conditions Index, came while policy rates stayed at their peak. For the broader framework on inflation regimes that anchors this reading, see the complete guide to inflation regimes. Correlation with the Nasdaq 100 reached 0.80 (Bloomberg). Bitcoin behaves like a long-duration asset, ultra-sensitive to the cost of capital, not like an inflation hedge. The sub-pillar Bitcoin and liquidity cycles develops this analysis.
Ethereum and programmable blockchains: experimental financial infrastructure
Ethereum introduced the concept of smart contracts: automatic execution of financial rules without an intermediary. This innovation enabled decentralized finance (DeFi), whose total value locked (TVL) peaked in November 2021 (DeFi Llama) before losing close to four fifths of its value at the 2022 trough, a swing perfectly synchronized with the liquidity cycle rather than with technological adoption. TVL then more than doubled by the end of 2024 (DeFi Llama).
Ethereum functions as a programmable financial infrastructure whose value depends on network activity (transaction fees, smart contract deployments, DeFi volumes). The transition to Proof of Stake (The Merge, September 2022) reduced energy consumption by 99.95% (Ethereum Foundation) and introduced a deflationary mechanism (EIP-1559: a portion of fees is burned). Still, Ethereum’s valuation remains governed by the same forces as Bitcoin (liquidity, real rates, risk appetite) with amplified sensitivity (beta > 1 relative to the cycle). The sub-pillar Ethereum and stablecoins expands on this analysis.
Stablecoins: systemic liquidity instruments
Stablecoins (crypto-assets pegged to fiat currencies, primarily the dollar) occupy a central function in the ecosystem. Their combined capitalization exceeded a hundred billion dollars in 2024 (CoinGecko), overwhelmingly dominated by Tether (USDT) and USD Coin (USDC). They serve as liquidity vehicles for crypto trading, gateways between crypto-finance and traditional finance, and relative safe havens during corrections.
Stablecoins raise major systemic issues. Tether holds roughly 80% of its reserves in U.S. Treasuries (Tether attestation, 2024), making it one of the largest non-bank holders of U.S. sovereign debt. The collapse of TerraUSD (UST) in May 2022, an algorithmic stablecoin that lost almost all of its value within days and erased tens of billions of dollars of market cap (CoinGecko), showed that stablecoin liquidity can vanish instantly and trigger cascading contagion (Three Arrows Capital, Celsius, FTX). The parallels with money market funds (2008 Reserve Primary Fund “breaking the buck”) are structural: abundant liquidity in normal times, potential for runs in stress.
II: Macro dependence: crypto-assets as long-duration instruments
The central thesis of this pillar is that crypto-assets operate as long-duration, zero-cash-flow assets, highly sensitive to the cost of capital. Their valuation depends on the same triad as high-multiple growth equities: global liquidity, real interest rates and expectations. When liquidity is abundant and real rates are negative, crypto-assets outperform. When liquidity tightens and real rates turn positive, they underperform, with amplified amplitude due to absence of fundamental cash flows, native leverage in the ecosystem and fragile liquidity.
The liquidity cycle as the primary determinant
Each major Bitcoin bull phase coincided with an expansion of global liquidity, and each bear phase with contraction. For a detailed macro breakdown of this relationship, see this analysis of Bitcoin and global liquidity. 2020–2021: the Fed injected $4,800bn via QE (Federal Reserve) and real rates fell to -1.19% (TIPS, Aug 2021). Bitcoin rose more than tenfold (CoinGecko). Reference release: the weekly H.4.1 release on the Federal Reserve balance sheet. 2022: the Fed raised rates from 0% to 4.50% in 9 months and began QT (-$95bn/month). Bitcoin then lost more than three quarters of its value from peak to trough (CoinGecko). In 2023–2024 it more than quadrupled from that trough, despite policy rates held at 5.25–5.50% (Federal Reserve). Financial conditions eased de facto (Goldman Sachs FCI). Correlation with Fed liquidity net measures (Fed balance sheet – Treasury General Account – Reverse Repo) has remained high since 2020 (Bloomberg).
This liquidity dependence is explained by market structure. Crypto-assets have no cash flows (no dividends, coupons, or rents): their valuation rests entirely on expectations of future prices, which themselves depend on liquidity available for risk-taking. When cash yields 5.25% risk-free (T-bills, Federal Reserve), the opportunity cost of holding a zero-yield asset rises mechanically, and flows reallocate. The sub-pillar Liquidity and financial conditions explains transmission mechanisms in detail.
The end of the decoupling promise
Bitcoin–Nasdaq correlation was close to 0 before 2020 (Bloomberg). It rose as high as 0.80 between 2021 and 2023 (Bloomberg). The explanation is structural, not cyclical: institutional entry (hedge funds, family offices, ETFs) integrated crypto-assets into the same allocation circuits as tech equities. A generalized risk-off, like the FOMC’s 75 bp hike in June 2022 or the yen carry unwind of August 2024, now affects Bitcoin and Nvidia in similar ways. “Crypto diversification” no longer exists for institutional portfolios, which is why crypto analysis belongs to the same framework as correlation dynamics in the Financial markets pillar.
Assets presented as decoupled from central banks and financial cycles.
- Bitcoin / Nasdaq correlation near 0
- Promise of diversification
- Assumed independence from liquidity
Integrated into the same allocation circuits as tech equities.
- Correlation rose as high as 0.80 (Bloomberg)
- Entry of institutions and ETFs
- Direct sensitivity to the cost of capital
Crypto cycles: euphoria and purge synchronized with the monetary cycle
A common error is to confuse technological adoption with financial cycles. Crypto bull phases do not correspond to fundamental advances: they correspond to liquidity expansions. The 2020–2022 cycle is paradigmatic. Expansion phase (2020–2021): massive QE, negative real rates, excess capital, total crypto market cap up tenfold (CoinGecko). Euphoria phase (2021): narrative amplifiers (NFTs, DeFi, Web3, “supercycle”), native leverage (DeFi protocols 10–20×, CEX up to 100×), speculation on tokens without utility, TVL at its peak. Tightening phase (2022): Fed +425 bps, QT → sequential collapses: TerraUSD/Luna (May, tens of billions of dollars erased), Three Arrows Capital (June, -$10bn), Celsius (June, withdrawal freeze), FTX (Nov, fraud + bankruptcy, -$8bn client losses). Total market cap down by nearly three quarters. Recovery phase (2023–2024): de facto easing of financial conditions, rate-cut expectations, spot ETFs approved → market cap more than tripled from the trough.
Technological narratives (AI, tokenization, real world assets or RWA) act as cyclic amplifiers: they provide intellectual justification for risk-taking in liquidity-rich phases and disappear in contraction phases. They are not the engine: liquidity cycles are. The sub-pillar Cycles and volatility develops this analysis and the structural mechanisms (fragmented liquidity, lack of stabilizing market-makers, native leverage) that explain the amplitude of swings.
AI-labelled tokens show how such a narrative behaves once liquidity recedes. From 1 November to 5 December 2025, bitcoin and ether fell and the leading AI tokens followed or did worse, after rebounds of a few days that quickly faded. The theme that carried listed technology stocks gave them no floor. The label covers three distinct economic models. Decentralised infrastructure tokens pay for or reward compute, storage and data, and still have to show they can compete on cost with large centralised providers. Utility tokens grant access to an AI service, so a price surge makes that service dearer than a fiat subscription and speculative success erodes the model. Purely narrative tokens borrow AI through name and branding, and rest almost entirely on anticipated flows.
Read in layers of risk, the market puts major assets (bitcoin, Ethereum) first, base protocols with clear utility and an execution record next, and peripheral narrative themes last: new crypto flows reach that last layer only after rotating through the majors. With the 10-year US inflation-indexed Treasury yield around 1.9% in real terms at end-2025 (FRED series DFII10), tolerance for projects without cash flows stays limited. One gauge separates usage from speculation: the ratio of a token’s daily trading volume to a proxy for real protocol activity, such as queries, compute tasks or paying users. When it stretches sharply and stays stretched for weeks, speculative flows dominate and the segment is more exposed to a liquidity reversal.
Real yields have risen since. The Federal Reserve raised its target range to 3.75-4.00% in September 2026, its first hike since July 2023, and the 10-year inflation-indexed Treasury yield (DFII10) reached 2.95% on 5 October 2026, a level not seen since November 2008. A token distributed by airdrop therefore has a higher hurdle to clear than in autumn 2025.
Between 2018 and 2021, with zero rates and abundant liquidity, airdrops mainly spread tokens as widely as possible to bootstrap a protocol’s network effects, and the dilution was easy to absorb. They now work increasingly as financing tools. The tokens handed out are a share of the project’s future capitalisation, so the economics resemble a dilutive capital increase, with winners and losers. One filter is the share of fully diluted valuation (FDV) the airdrop represents: an overly generous distribution may mainly signal that the protocol has to subsidise its usage for lack of organic demand. The vesting schedule decides when the dilution lands. Tokens fully unlocked at listing concentrate selling pressure into a few sessions, and an unlock that coincides with a weakening crypto cycle or an unexpected monetary tightening meets thinner liquidity.
III: Systemic integration: regulation, geopolitics and structural risks
Accelerated institutionalization
SEC approval of spot Bitcoin ETFs in January 2024 is an inflection point. The SEC approved 11 of them. They drew massive net inflows from their first months, and BlackRock’s iShares Bitcoin Trust (IBIT) became the fastest-growing ETF at launch (Bloomberg). Spot Ethereum ETFs followed in May 2024 (SEC). This institutionalization has three structural consequences. First, it reinforces correlation with traditional assets: Bitcoin enters the same portfolios, risk management systems and allocation flows as equity and bond ETFs. Second, it increases market depth: ETF volumes now represent a significant share of total Bitcoin volume. Third, it subjects crypto-assets to the same regulatory constraints as traditional assets, reporting, compliance and market surveillance.
Regulation: MiCA, SEC and the race to framework
The MiCA regulation, effective in the EU in December 2024, is the first comprehensive crypto-assets framework in a major jurisdiction. It imposes reserve requirements for stablecoins (1:1 reserves, segregation, audit), licensing obligations for crypto service providers, and transparency rules for token issuers. In the U.S., the approach remains fragmented between an enforcement-driven SEC and the CFTC (derivatives regulator), without a unified legislative framework, creating legal uncertainty that pushes some actors to clearer jurisdictions (EU, Dubai, Singapore).
Regulation produces two contradictory effects. It reduces systemic risk by imposing reserve norms on stablecoins and excluding fraudulent actors (post-FTX). But it also accelerates integration into the existing system, and therefore correlation with traditional cycles. The more regulation frames the space, the more crypto-assets resemble classic financial assets, and the further the “alternative system” promise drifts. The sub-pillar Regulation and structural risks expands on this analysis.
Monetary geopolitics: digital dollar, sanctions and CBDCs
Crypto-assets sit within monetary sovereignty tensions analysed in the sub-pillar Structural geopolitics and the sub-pillar Dollar and the global system. Russia used crypto-assets to partly circumvent Western sanctions after 2022: rouble flows to crypto platforms rose sharply in the weeks following the invasion (Chainalysis, 2022). China banned mining and crypto trading (2021) while launching a digital yuan (e-CNY), illustrating the choice of full monetary sovereignty over decentralization. Over 130 countries are exploring central bank digital currencies (CBDCs, Atlantic Council 2024): the rivalry between public monetary infrastructures (CBDCs) and private ones (stablecoins, Bitcoin) will shape monetary geopolitics for decades.
Structural risks: what persists despite institutionalization
Four persistent structural risks
Institutionalization reduces fraud and reserve opacity, but the fragilities inherent to crypto-asset market structure remain.
Bitcoin’s order book is much thinner than the S&P 500’s: price moves are amplified (Kaiko).
The largest addresses hold a notable share of Bitcoin supply (Glassnode); a few stablecoins concentrate most of the segment (CoinGecko). For the broader picture: how bitcoin and Nasdaq compare.
Native 10–100× leverage on derivatives, generating cascade liquidations, as in the August 2024 flash crash.
Risk shifts to code: DeFi hacks cost several billion dollars in 2022 (Chainalysis).
Institutionalization reduces some risks (fraud, opaque stablecoin reserves) but does not eliminate structural risks inherent to crypto-assets. Liquidity risk remains dominant: Bitcoin’s order book is much thinner than the S&P 500’s (Kaiko), meaning price moves are amplified versus traditional markets. Concentration risk is high: the largest addresses hold a notable share of total Bitcoin supply (Glassnode), and a few stablecoins concentrate most of stablecoin capitalization (CoinGecko). Leverage risk is native: platforms offer 10–100× leverage on crypto derivatives, generating cascade liquidations during corrections, as in the August 2024 flash crash. Technology risk persists: DeFi hacks cost several billion dollars in 2022 (Chainalysis). Companion analysis: stablecoins versus CBDCs, by the data.
What crypto-assets will not change
Crypto-assets will not eliminate economic cycles, central banks, or financial risk. Bitcoin’s programmed scarcity (21 million units) does not shield it from monetary tightening: 2022 proved this. Ethereum smart contracts do not remove counterparty risk: they shift it to code risk (bugs, exploits, governance). Stablecoins are not “safe digital dollars”: they are parity promises backed by reserves whose quality and transparency vary. TerraUST’s collapse (almost all of its value erased within days, May 2022) is empirical proof that decentralization does not prevent runs: it can accelerate them.
Analysing crypto-assets lucidly requires simultaneously recognising that blockchain infrastructure is a significant innovation in financial programmability, and that its valuation remains fully subject to the same macro forces as traditional assets. Technology can be revolutionary; its valuation does not escape the monetary cycle.
The more crypto-assets institutionalize, the more macro-dependent they become. The decoupling promise has collapsed: Bitcoin/Nasdaq correlation reached 0.80 (Bloomberg). Every major bull phase coincided with liquidity expansion (QE $4,800bn, real rates -1.19% → Bitcoin up more than tenfold); every major bear phase with contraction (Fed +525 bps → Bitcoin down by more than three quarters). Spot ETFs, carried by massive net inflows from their first months (Bloomberg), fully integrated crypto-assets into institutional circuits. Stablecoins (dominated by Tether) are systemic liquidity instruments whose reserves (largely Treasuries) tie them directly to the traditional financial system. Regulation (MiCA in the EU, SEC in the US) reduces fraud risk but accelerates convergence toward classic assets. Structural risks persist: liquidity much thinner than on traditional markets (Kaiko), native leverage, high concentration, DeFi hacks worth several billion dollars (Chainalysis). Programmed scarcity does not protect against monetary tightening: technology can be revolutionary, but its valuation remains subject to the monetary cycle.
Last updated — 29 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Bitcoin and Liquidity Cycles: Real Rates, Macro Regimes, and Market Behavior
Fed total assets and net liquidity, Wednesday levels, January 2020 to October 2026. Sources: Federal Reserve Board, H.4.1…
Crypto Regulation: What It Changes, What It Doesn’t, and Where Risks Remain
What MiCA regulates and what it leaves out, read from the text of Regulation (EU) 2023/1114: client-asset safekeeping…
Ethereum, Stablecoins and Digital Dollarization: Architecture, Risks, Power
Decentralized finance did not eliminate intermediaries: it redefined their nature. Ethereum replaced banks with protocols and legal contracts…