
The +0.5 Rule: What the NFCI’s Conventional Stress Threshold Actually Caught (1990–2026)
Executive summary
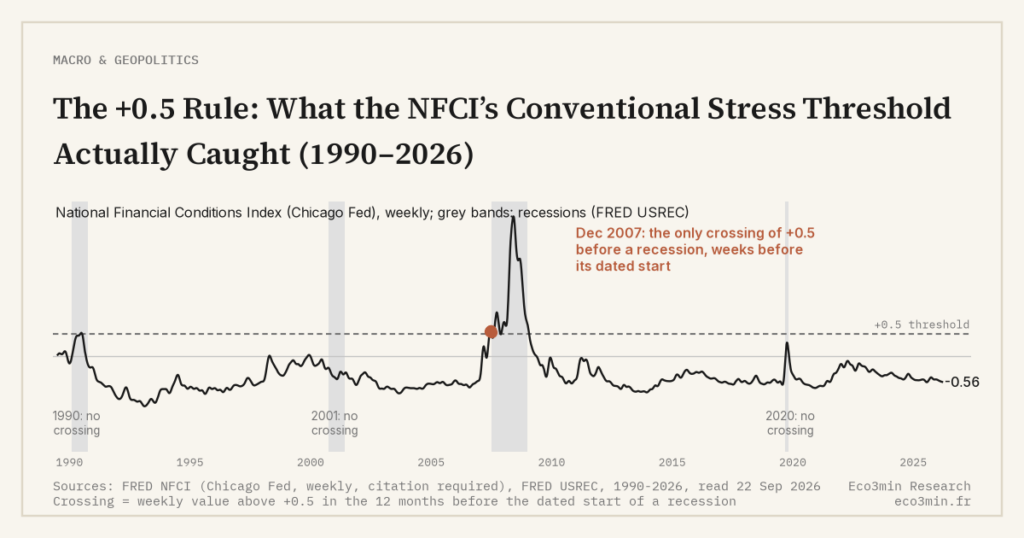
- 0 sustained leads, 1 coincident hit, 1 brief retraced signal, 2 outright misses. Strict out-of-sample audit on the four US recessions since 1990 (post-VIX, post-real-time-NFCI window): GFC = coincident hit (Dec 7, 2007); 1990 S&L/Gulf = brief signal in spring 1989 that retraced sixteen months before the recession; 2001 and 2020 = NFCI never crossed +0.5.
- The “+0.5 rule” is a backcast artifact. NFCI’s first FRED vintage is May 25, 2011. The pre-2011 record (including the 1973, 1980, 1981 recessions where the rule appears to work) is reconstructed using a dynamic factor model calibrated on the full 1971–2010 sample.
- VIX panics and NFCI stress measure different things. Of the 62 weeks since 1990 when weekly-max VIX reached 40 or higher, 34 (55%) coincided with NFCI below +0.5: equity panics with no systemic-stress confirmation (1998 LTCM, 2001 9/11, 2002 corporate scandals, 2010 Flash Crash, 2011 eurozone, 2015 China, April 2025 tariffs).
- COVID is the largest divergence on record. Weekly-max VIX peaked at 82.7 in March 2020: the highest in the series. NFCI peaked at 0.31, never reaching the +0.5 threshold.
- The Fed put has compressed NFCI. Every NFCI reading above +1.0 since 1990 belongs to the 2008–2009 GFC. No other event in the post-1990 window has produced a comparable systemic-stress signal, including 2020.
What the conventional reading claims
The Chicago Fed’s National Financial Conditions Index (NFCI) is a weighted average of 105 indicators across money markets, debt and equity markets, and the traditional and “shadow” banking systems. Constructed by Brave and Butters (Chicago Fed, 2011) and updated weekly, it is normalized to mean zero and unit standard deviation over the 1971+ sample. Positive values indicate financial conditions tighter than the historical average; negative values, looser than average.
In the years following its publication, NFCI was adopted by practitioners, financial journalists, and a generation of macro newsletters as a leading recession indicator. The conventional reading, repeated across blog posts and research notes, runs roughly as follows: sustained NFCI readings above +0.5 have preceded every US recession since 1971; the median lead time is around five months; the indicator has zero false positives. Data on this: our Chicago Fed NFCI series.
Backtests over the full 1971–2010 sample appear to support this. The series crossed +0.5 in 1971, 1978, 1979: ahead of the 1973–75, 1980, and 1981–82 recessions. The 2007–09 financial crisis produced the largest NFCI spike since the 1970s, peaking at 3.06 in November 2008; the series maximum, 5.20, dates from July 1974.
Methodology note: the look-ahead problem
NFCI was published for the first time on May 25, 2011, in FRED vintage records. Every observation dated before that (covering the 1971–2010 period that includes six of the seven US recessions in the series) was constructed retroactively. The dynamic factor model that produces NFCI assigns indicator weights estimated on the full historical sample, then applies those weights backward in time. A pre-2010 reading therefore reflects the model’s full-sample knowledge of which indicators carried information about financial stress, including stress episodes the model is trying to “predict.”
The Chicago Fed acknowledges this in the FAQ: “The history of the NFCI and the ANFCI can change from week to week depending on incoming data, data revisions, and changes in the estimated weight given each financial indicator.” Revisions are typically small in recent observations, but the structural look-ahead in pre-2011 readings is not a revision: it is the construction.
To audit the +0.5 rule, the only honest window is the post-1990 period, where the VIX exists for comparison, and within it the post-2011 sub-window for fully real-time NFCI behavior.
What 35 years of out-of-sample data show
Four US recessions have occurred since 1990: the 1990–91 S&L / Gulf War recession, the 2001 dot-com recession, the 2007–09 Great Financial Crisis, and the 2020 COVID-19 recession. The table below reports NFCI behavior in the 24 months preceding each recession’s start, dated at the cycle peak: the month before the FRED USREC series (Federal Reserve Bank of St. Louis) first equals 1.
| Recession start (peak month, FRED USREC) | Peak NFCI in 24m before | Crossed +0.5 before start? | First crossing date | Effective lead time |
|---|---|---|---|---|
| July 1990 | 0.73 (April 1989) | Briefly: 9 weeks in spring 1989, reverted | 1989-03-10 | 16 months, but signal retraced |
| March 2001 | 0.033 (June 2000) | No | – | – |
| December 2007 | 0.569 (December 2007) | Yes | 2007-12-07 | 3 weeks: coincident |
| February 2020 | -0.42 (December 2018) | No | – | – |
Two recessions (2001, 2020) occurred without NFCI ever crossing +0.5 in the two years preceding them. The 2008 crossing arrived three weeks before the official recession start, qualifying as coincident rather than leading. The 1990 case is intermediate: NFCI did cross +0.5 in March 1989, but only for nine weeks, after which it retraced to negative territory and did not return to stress levels before the recession arrived sixteen months later. By the strictest reading, sustained NFCI above +0.5 in the months preceding a recession, the post-1990 record is zero hits in four attempts.
The same picture emerges when looking at NFCI’s distribution since 1990: the index has spent 81 weeks above +0.5 (4.3% of all weeks) and 31 weeks above +1.5 (1.6%). All of the +1.5 readings, and 78 of the 81 readings above +0.5, occurred during the December 2007 – July 2009 GFC window. Outside of that single episode, NFCI has crossed +0.5 in only two brief stretches: three weeks at the 1990–91 turn (already during the 1990 recession), and the four weeks immediately preceding the GFC.
Two legitimate defenses of the index
The empirical record is what it is, but two defenses of NFCI’s design deserve to be presented in full.
First, NFCI was never intended as a strict recession predictor. Brave and Butters (2011) describe the index as a “comprehensive weekly update” on US financial conditions: a state descriptor aggregating ~105 contemporaneous indicators. The interpretation of NFCI as a leading indicator with a fixed +0.5 threshold is a practitioner convention that grew up around the series, not a property the Chicago Fed has ever claimed. Reading NFCI as describing the current state of financial conditions, the post-1990 record is consistent with what the index is designed to do: the GFC produced extreme readings, the 2020 stress was real but brief and aggressively counteracted by Fed action, and the periods between have shown looser-than-average conditions.
Second, the post-GFC compression reflects genuine structural change. The financial system of 2010–2026 is materially different from the 1970–2010 system the index was calibrated on. Post-Dodd-Frank capital and liquidity requirements, central bank standing facilities, the Fed’s enlarged balance sheet, and an order-of-magnitude expansion of pre-emptive Fed action have all reduced the type and persistence of stress events that drove NFCI’s historical signal. The 2020 COVID episode is the cleanest example: NFCI was rising fast and reached 0.31 by the first week of April 2020, but the Fed’s announcement of unlimited Treasury and MBS purchases on March 23, the standup of the PMCCF, SMCCF, MLF, and TALF facilities, and the dollar swap line expansion compressed funding stress within weeks. The index is not failing to detect stress; it is correctly describing a system in which stress is dampened faster than it would have been pre-2008. A related question: our piece on dollar swap lines.
The implication is not that NFCI is useless: it remains the single best aggregate descriptor of contemporaneous US financial conditions available at weekly frequency. The implication is that the +0.5 rule, as widely cited, describes a regime that no longer exists. What replaced it is a system cushioned by standing facilities and a larger Fed balance sheet, backstops that belong to the central-bank liquidity machinery behind US financial conditions.
The VIX comparison: equity panic is not systemic stress
The VIX, available daily since January 1990, measures the 30-day implied volatility of S&P 500 options. By construction it tracks the equity market’s pricing of near-term downside risk, not the underlying condition of the financial system. The 1990–2026 record shows that VIX panics (weekly-max readings of 40 or higher) and NFCI stress (sustained readings above +0.5) overlap less than commonly assumed.
Of the 62 weeks since 1990 when weekly-max VIX reached or exceeded 40, only 28 (45%) coincided with NFCI above +0.5. The other 34 weeks (the majority of VIX panic weeks) occurred while NFCI remained in territory the Chicago Fed would describe as looser than the historical average. See also: our side-by-side of NFCI, the VIX and HY OAS as stress gauges.
| Episode | Peak VIX (weekly max) | Peak NFCI in window | Reading |
|---|---|---|---|
| 1998-Sep / 1998-Oct (LTCM) | 45.7 | 0.02 | Equity panic, no systemic stress |
| 2001-Sep (9/11) | 43.7 | -0.34 | Equity panic, no systemic stress |
| 2002-Jul / 2002-Oct (corporate scandals) | 45.1 | -0.35 | Equity panic, no systemic stress |
| 2008-Oct / 2009-Apr (GFC) | 80.9 | 3.06 | Both at crisis |
| 2010-May (Flash Crash / Greek crisis) | 45.8 | -0.12 | Equity panic, no systemic stress |
| 2011-Aug / 2011-Oct (eurozone, debt ceiling) | 48.0 | -0.04 | Equity panic, no systemic stress |
| 2015-Aug (China devaluation) | 40.7 | -0.42 | Equity panic, no systemic stress |
| 2020-Feb / 2020-Apr (COVID) | 82.7 | 0.31 | Largest VIX print, NFCI below threshold |
| 2020-Jun (second wave) | 40.8 | -0.34 | Equity panic, no systemic stress |
| 2025-Apr (tariff announcement) | 52.3 | -0.39 | Equity panic, no systemic stress |
The pattern is consistent: the only window in which both VIX and NFCI sustained extreme readings simultaneously was the October 2008 – April 2009 stretch of the GFC. The broader catalogue of comparable equity-volatility spikes is mapped in our history of major VIX spikes from 1990 to 2026. Every other panic in the modern record was an equity-market event that did not develop into a systemic-funding-stress event. In several cases (2002 corporate scandals, 2015 China devaluation, April 2025 tariffs) NFCI was outright negative while VIX printed above 40.
In the 2008 GFC, the VIX peak preceded the NFCI peak by about one week: VIX hit its first blow-off on October 24, 2008 (79.1), then its all-time high for that episode on November 21 (80.9); NFCI continued rising into the November 28 print of 3.06, then began to roll over. The two indices were rising together but on different clocks: equity volatility prices forward expectations while NFCI aggregates contemporaneous funding metrics that lag by days to weeks.
A third read: high-yield credit spreads
The option-adjusted spread of high-yield corporate bonds over Treasuries of comparable maturity adds a third object to the comparison. The three differ on frequency (intraday for implied volatility, daily for the spread, weekly for NFCI), on scope (equities only, sub-investment-grade corporate credit, the whole financial system). They also price different things: a short-horizon equity risk premium, anticipated default risk on weaker issuers, the cyclical position of funding conditions.
Stripping out the call features embedded in most high-yield bonds leaves a measure of pure credit spread. That spread moves slowly. It reflects allocation decisions by insurers, asset managers and pension funds over horizons of several months to several quarters, which makes it a structural read.
The spread does not enter NFCI as such. The credit sub-index uses related high-yield measures, but it also carries bank lending survey answers, investment-grade default-swap prices and mortgage and consumer-loan spreads, any of which can drift away from high yield. NFCI and the spread therefore tend to move together without moving in lockstep.
A third gauge sharpens the typology of divergences. An equity spike with calm credit and calm NFCI points to an isolated market shock. Spreads widening with no echo in equity volatility or in the aggregate index point to credit stress building beneath the surface. In the run-up to the GFC, equity volatility flared, then fell back to calm levels while credit spreads stayed wide: a reader watching volatility alone saw the alarm and then the all-clear, well before the systemic phase.
What NFCI does capture, when used carefully
The audit is hostile to one specific reading of NFCI (the “+0.5 rule as recession predictor”) not to the index itself. Used as a coincident state descriptor of US funding conditions, NFCI continues to do useful work. How that descriptor is built (money markets, credit, leverage) is the subject of the NFCI, the Chicago Fed’s meta-indicator of financial conditions.
The index moved sharply higher in March 2020, peaking at 0.31 in early April before the Fed’s intervention compressed it. That movement, even though it did not reach the +0.5 threshold, was the largest single-month NFCI swing outside the GFC. A reader watching NFCI in real time during March 2020 saw funding stress building in real time: the threshold was the wrong reading, not the index.
The same applies to the August 2007 quant-fund crisis. NFCI rose from -0.53 in late June 2007 to +0.22 in early September: an eleven-week, 0.75-point swing that was the earliest aggregate signal of the subprime credit dislocation. The level did not reach +0.5 until December 2007, but the direction and pace were informative three months earlier.
Treating NFCI as a state variable, the most useful operational questions are about direction and acceleration, not threshold-crossing. The August 2007 quant-fund swing described above (and, in a different direction, the March 2020 rise that fell short of +0.5 but compressed only after the Fed’s intervention) illustrates the point: meaningful information about US funding stress was visible in NFCI’s slope and acceleration before either episode reached the conventional +0.5 cutoff. The threshold itself, in both cases, was the wrong reading.
Where the rule fails outside the recession count
Even inside the backcast, the claim of zero false positives does not survive. Recomputed on a later FRED vintage than the study’s CSV, the index stayed 19 weeks above +0.5 in 1984, from May to September, and in 1987 it spent six weeks there in the spring and 16 after the October crash. No US recession followed either episode.
The 2022-2023 tightening gives the mirror case. The Fed raised the federal funds rate by 525 basis points and CPI inflation reached 9.1% in June 2022, yet NFCI peaked at only -0.09 in October 2022, without returning above its historical average. The FRED USREC series records no recession over the period. Rate hikes of that size did not push the index above zero, a sign that transmission from the Fed to financial conditions ran differently than in earlier cycles.
The aggregate can also hide a tight component. In 2011 the leverage sub-index spent 22 weeks above +0.5 and peaked at +1.09 on September 23. The risk (-0.07) and credit (+0.12) sub-indices stayed close to zero, and the aggregate remained negative. A crossing driven by a single sub-index carries less information than one where risk, credit and leverage move together.
Where the threshold does mark something, it is the cost of funding. In the autumn of 2007, as the index climbed toward the line, the gap between the yield on Moody’s Baa-rated bonds (via FRED) and the 10-year Treasury widened by 40 basis points. It went from 2.07% on August 17 to 2.47% on November 30. The later path is often told backwards. NFCI passed 1.0 on September 5, 2008, ten days before the Lehman bankruptcy, and 2.0 on October 3. The acceleration followed the shock rather than announcing a recession that had already begun.
Key levels to watch
- Invalidation of the “no systemic stress” reading: a 13-week rise in NFCI of 0.5 points or more. Latest reading (week of 2026-03-13) is -0.486; a move to +0.014 over 13 weeks would meet this threshold. The index would shift from “looser than average” to coincident-stress territory.
- Confirmation of the current loose regime: NFCI continuing to print in the -0.40 to -0.65 range. The post-COVID record (Sep 2020 onward) shows roughly half of weekly observations in this band, with the median at -0.44, and brief excursions above -0.40 typically reverting within one to two months. A sustained move above -0.40 lasting more than four months would mark a regime change away from the current loose configuration.
- Calendar catalyst: Chicago Fed publishes NFCI every Wednesday at 8:30 a.m. CT, covering the previous Friday’s close. The 105 underlying indicators include components updated monthly; revisions to historic readings tend to be larger near the start of each month.
Past distributions are not predictive of future outcomes. The patterns described here are descriptive of the 1990–2026 historical record.
Dataset and methodology
The CSV accompanying this study contains 2,880 weekly Friday-ending observations from January 8, 1971 to March 13, 2026, with the following columns:
date: Friday-ending weeknfci. Chicago Fed National Financial Conditions Index (FRED series NFCI), in the vintage published on March 18, 2026 (ALFRED): the Chicago Fed re-estimates the full history every week, so a later download differs slightly. Pre-2011 readings are backcasted by construction.vix_week_friday: VIX close on the Friday, or the last close of the week when Friday is a market holiday (FRED series VIXCLS, daily, Cboe). NaN before January 1990 (VIX inception).vix_week_avg,vix_week_max: within-week mean and maximum of daily VIX closes.recession,recession_label: US recession flags from the FRED USREC series (Federal Reserve Bank of St. Louis), 1 in the months where USREC equals 1, so the peak month itself is 0. Labels: Stagflation I (1973–75), Volcker I (1980), Volcker II (1981–82), S&L/Gulf (1990–91), Dot-com (2001), GFC (2007–09), COVID (2020).nfci_regime, five-state classification: very_loose (<-0.5), loose (-0.5 to 0), tight (0 to 0.5), stress (0.5 to 1.5), crisis (≥1.5).vix_regime, four-state classification based on weekly max: calm (<15), normal (15–25), elevated (25–40), panic (≥40).divergence, pairwise state: aligned, vix_panic_alone, nfci_stress_alone, both_crisis, vix_elevated_nfci_loose, nfci_tight_vix_calm.
Sources: Federal Reserve Bank of Chicago (NFCI) and Cboe (VIX, series VIXCLS), both retrieved from FRED, Federal Reserve Bank of St. Louis; recession months: Federal Reserve Bank of St. Louis, NBER based Recession Indicators for the United States from the Period following the Peak through the Trough [USREC], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/USREC. Terms: all three series carry the FRED “Copyrighted: Citation required” status. Reuse is allowed with attribution to the Chicago Fed, Cboe and FRED; the file is not available under a Creative Commons licence, and anyone reusing it remains bound by the FRED terms. The file was rebuilt on September 25, 2026 from the FRED API. All statistics in this page were computed from this CSV; a numerical audit script verifying every annotated value is available on request.
Frequently asked questions
Why focus on 1990–2026 and not the full 1971–2026 series?
Two reasons. First, NFCI’s first FRED vintage is May 25, 2011: every reading before that date was constructed retroactively using a dynamic factor model calibrated on the full 1971–2010 sample. The pre-2011 record cannot be used to evaluate predictive properties because the model’s knowledge of pre-2011 stress events is partly embedded in the indicator weights it produces. Second, the VIX series begins in January 1990; comparing NFCI to VIX is only meaningful within their joint window.
Did NFCI predict the GFC?
NFCI crossed +0.5 on December 7, 2007. The business-cycle peak, December 2007 in the FRED USREC series (the month before its first recession month), was only announced in December 2008. On any strict reading, NFCI’s crossing was contemporaneous with the cycle peak rather than meaningfully leading it. The earlier directional signal (NFCI rising from -0.53 to +0.22 between June 22 and September 7, 2007) was visible roughly three months ahead of recession start. Direction and acceleration were informative; the +0.5 threshold was not.
Why did NFCI stay below +0.5 during COVID?
Two factors. First, the COVID shock was a sudden-stop event, not a gradual deterioration of financial conditions: many of the 105 NFCI inputs (credit spreads, funding spreads, equity-related indicators) did spike, but the spike was compressed within weeks. Second, the Federal Reserve’s emergency response on March 23, 2020 (unlimited Treasury and MBS purchases, the standup of PMCCF / SMCCF / MLF / TALF facilities, dollar swap line expansion) directly targeted the funding markets NFCI measures. Within five weeks the index was rolling over.
If NFCI is not a leading indicator, why do so many sources call it one?
The conventional reading developed during 2011–2014 when the GFC was the most recent recession in memory and the only one in NFCI’s then-published history. The 2008 backcast plus the 1973, 1980, 1981 backcasts together appeared to support a clean “+0.5 rule with a few months lead.” The 2020 record, the first fully out-of-sample test in the post-2011 vintage era, did not confirm the rule. The rule has survived partly because NFCI rarely makes it into mainstream financial commentary except during stress, and during stress the question of lead time is already moot.
Is there a better recession indicator?
This study is not a comparative ranking. The yield curve (2s10s or 3m10y) has a longer real-time track record than NFCI and a clean post-1976 sample. Official US recession dates are themselves announced with a typical lag of six to eighteen months. Real-time recession-detection benchmarks (the Sahm rule on unemployment, for instance) describe coincident or near-coincident transitions, not leading ones. The honest position is that no single indicator has produced a robust real-time recession lead in the post-1990 sample.
How was this study constructed?
NFCI weekly Friday-ending values come from FRED (series NFCI), in the vintage published on March 18, 2026. VIX daily closes come from FRED series VIXCLS (Cboe). VIX was resampled to weekly Friday close, plus weekly mean and weekly max, to align with NFCI. Recession months come from the FRED USREC series (Federal Reserve Bank of St. Louis), used as published. All statistics quoted in this page were computed in Python from the merged CSV and verified by an automated audit script comparing every annotated number to its CSV source. Pre-1990 calculations are reported separately and flagged as backcasted.
Citation
If you cite this study, please attribute as: Eco3min Research, “The +0.5 Rule: NFCI Stress Threshold Audit, 1990–2026,” eco3min.fr/en/nfci-vs-vix-stress-audit/, 2026. Text under CC BY 4.0; the NFCI, VIX and USREC data remain under the FRED terms.
Last updated — 30 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.