
Compound Interest Calculator: Estimate Investment Growth and Monthly Savings
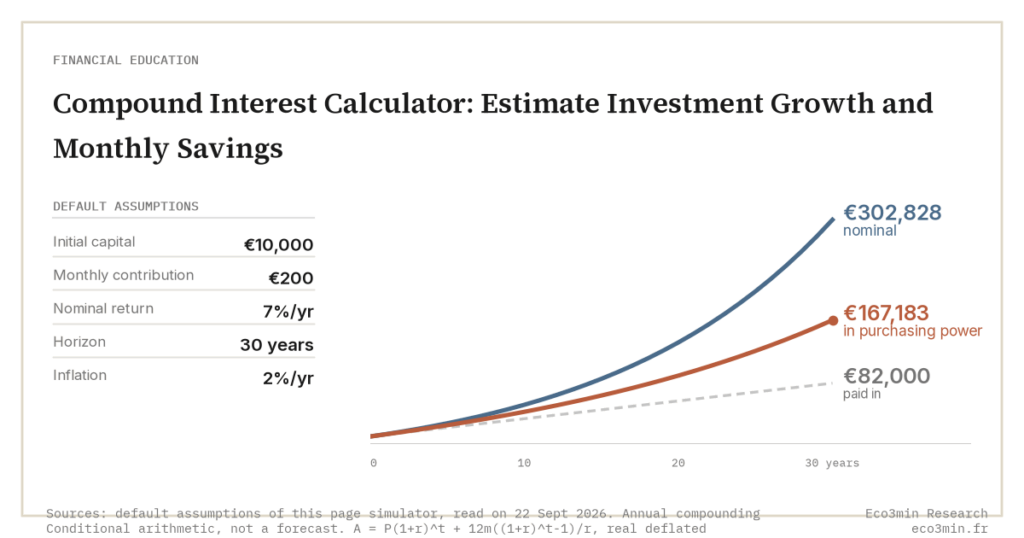
Calculator: Compound interest
Visualize the trajectory shaped by your assumptions: nominal and in real purchasing power. On the same theme: ETFs, beginner’s guide.
Compound interest is the mechanism by which the interest earned on a principal itself earns interest in later periods. Unlike simple interest, computed only on the initial principal, it folds accumulated gains back into the base. This compounding is why, over a long horizon, time becomes a more powerful lever than the amount invested. But a compound interest calculator does not predict an outcome: it tells you what happens if your assumptions about return, duration and inflation hold. The simulator below makes those assumptions visible, plotting the nominal projection and its real purchasing power.
What time does to your capital — and what it doesn't guarantee
Adjust the assumptions. The tool plots the nominal projection and its real purchasing power: the terracotta band is what inflation removes.
Conditional projection, non-predictive · assumptions entered by the user · constant return, annual compounding, end-of-period contributions · Eco3min — educational tool, neither advice nor a recommendation.
The results displayed are for strictly indicative and educational purposes. They do not constitute investment advice, a personalized recommendation, or an incentive to use any specific financial product.
The compound interest formula
The calculation rests on a standard formula, used in both personal finance and market analysis:
A = P × (1 + r/n)n×t
- A = final amount (principal + accumulated interest)
- P = initial principal
- r = annual interest rate (as a decimal: 5% = 0.05)
- n = number of compounding periods per year (1 = annual, 12 = monthly)
- t = duration in years
With annual compounding (n = 1), it simplifies to A = P × (1 + r)t — the version the simulator above uses, and the one that makes the exponential mechanism clearest.
Worked example: €10,000 invested at 5% for 10 years
€10,000 at a 5% annual rate, annual compounding, no extra contributions:
A = 10,000 × (1 + 0.05)10 = €16,289. The principal generated €6,289 in interest. What makes it remarkable is the distribution over time: the first year produces €500 of interest, the tenth €776. With simple interest, the same investment would have returned exactly €5,000 — the €1,289 gap comes solely from interest compounding on itself. As reported in the SEC’s compound interest calculator on Investor.gov. That gap widens with n as much as with t, since compounding frequency moves the outcome too — one of the distinctions running through the three formulas and their limits.
Evolution table: capital over 10 years at 5%
| Year | Starting capital | Annual interest | Ending capital | Cumulative interest |
|---|---|---|---|---|
| 1 | €10,000 | €500 | €10,500 | €500 |
| 2 | €10,500 | €525 | €11,025 | €1,025 |
| 3 | €11,025 | €551 | €11,576 | €1,576 |
| 4 | €11,576 | €579 | €12,155 | €2,155 |
| 5 | €12,155 | €608 | €12,763 | €2,763 |
| 6 | €12,763 | €638 | €13,401 | €3,401 |
| 7 | €13,401 | €670 | €14,071 | €4,071 |
| 8 | €14,071 | €704 | €14,775 | €4,775 |
| 9 | €14,775 | €739 | €15,513 | €5,513 |
| 10 | €15,513 | €776 | €16,289 | €6,289 |
Annual interest rises from €500 to €776 with no extra effort. Over the last 5 years the capital generates €3,526 of interest, versus €2,763 over the first 5: most of the gains concentrate at the end. To work backward from a monthly contribution toward a target capital, the simulator folds this compounding into regular contributions directly.
Simple vs compound interest: what’s the difference?
Simple interest is computed on the initial principal only: €10,000 at 5% returns €500 every year, indefinitely. Linear growth (I = P × r × t). Compound interest folds prior interest into the base: the second year earns on €10,500. Exponential growth.
| Criterion | Simple interest | Compound interest |
|---|---|---|
| Calculation base | Initial principal | Principal + accumulated interest |
| Growth | Linear | Exponential |
| €10,000 at 5% · 10 years | €15,000 | €16,289 |
| €10,000 at 5% · 20 years | €20,000 | €26,533 |
| €10,000 at 5% · 30 years | €25,000 | €43,219 |
The gap widens mechanically: €1,289 over 10 years, €18,219 over 30, almost double the initial principal. This is why investment horizon is, in practice, the most powerful lever in a long-term savings strategy. For further depth, see the main investment accounts for children, from custodial to 529.
Why time is the main lever
Exponential growth produces most of its effect in the later periods. Early years contribute modestly; the later years account for the bulk of the gains. The direct consequence: extending the horizon by a few years can sharply reduce the monthly effort needed to reach a goal, while shortening it imposes a disproportionate one. Discipline and regularity of contributions often matter more than the starting amount.
What the calculation doesn’t show: inflation, fees, behavior
The theoretical calculation assumes a constant rate and regular compounding. Three factors pull the real outcome away from the headline figure, and that is exactly what the simulator above makes visible.
Inflation erodes the purchasing power of accumulated capital. A 5% nominal return with 2% inflation produces a real return of about 3%. It is the difference between the figure on the statement and what it can actually buy — the distinction between nominal and real return. To isolate that effect, the dedicated real return after inflation calculator computes it directly.
Taxation and fees reduce the effective return. Depending on the wrapper, PEA vs taxable brokerage account, the tax treatment of gains differs and can materially affect the net amount.
The behavior gap. The return actually captured by the average investor is historically lower than the return of the instruments held, largely because entry and exit decisions are poorly timed. The simulator lets you switch this assumption on to gauge its effect, noting that the size of the gap (the Dalbar QAIB estimate) is contested and that other studies find it smaller.
Frequently asked questions
How do you calculate compound interest?
The formula is A = P × (1 + r/n)n×t, where P is the principal, r the annual rate, n the compounding periods per year, and t the duration. With annual compounding it simplifies to A = P × (1 + r)t. The simulator above performs this automatically and adds the effect of inflation.
What’s the difference between simple and compound interest?
Simple interest is computed on the principal only (linear growth); compound interest folds prior interest into the base (exponential growth). Over 30 years, €10,000 at 5% gives €25,000 simple versus €43,219 compound.
How long does it take to double your money?
The Rule of 72 gives a quick estimate: 72 ÷ annual rate. At 5%, about 14.4 years; at 3%, about 24 years. Reliable for rates between 2% and 15%.
Does the simulator account for inflation?
Yes. The “real purchasing power” curve deflates the nominal projection by the average inflation you enter, in today’s euros. At 2% inflation, a nominal capital loses close to half its purchasing power over 30 years.
What return should I use?
A conservative return produces more robust projections than an optimistic one. For a regulated savings account: 2–3%. For a diversified equity/bond portfolio over 15+ years: 4–5% remains a reasonable assumption on long-run historical data, with no guarantee of future results.
Key takeaways
- Compound interest creates exponential growth: interest itself earns interest.
- Time is the most powerful lever: most gains concentrate in the later years.
- The nominal figure isn’t purchasing power: inflation, fees, taxes and the behavior gap reduce the real result.
- A calculator doesn’t predict: it makes visible the assumptions under which the outcome holds.
Go further
The inverse question: “how much should I save each month to reach a goal?” → the monthly savings to target calculator. Measure what inflation really removes → the real return after inflation calculator.
Last updated — 25 September 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Retirement Withdrawal Survival Simulator: the Historical Cohort Replay (1871–2025)
The "safe withdrawal rate" is one of the most searched questions in personal finance — and one of…
France Inflation Calculator: the Value of Money Between Two Years
🧭 Eco3min analysis tool — Methodological framework Calculator — French inflation and the value of money (1901-2025) Official…
Real Return After Inflation (Calculator & Formula Explained)
🧭 eco3min analysis tool: Methodological framework Simulator: Real return after inflation Measure inflation's impact on your returns. A…