
PEA vs. Taxable Brokerage Account: Which Should You Choose in France?
Educational content only. This does not constitute personalized tax or investment advice. Consult a licensed financial professional.
Tax laws and regulations are subject to change. Account choices depend heavily on your personal situation, investment horizon, and risk tolerance.
Note: The PEA (Plan d’Épargne en Actions) is a tax-advantaged investment account available only to French residents, similar in concept to a stocks and shares ISA in the UK.
Before acquiring your first ETFs or stocks, you need an account to hold them. For French tax residents, the two main options are the PEA (Plan d’Épargne en Actions) and the standard taxable brokerage account (Compte-Titres Ordinaire). A deeper analysis appears in how tax wrappers compare by their contents. Here is an objective breakdown of their differences.
1. The PEA: Frequently Used by Retail Investors
The PEA is a regulated account created by the French government to channel savings into European companies.
✅ Conditional Tax Advantages
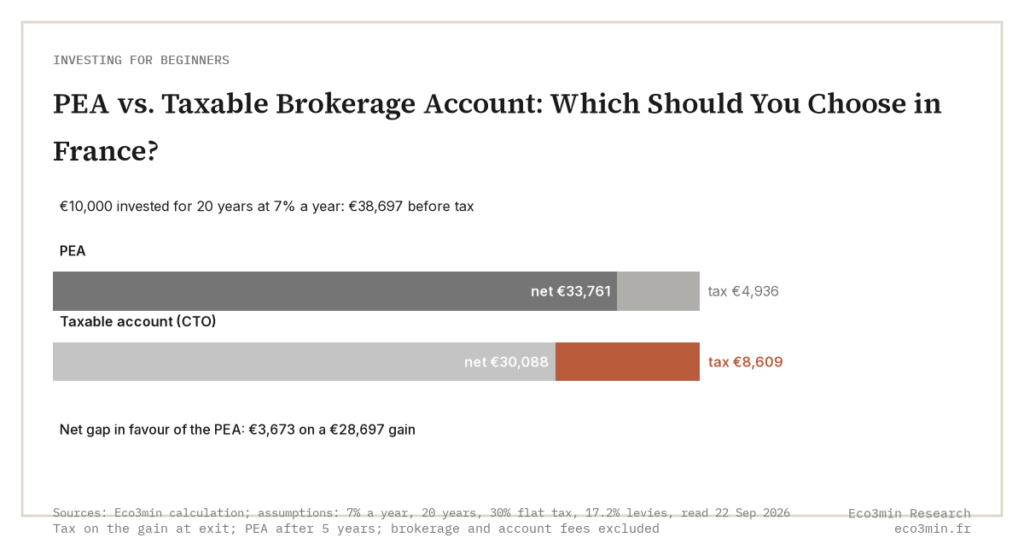
- Tax exemption under conditions: After holding the account for 5 years, capital gains realized within the account are exempt from standard income tax (under current law, only the mandatory social charges apply, 18.6% since 2026 (17.2% before)).
- Compatible with specific ETFs: While the PEA targets European equities, certain “synthetic ETFs” allow investors to gain exposure to global indices (like the S&P 500 or MSCI World) while meeting the legal eligibility criteria, a structure explained in how ETFs replicate indices and adapt to regulatory constraints.
❌ Regulatory Constraints
- Contribution Ceiling: Total cash deposits are capped at €150,000.
- Initial Lock-in Period: Making any withdrawal before the 5-year anniversary typically results in the permanent closure of the account.
- Restricted Investment Universe: It is not possible to directly hold individual non-EU stocks (such as US tech companies) or direct bonds within this account.
2. The Taxable Brokerage Account: The Universal Account
The standard taxable brokerage account (Compte-Titres Ordinaire) is not subject to any deposit ceilings or geographical restrictions, but it offers no specific tax benefits. That unlimited, unsheltered account sits at a specific point in the sequence of account funding.
🌍 Unrestricted Access
It allows investment across all global markets and asset classes, including international stocks, bonds, and specialized ETFs.
💸 Full Availability
There is no cap on deposits, and funds can be withdrawn at any time without triggering the account’s closure. Further reading: how to choose a brokerage account.
The Tax Framework: Capital gains and dividends generated within a taxable brokerage account are generally subject to the French Flat Tax (Prélèvement Forfaitaire Unique) of 31.4% when realized (30% until 2025; the 2026 social security financing act raised the CSG share). The level at which that single 31.4% rate gives way to the progressive scale finds its full framing in the bracket where flat beats progressive.
Summary: How Are These Accounts Used?
- The PEA as a Foundation: It is frequently used as a primary account for long-term strategies. Some investors choose to open a PEA early, even with a minimal deposit, solely to start the 5-year tax clock.
- The Taxable Brokerage Account as a Complementary Tool: A taxable brokerage account can be utilized in addition to a PEA, depending on specific investment goals (for instance, if the PEA ceiling is reached, or to access assets that are not PEA-eligible).
Last updated — 2 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Regulated and tax values: the rates, indices, caps and brackets with legal effect cited on this page are set by official decision, change over time and apply according to individual circumstances. Only the official publication in force on the relevant date is authoritative (for example the Journal officiel, INSEE, Banque de France, the IRS or the Social Security Administration). To revise a rent, sign or challenge a contract, or file a return, check the value at the source or with a professional.
Read next
Full pillar →The Investing Mistakes That Cost Beginners the Most
Disclosure: Independent educational content. Eco3min does not provide personalized investment advice. All investing involves risk of loss. The…
ETFs Explained: Understand the Tool Before You Use It
Disclosure: Independent educational content. Eco3min does not sell financial products or provide personalized investment advice. All investing involves…
Real vs. Nominal Returns: The Most Important Distinction in Personal Finance
Disclosure: Independent educational content. Eco3min does not provide personalized investment advice. All investing involves risk of loss. A…