Yield Curve Steepening and Flattening: Bull and Bear, Explained
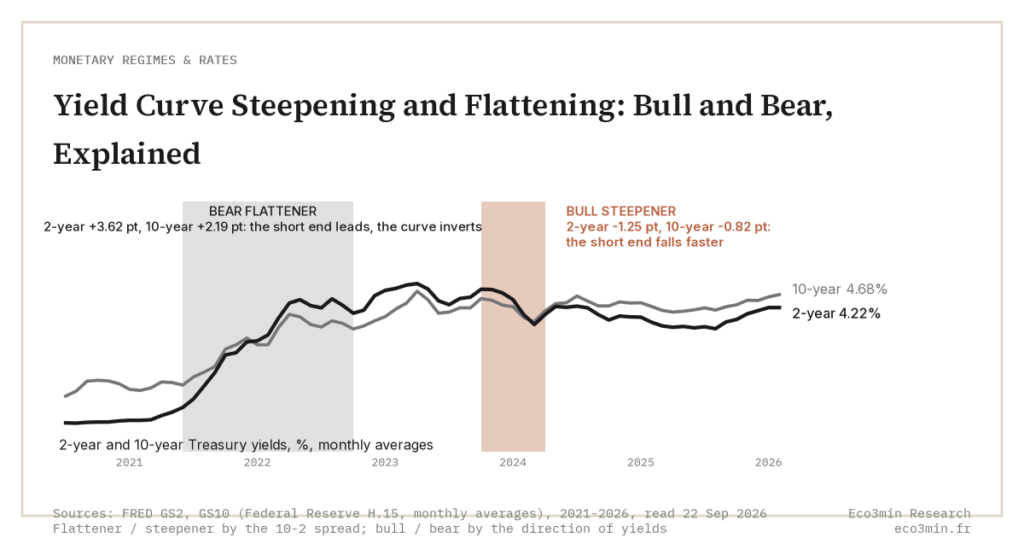
The US Treasury yield curve changes shape in two basic ways: it steepens (the gap between long and short yields widens) or flattens (the gap narrows). Each move can happen while yields are broadly falling — a “bull” move, where bond prices rise — or broadly rising — a “bear” move, where prices fall. That gives four combinations: the bull and bear steepeners and flatteners defined below.
The distinction is not cosmetic. Which end of the curve drives the move — the policy-sensitive front end or the growth- and inflation-sensitive long end — is exactly what each label encodes, and it is why the four shapes tend to show up in such different macro contexts.
For the historical record of these moves, the 2s10s yield curve dataset tracks the 10-year minus 2-year spread back to 1976. On how a sustained flattening into inversion has related to recessions, see the credit-channel mechanism.
Last updated — 6 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Manage Consent
We use cookies to keep the site running and, with your consent, to measure audience so we can improve our content. You can accept, decline or customise your choices at any time.
Fonctionnel Always active
Technical access or storage is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of transmitting a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistiques
The technical storage or access that is used exclusively for statistical purposes.Le stockage ou l’accès technique qui est utilisé exclusivement dans des finalités statistiques anonymes. En l’absence d’une assignation à comparaître, d’une conformité volontaire de la part de votre fournisseur d’accès à internet ou d’enregistrements supplémentaires provenant d’une tierce partie, les informations stockées ou extraites à cette seule fin ne peuvent généralement pas être utilisées pour vous identifier.
Marketing
L’accès ou le stockage technique est nécessaire pour créer des profils d’internautes afin d’envoyer des publicités, ou pour suivre l’utilisateur sur un site web ou sur plusieurs sites web ayant des finalités marketing similaires.