
Dollarization vs de-dollarization: the slow reshuffle
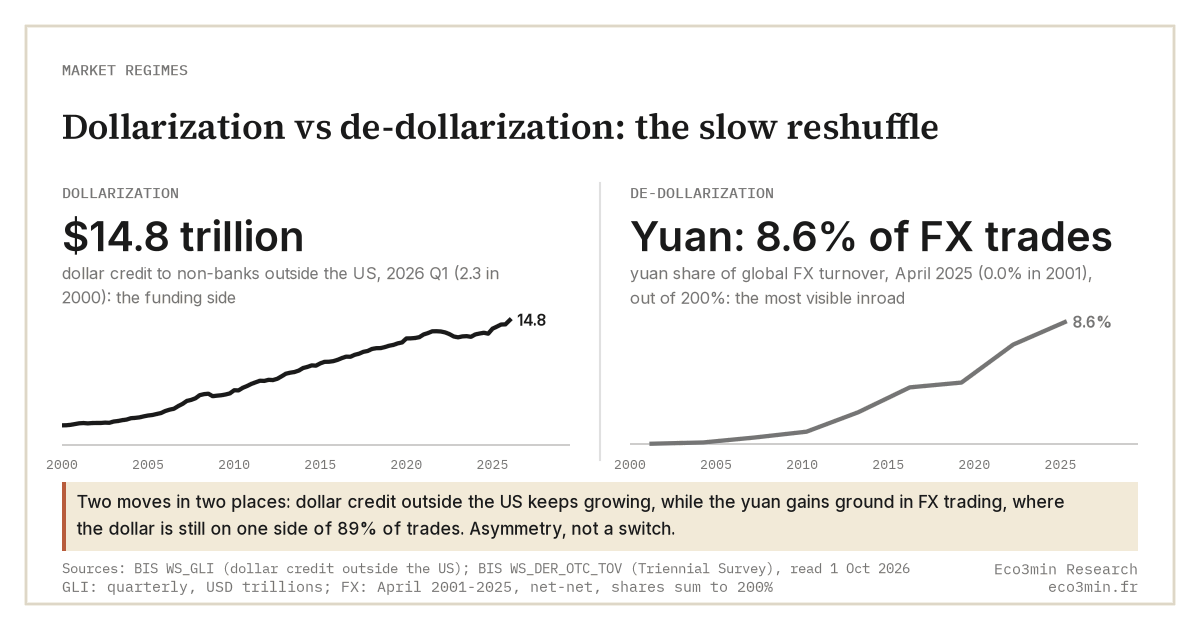
Dollarization is the global economy’s entrenched reliance on the US dollar for invoicing, funding and reserves; de-dollarization is the deliberate, gradual effort to reduce it. The two are not symmetric: the dollar’s share of official reserves has fallen from its 2001 peak to about 58% in 2024, yet its share of global payments and trade finance has held or risen. The real distinction is where each shows up: de-dollarization is visible in reserve composition and gold, not yet in the dollar’s core role as the world’s medium of exchange and safe asset.
In this comparison
Why this comparison matters
“De-dollarization” has become one of the most over-read terms in macro. Headlines pair a falling dollar reserve share with talk of a BRICS currency and conclude the dollar is being dethroned. The data tells a more divided story: the dollar is slowly losing ground as a store of value while holding, or gaining, ground as a medium of exchange. Understanding the difference between dollarization and de-dollarization is less about picking a side than about knowing which monetary function a given headline actually measures. Related reading: a closer look at asset-class correlations across regimes.
What dollarization is
Dollarization is the dependence of the global economy on the US dollar across the three classic functions of money: unit of account (trade invoicing), medium of exchange (payments and funding), and store of value (official reserves). In its strongest form it becomes currency substitution, where a country uses the dollar domestically, as Ecuador and Panama do. As of 2024 the dollar accounted for about 58% of disclosed official reserves and the large majority of trade-finance contracts (Federal Reserve), far ahead of the euro and the renminbi. It was also the leading currency for international payments on SWIFT. Its dominance rests less on US economic weight than on the depth, liquidity and openness of dollar markets: features no rival currently matches.
→ The complete explanation: What makes the dollar the global reserve currency?
What de-dollarization is
De-dollarization is the deliberate effort by some central banks and governments to reduce that dependence, diversifying reserves into other currencies and gold, settling bilateral trade in local currencies, and building payment channels that bypass dollar infrastructure. Its main accelerant has been the weaponization of the dollar: when the US and its allies froze roughly half of Russia’s foreign reserves in 2022, reserve managers elsewhere drew the lesson that dollar assets carry political risk. The clearest evidence is gold: central banks bought more than 1,000 tonnes in each of 2022, 2023 and 2024, roughly double the 2010–2021 average (World Gold Council). What de-dollarization has not produced is a rival reserve currency; the renminbi’s share of official reserves has stayed marginal for years.
→ Full account: How has the weaponization of the dollar changed reserve management?
The key differences
What each describes. Dollarization is a state: the dollar’s entrenched position across every monetary function. De-dollarization is a process, and a narrow one: a gradual, deliberate reduction concentrated almost entirely in how reserves are held. They are not two sides of a balanced scale; one is a standing structure, the other a slow trim at its edges.
Where each shows up in the data. This is where the two narratives diverge most sharply. De-dollarization is measurable in reserve composition (the dollar’s reserve share has fallen from its 2001 peak to about 58% in 2024, Federal Reserve) and in gold, whose share of official reserves has more than doubled since 2015. But in the dollar’s core functions the trend runs the other way: its share of international payments on SWIFT climbed to a multi-year high in early 2025, and its role in trade finance and dollar funding has barely shifted. Contrary to the assumption that a falling reserve share signals a broad retreat, de-dollarization has touched the store-of-value function while leaving the medium-of-exchange function intact.
Pace and driver. Dollarization is self-reinforcing: the more trade and debt are denominated in dollars, the more everyone needs dollars, a network effect that has outlived every prediction of decline since the 1970s. De-dollarization advances in fits, driven by geopolitical risk rather than economics, and overwhelmingly through gold rather than a competing currency, because no alternative yet offers the same combination of depth, liquidity and an open capital account.
How they behave across regimes
The balance between dollarization and de-dollarization shifts with the regime. In episodes of acute financial stress (the 2008 crisis, the March 2020 dash for cash) dollarization intensifies: capital flees to dollar safety, a global dollar funding squeeze appears, and the dollar’s usage rises precisely when confidence in the system is lowest, because no other asset offers comparable depth. In episodes of geopolitical rupture (the 2014 sanctions on Russia, the 2022 reserve freeze) de-dollarization accelerates at the margins, visible in gold buying and reserve diversification. And in strong-dollar regimes, dollar-denominated debt across emerging markets makes the dollar harder, not easier, to abandon. The switching parameter is the availability of a credible alternative safe asset: one combining scale, liquidity, rule of law and open capital flows; until one exists, de-dollarization stays marginal regardless of political will.
Diversifying reserves is not the same as displacing the dollar: the first is under way, the second is not.
→ Framework: The US dollar in the global monetary system
The common confusion
The common error is to read a falling dollar reserve share as the dollar’s decline, full stop. Two things get conflated. First, reserve composition is only one of the dollar’s roles; the headline number can fall while payments, invoicing and funding hold steady, which is what has happened. Second, much of the recent decline is not active selling but valuation: when the dollar weakens, the dollar-measured value of a fixed basket of non-dollar reserves rises mechanically, shrinking the dollar’s percentage without any central bank trading a thing. In the first half of 2025, when the dollar index fell more than 10%, the great majority of the reserve-share decline came from this exchange-rate effect; adjusted for it, the share barely moved. Pure valuation at work, that exchange-rate effect ties reserve statistics to how currency markets interact with international monetary regimes.
A further confusion runs through the exchange rate itself. A strong dollar index measures the currency’s relative price against trading partners, not its share of reserves, payments or debt. A dollar losing reserve share can coexist with a high index if weaker official demand is offset by transactional demand, so a strong dollar neither refutes nor confirms de-dollarization. The two dimensions are best read side by side.
The functions also differ in inertia. International debt issuance is the steadiest channel, because borrowing in a currency presupposes a deep secondary market in which to place the bonds, and the Treasury market remains the default safe asset of global institutional investors. Where reserve managers have diversified, the gains have gone mostly to smaller currencies that official statistics do not break out, then to the Canadian and Australian dollars, well ahead of the renminbi. Political fragmentation and economic dominance can therefore coexist, because monetary and political functions do not align mechanically.
Practical observation
What the data suggests for framing your own analysis:
- Question to ask yourself: when a headline reports de-dollarization, is it describing a change in reserve composition, or a change in the dollar’s role as the world’s medium of exchange and safe asset?
- Data to monitor: the gap between the dollar’s reserve share (falling) and its SWIFT payment share (stable-to-rising); the constant-exchange-rate reserve share, which strips out valuation; central bank gold flows; foreign holdings of US Treasuries.
- Historical parallel: sterling held a meaningful reserve share for decades after Britain’s economic peak; the dollar’s share of payments on SWIFT reached a multi-year high in January 2025, even as its reserve share sat near multi-decade lows.
- What the literature documents: the incumbency and network effects of international currencies (Eichengreen), and the IMF’s own decomposition of reserve-share moves into flow and valuation effects.
This is descriptive information to help you frame your own analysis. Eco3min does not provide investment advice.
Go deeper
📊 Full study: The strong dollar as a structural regime
📁 Dataset: The US dollar and global crises, 1973–2023
Related guides
Frequently asked questions
How is dollarization different from de-dollarization?
Dollarization describes the global economy’s entrenched reliance on the US dollar across all three functions of money: invoicing, payments and funding, and reserves. De-dollarization describes the deliberate, gradual effort to reduce that reliance, mostly by diversifying official reserves and accumulating gold. The key asymmetry is scope: dollarization is a standing structure spanning every monetary function, while de-dollarization, so far, is concentrated almost entirely in how reserves are held. One is the system; the other is a slow adjustment at its edges.
Not on its own. The reserve share is only one of the dollar’s roles, and it has fallen from its 2001 peak to about 58% in 2024. But over the same recent period the dollar’s share of international payments climbed to a multi-year high, and its role in trade finance and dollar funding held firm. Much of the reserve-share decline, moreover, reflects valuation rather than selling: when the dollar weakens, the dollar value of non-dollar reserves rises mechanically. A falling reserve share documents diversification in the store-of-value function; it does not, by itself, show the dollar losing its role as the world’s medium of exchange.
Why are central banks buying so much gold?
After the US and its allies froze a large share of Russia’s foreign reserves in 2022, reserve managers in many countries concluded that dollar and euro assets carry political risk that gold does not: gold has no counterparty and cannot be frozen remotely. Central banks responded by buying more than 1,000 tonnes in each of 2022, 2023 and 2024, roughly double the previous decade’s pace (World Gold Council). The share of gold in official reserves has more than doubled since 2015. The buying is best read as diversification away from dollar political risk, not a bet against the dollar’s market role.
Last updated — 20 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Fed vs ECB: two mandates compared
The Federal Reserve operates under a dual mandate (maximum employment and stable prices) set by the US Congress.…
Value vs growth: how the styles diverge across regimes
Value buys cheap cash flows today; growth pays up for cash flows years out. The real difference is…
Stocks vs bonds: what the long-run data shows
Stocks are residual claims on corporate earnings; bonds are fixed claims on a defined stream of payments. Over…