
Asset Class Correlations and Regime Shifts in Financial Markets
Sources: Kenneth R. French Data Library (market portfolio, total return); Federal Reserve Board H.15 via FRED (DGS10, 10-year Treasury return estimated from the month-end yield) · eco3min.fr
Correlations between asset classes are not constants: they are variables dependent on the macroeconomic regime. Their sudden breakdown precedes crises and invalidates the protections diversification seemed to guarantee.
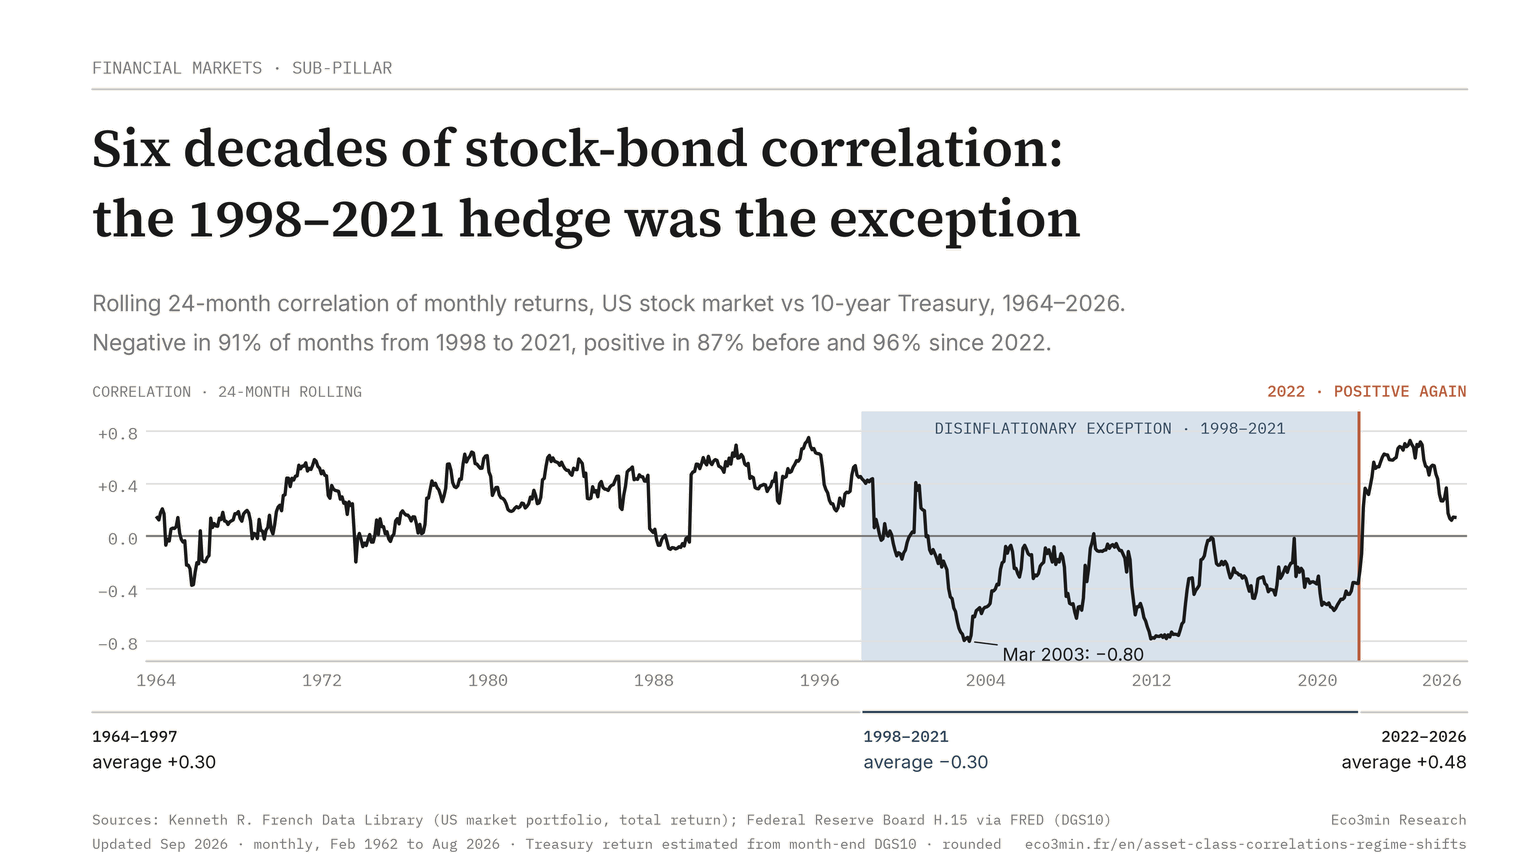
In 2022, the 60/40 portfolio, the foundation of institutional allocation for two decades, experienced its worst performance since 1937: −18.0% for a portfolio of 60% US equities and 40% 10-year Treasuries, rebalanced annually (Eco3min calculation on the annual returns published by Aswath Damodaran, NYU Stern). The S&P 500 fell 19.4% (S&P Global). The 10-year Treasury lost 17.8%, its worst year since the series began in 1928 (Damodaran). The Bloomberg US Aggregate Bond Index declined 13%, its first double-digit annual loss in history. Equities and bonds both ended the year in the red together, which Damodaran’s series shows only four other times since 1928 (1931, 1941, 1969 and 2018). The 24-month rolling correlation between the US stock market and the 10-year Treasury, negative on average from 1998 to 2021 (−0.30), turned positive again in March 2022 (Eco3min calculation, Kenneth R. French Data Library and FRED). The entire framework of modern portfolio theory, built on the assumption that bonds protect when equities fall, was invalidated in one year by a regime shift.
This was not an anomaly. It was a correlation regime shift, and understanding these regimes is the core competency of modern asset allocation. The analysis is carried further in this analysis of strategic vs tactical asset allocation. Correlations are products of the macroeconomic regime: when the regime changes, correlations change, and portfolios built on prior correlations disintegrate.
Equities and Bonds: The Relationship That Changed, and Why
The negative equity/bond correlation is not a law of nature; it is the product of a specific monetary regime: low inflation, responsive central banks, and a secular decline in rates. That regime prevailed from 1998 to 2021. The Fed funds rate moved from 6.5% (2000) to 0.25% (2008), briefly rose to 2.5% (2018), then returned to 0% (2020). As reported in the Federal Reserve’s history of FOMC target-rate decisions. During this period, every economic slowdown produced falling rates → rising bond prices → portfolio protection when equities declined. The equity/bond correlation was negative in 91% of months from 1998 to 2021, averaging −0.30 (24-month rolling correlation, Eco3min calculation). The analysis is carried further in the most common misreadings of asset allocation.
Before 1998, the correlation was positive, and remained so for most of the 20th century. From 1964 to 1997, the 24-month rolling correlation between the US stock market and the 10-year Treasury averaged +0.30, and was positive in 87% of months (Eco3min calculation, Kenneth R. French Data Library and FRED). During the 1970s-1980s (high inflation, rising rates), it exceeded +0.50 in 53 of 240 months, peaking at +0.64 in March 1979. Equities and bonds rose and fell together: exactly as in 2022. The 1998-2021 period of negative correlation is not the historical norm: it is the exception, produced by a disinflationary and accommodative monetary regime that will not automatically repeat. This is worked through in macro-financial glossary.
The determining factor is inflation. When inflation is the dominant problem (1965-1982 and 2022+ regimes), central banks raise rates to fight it: a configuration mapped in the complete guide to inflation → bonds fall (higher rates = lower prices for existing bonds) at the same time equities suffer from tighter financial conditions. Correlation turns positive. When growth is the dominant problem (2001, 2008, 2020 regimes), central banks cut rates → bonds rise at the same time equities fall. Correlation turns negative. The full transmission mechanism is analyzed in the study on interest rate impacts on financial markets.
One channel explains why both legs fall together when inflation leads. An equity is worth the present value of future earnings and a bond the present value of its contractual cash flows, and both discount rates embed the same real rate. When the real rate climbs, both denominators tighten at once, so the positive correlation reflects a shared exposure rather than a statistical coincidence. The sign also moves late. The flip lags the inflation regime: after inflation settled at a low and stable level, the correlation stayed positive for years before turning negative. A portfolio model calibrated only on the disinflationary decades embeds a negative correlation as a structural input, and understates the risk that a regime change makes losses converge.
The allocator’s question is therefore not “are equities and bonds uncorrelated?” but “which inflation regime are we in, and what correlation does it produce?” As long as inflation remains above target (2%) and central banks maintain a restrictive bias, bond protection within the 60/40 framework remains impaired: a reality the Allocation Foundations sub-pillar incorporates into its portfolio construction frameworks.
Do equities and bonds protect each other?
SAME TWO ASSETS · FLIP THE REGIMECorrelation is not a property of the assets: it is a product of the macroeconomic regime. Flip the regime and you invert the diversification.
The Dollar: An Asymmetric Amplifier of the Global Financial System
The broad trade-weighted dollar index appreciated 16% between May 2021 and September 2022 (Federal Reserve), a large move, though 2008-2009 and 2014-2015 had seen stronger ones. Simultaneously: the MSCI Emerging Markets Index fell sharply, the World Bank’s non-energy commodity price index lost 18.5% between its April 2022 peak and September 2022, and emerging currencies slumped, with the Japanese yen also weakening against the dollar. This is not coincidence: it is the strong-dollar transmission mechanism.
The dollar occupies a unique position in the global financial architecture: reserve currency (56.7% of reserves with a reported currency composition in the second quarter of 2026, IMF COFER), invoicing currency (40% of global trade ex-eurozone, BIS 2022), and debt denomination currency (~60% of emerging external debt denominated in USD, World Bank). When the dollar strengthens, three transmission channels activate simultaneously. First channel: commodities, priced in dollars, become mechanically more expensive for non-US buyers → demand contracts → dollar prices fall. Second channel: dollar borrowers (emerging corporates and sovereigns) see the real cost of debt rise → financial stress → capital flight → further currency depreciation. Third channel: global investors repatriate capital into dollars (flight to quality) → selling of emerging assets → vicious depreciation loop.
The asymmetry is structural: the dollar appreciates sharply during stress episodes (2008, 2020, 2022) and falls back only more modestly during expansion phases. This asymmetry gives the dollar hedging value in portfolios that the study of the strong dollar and performance hierarchy quantifies by asset class and geography. The Dollar and International Monetary System sub-pillar analyzes the structural dynamics sustaining this centrality.
Gold and Real Rates: An Anchor That Temporarily Drifted
The relationship between gold and US real rates (10-year TIPS) is the most stable cross-asset correlation: a strongly inverse correlation from 2006 to the early 2020s. The mechanism is straightforward: gold pays no dividend or coupon. Its opportunity cost is the real yield on risk-free assets. When real rates are negative (TIPS -1.19% in August 2021, Fed), holding gold carries no cost: the alternative yields less than inflation. Gold set what was then a record in August 2020, at $1,969/oz as a monthly average (World Bank, Pink Sheet), as real rates sank below zero; their trough came only a year later.
But since 2022, this relationship has partially decoupled. Real TIPS yields rose from -1.0% to +2.40% (Fed, October 2023): gold’s opportunity cost surged. Based on the historical relationship, gold should have fallen to $1,400-1,600/oz. Instead, it reached new records, above $2,400/oz as a monthly average from August 2024 (World Bank). Explanation: net central bank purchases exceeded 1,000 tons a year from 2022 to 2024 (World Gold Council). China (PBOC), Poland (NBP), Singapore (MAS), and Turkey (CBRT) are accumulating heavily. These purchases are strategic (de-dollarization, reserve diversification post-freeze of Russian reserves in 2022) and insensitive to opportunity cost: driven by geopolitical logic, not financial optimization.
Gold also maintains a complex correlation with the dollar: both share safe-haven characteristics, but the metal is priced in dollars, a strong dollar mechanically weighs on USD gold prices even if physical demand remains stable. The allocator’s question: is gold still a real-rate asset, or has it become a geopolitical asset whose valuation depends as much on emerging central bank reserve policy as on TIPS spreads? The breakdown in Gold: price determinants explores this structural decoupling.
Credit Spreads: The Signal Equities Ignore, Until They Can’t
The yield spread between corporate bonds and Treasuries of similar maturity is the most reliable leading indicator of systemic stress. The US high-yield spread (ICE BofA US High Yield Index) widened sharply in 2022, then fell back to 292 bps by late 2024 (ICE BofA, via FRED): the bond market signaled and then absorbed stress before equities fully reacted. Historically, the HY spread surged well ahead of the equity trough in the 2001 and 2008 recessions. The Eco3min gallery of crashes and crises places them on a common timeline.
The investment-grade spread (ICE BofA US Corporate Index) is less volatile but equally informative in trend: its widening through 2022 signaled tightening financing conditions that later pressured equity valuations. The correlation between IG spreads and the S&P 500 is structurally negative: when spreads widen, equities tend to fall. But spreads move first: the bond market, dominated by institutions with substantial analytical resources (PIMCO, BlackRock, Vanguard), incorporates credit deterioration before equity markets. The inverted yield curve → credit → real economy transmission formalizes the channels through which these stresses propagate.
Flight to Quality: The Moment Diversification Dies
The most destructive phenomenon for diversified portfolios occurs during systemic panics: all correlations converge toward +1 among risky assets (everything falls together) and toward -1 versus ultimate safe havens. In March 2020, over a few sessions (March 9-16), the S&P 500, investment-grade credit, high yield, emerging markets and commodities all fell simultaneously (Bloomberg). The dollar rose (+3.2% for the Fed’s broad index from March 9 to 16); even the 10-year Treasury was sold, its yield moving from 0.54% to 0.73% over the period (Fed, via FRED). The correlation between the S&P 500 and MSCI World ex-US approached one in one week: “geographic diversification” ceased to exist.
The same pattern occurred in every major crisis: August 2015 (yuan devaluation, correlations between emerging and developed markets close to one for several weeks), February-March 2018 (Volmageddon: VIX +116% in one session on February 5, Cboe via FRED, and intra-equity correlations at their highs), September 2008 (Lehman, extreme global correlations for months). The asymmetry is structural and documented (Longin & Solnik 2001, Journal of Finance; Ang & Chen 2002): correlations rise during downturns and remain stable or fall during upturns. Diversification works when it’s not needed, and fails when it’s most valuable.
This is why the most dangerous market moments occur when conventional risk indicators (low VIX, compressed spreads, weak correlations) appear most reassuring: these calm conditions are precisely those that precede brutal correlation convergences.
The Three Correlation Regimes: and How to Identify Them
Rather than relying on static average correlations (the 60/40 mistake), the productive approach is to identify the prevailing correlation regime and the macroeconomic conditions that produce it.
Three regimes, three correlation behaviors
The dominant macroeconomic regime sets the correlation across asset classes, and therefore how well diversification works. Eco3min charts this regime dependence empirically in the Eco3min heatmap of how each asset class behaved across macro regimes.
Risk-on / risk-off · 2009-2021
Driver: Fed liquidity. Risky assets rise and fall together (intra-risk correlation +0.60 to +0.80); safe havens mirror them negatively.
Inflation · 2022, 1970s-1982
Driver: inflation and the central-bank response. Equities and bonds suffer together as rates rise; correlation turns positive (+0.30 to +0.50) and the 60/40 breaks down.
Divergent growth · 2023-2024
Driver: diverging trajectories across regions and sectors. Global correlations fragment; dispersion surges: Magnificent Seven +75% in 2023 (Goldman Sachs), far ahead of the S&P 500 equal-weight.
“Risk-on / Risk-off” regime (2009-2021). Global liquidity conditions dominate price formation. All risky assets rise together when liquidity expands (QE, zero rates) and fall together when it contracts. Intra-risky-asset correlation is high (+0.60 to +0.80); correlation with safe havens (Treasuries, dollar) is symmetrically negative. This is the TINA regime (There Is No Alternative): zero-yield risk-free assets push investors into risk. The driver is the Fed and net liquidity. The Liquidity and Financial Conditions sub-pillar deconstructs this mechanism.
“Inflation” regime (2022, 1970s-1982). Inflation becomes the dominant driver. Equities and bonds suffer simultaneously from rising rates. Equity/bond correlation: positive (+0.30 to +0.50). Real assets (commodities, gold, early-cycle real estate) and short-duration assets (cash, T-bills, floating-rate instruments) outperform. The 60/40 portfolio breaks down. The driver is inflation and central bank response. The rate hikes and differentiated market impacts illustrate how the same monetary shock affects segments very differently.
“Divergent growth” regime (fragments of 2023-2024). Economic trajectories diverge across regions (US exceptionalism vs European recession) or sectors (AI/tech vs everything else). Global correlations fragment. Intra-market dispersion surges: the performance spread between the Magnificent Seven (+75% in 2023, Goldman Sachs) and the S&P 500 equal-weight reaches historic levels. This regime creates differentiation opportunities among usually synchronized assets, but also massive concentration risk for indexed portfolios. Often overlooked: why index concentration alters asset-class correlations.
Identifying the prevailing regime determines portfolio construction. In risk-on/risk-off regimes, asset-class diversification works. In inflation regimes, only regime diversification (including inflation-resilient assets: commodities, TIPS, interest-bearing cash) protects. In divergent-growth regimes, geographic and sector diversification regain value. The Allocation Foundations sub-pillar integrates this dynamic framework into portfolio construction models.
Implications for Portfolio Construction
Correlation instability requires thinking in regime scenarios rather than historical averages. Asset-class diversification (equities, bonds, real estate) remains necessary but insufficient; it must be complemented by regime diversification: including assets likely to perform in environments the portfolio does not cover. A 60/40 portfolio is optimized for the 2009-2021 regime: it is structurally vulnerable to inflation and divergent-growth regimes.
Real-time correlation monitoring (60-day rolling S&P 500 vs 10-year Treasury correlation, intra-sector dispersion, equal-weight vs cap-weight performance spread, gold vs TIPS behavior) provides a diagnostic tool for the prevailing regime. Not to predict the future, but to verify that portfolio structure aligns with the current regime, and to detect transitions before they become obvious in aggregated macro data.
The study of the strong dollar and performance hierarchy quantifies the impact of a strong-dollar regime on each asset class. The examination of the inverted yield curve formalizes transmission channels between bond markets and the real economy. The study of dangerous market moments identifies calm-before-the-storm configurations that precede correlation breakdowns. The review of rate hikes and their differentiated impacts documents how the same monetary shock affects segments differently depending on regime.
← Back to pillar page Financial Markets
Last updated — 20 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Financial Innovation, Market Infrastructure and Systemic Risk
Technologies, infrastructures, and new economic models: the structural transformations reshaping capital flows, market architecture, and risk transfer. Financial…
How Financial Markets Form Expectations and Price Risk
Reading framework This page constitutes an analytical subset of the pillar Financial Markets. It provides a structural reading…
Capital Flows and Price Formation in Financial Markets
Net purchases of US corporate equities by sector (Federal Reserve Board, Financial Accounts of the United States, Z.1,…