
Every S&P 500 Drawdown Since 1950: A Catalog of 17 Episodes by Depth, Duration, Recovery, and Macro Regime
Research · Equity Markets · Updated September 2026
A reproducible inventory of every S&P 500 decline of 10% or more between January 1950 and September 2026, measured on monthly averages of daily closes and cross-referenced against four macroeconomic regime indicators: yield curve inversion, real Fed Funds rate, high-yield credit spreads, and recession dates (FRED USREC).
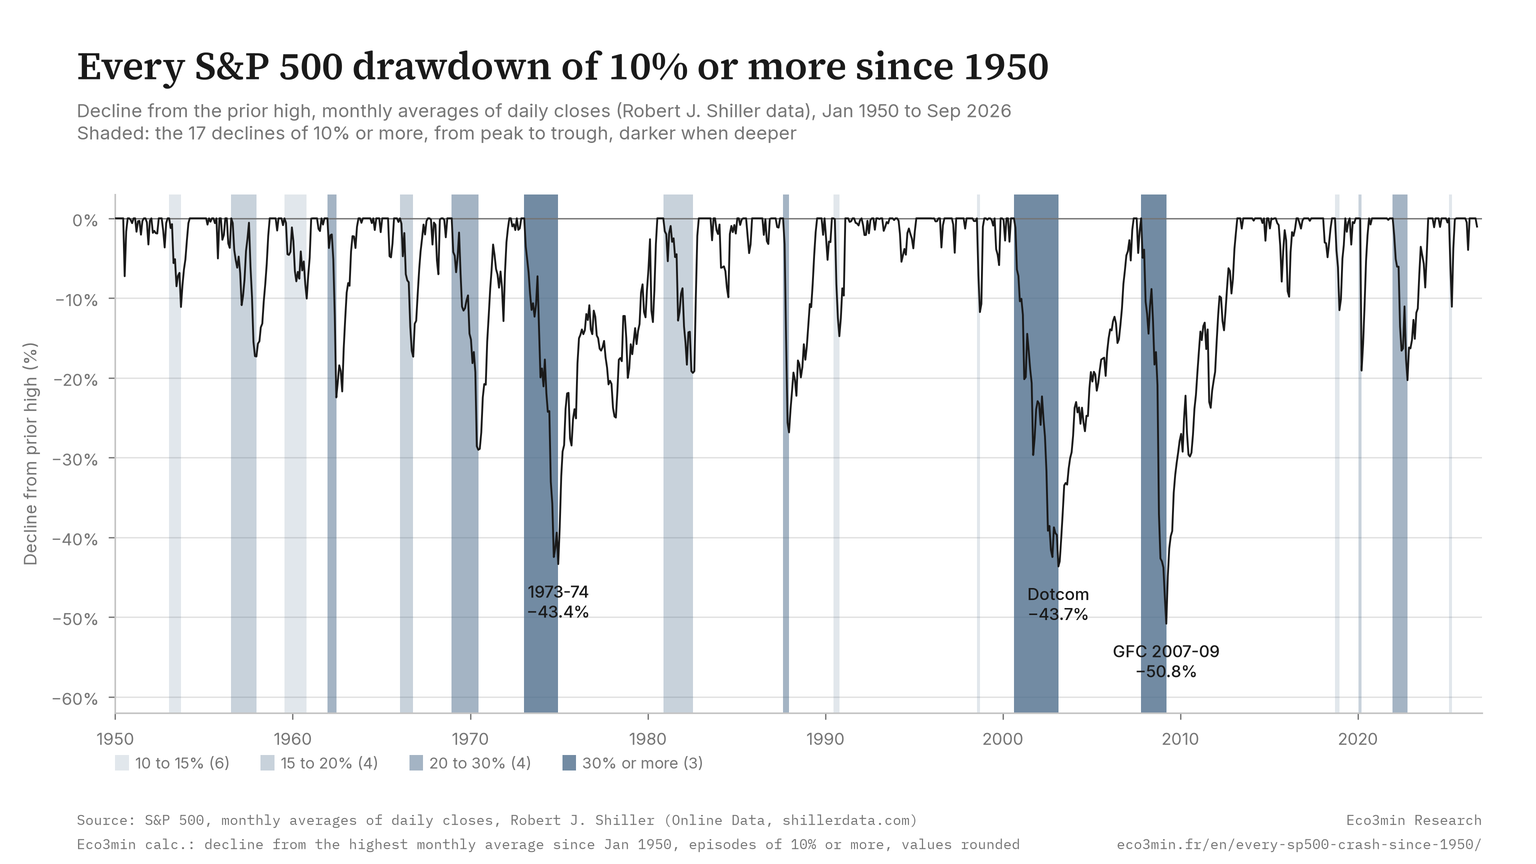
Of the 7 S&P 500 bear markets observed since 1950 on monthly averages, all 7 were preceded, within a 24-month window, by at least one of three classical macro stress signals: a yield curve inversion, a tight real Fed Funds rate, or a sharp high-yield credit spread widening.
TL;DR: Five facts the catalog establishes
- 17 drawdowns of 10% or more in the S&P 500 price index between January 1950 and September 2026, measured on monthly averages of daily closes: roughly one every four and a half years.
- 7 of those were bear markets (decline ≥20%). The median bear market took 39 months from peak to recovery, the median pullback (10–15%) only 7.5 months.
- All 7 bear markets were preceded by at least one of three classical macro stress signals (yield curve inversion, real Fed Funds rate at or above +1.5%, or a high-yield credit spread widening of at least 200 basis points) within the prior 24 months.
- The only drawdown with no signal is the 1956–57 decline (peak July 1956, trough December 1957, −17.3%, short of the bear-market line on monthly averages): no inversion, real Fed Funds below the +1.5% threshold at peak, no observable high-yield credit data, recession (business-cycle peak in August 1957, FRED USREC) arriving 13 months after the equity peak.
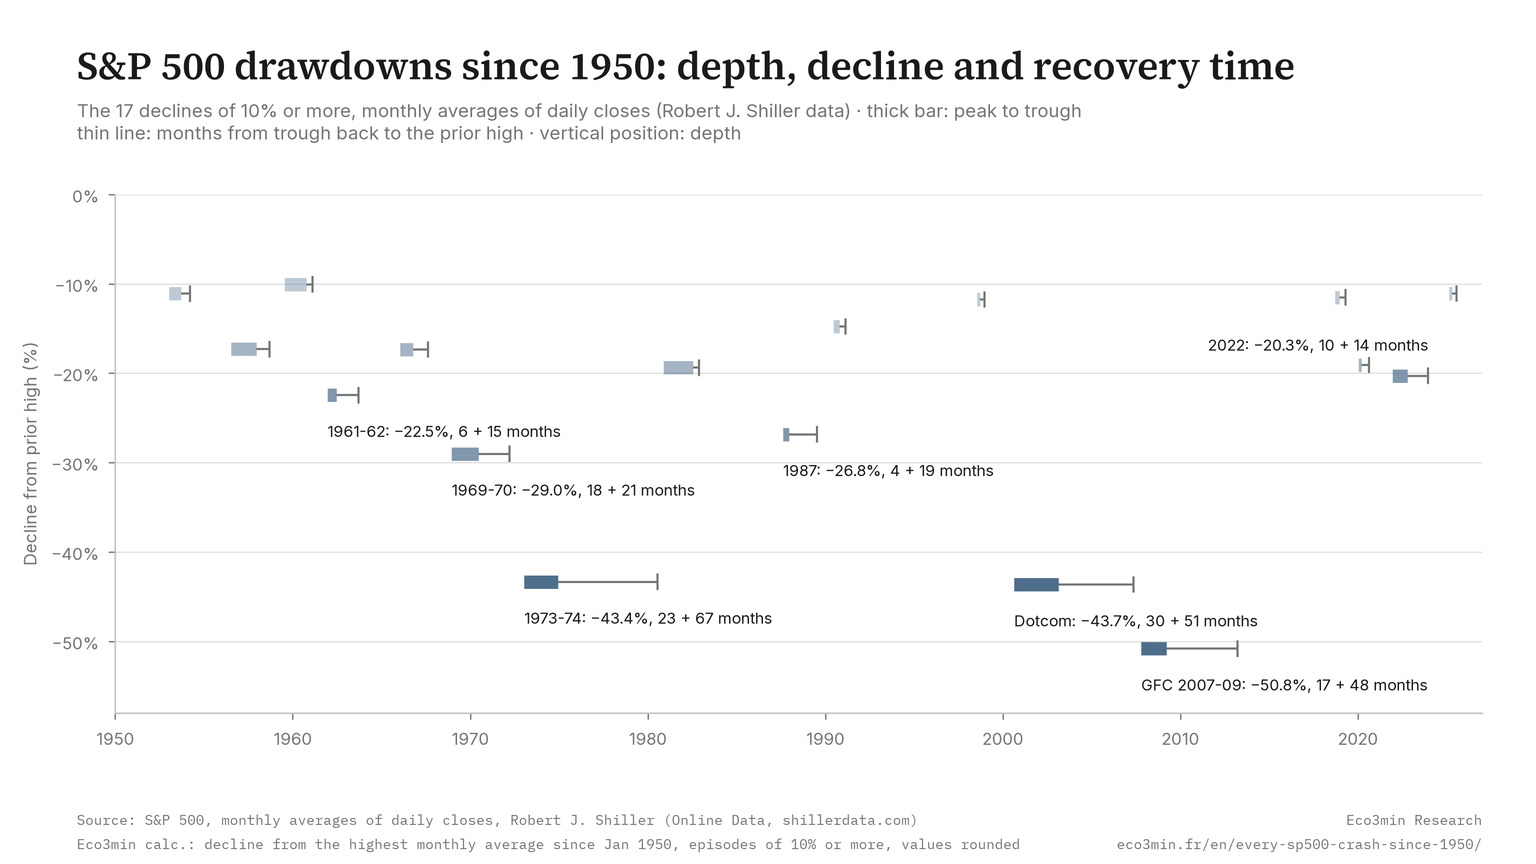
- Recovery time scales with depth. Median peak-to-recovery is 7.5 months for pullbacks (10–15%), 23.5 months for bear markets (20–30%), and 81 months, almost seven years, for severe bear markets ≥30%.
What the catalog shows
Between January 1950 and September 2026, the S&P 500 price index, measured on monthly averages of daily closes, recorded 17 distinct drawdowns of 10% or more from its highest level since January 1950. The deepest was the 50.8% decline from the October 2007 peak to the March 2009 trough. The shortest, measured peak to full recovery, were the LTCM/Russia decline of 1998 (July to December) and the 2025 tariff shock (February to July): five months each. The longest was the 1973–1974 stagflation bear: 7.5 years from the January 1973 peak to the July 1980 reclamation of that level. Related question: Our Q&A on stagflation.
Each episode in the catalog is defined the same way. A drawdown begins in a month whose average sets a new high. It ends in the next month whose average reaches or exceeds that high. If the maximum decline inside that window reached at least 10%, the window is counted as a drawdown episode. The lowest month inside the window is the trough; the recovery month is the first month in which the prior high was reclaimed. This algorithm is reproducible from the underlying monthly price series, whose source is listed in the methodology.
Context box: three caveats this catalog acknowledges from the outset
- All values are nominal monthly averages. The S&P 500 price index used here is the monthly average of daily closes published by Robert J. Shiller; it excludes dividends and is not adjusted for inflation. Averaging smooths short, sharp declines: depths are shallower than on daily closes, and the February–March 2020 crash registers at −19.1%. The 1973–74 bear took 7.5 years to recover in nominal terms; in real terms (price deflated by the CPI), the index did not reclaim its January 1973 level until August 1987. Total-return drawdowns are shallower than price-index drawdowns, by 0.2 to 6.8 percentage points across the 17 episodes (median 1.8), depending on the length of the decline and the dividend yield of the period.
- The three macro signals are not independent. Yield curve inversions, sharp rises in real Fed Funds, and high-yield credit spread blow-outs are all manifestations of the same underlying tightening-and-overextension dynamic. The value of this catalog is documentary, a structured record of which signals preceded which drawdown, not the discovery of three separate leading indicators.
- Signal observability is constrained by data history. The monthly 10-year Treasury yield used for the yield curve begins in April 1953; the Fed Funds rate series in July 1954; the ICE BofA US High Yield index in December 1996. For drawdowns before those start dates, the corresponding signal is marked unobservable rather than treated as absent. One of the 17 episodes, the 1953 pre-recession decline, has no observable signal at all and is flagged accordingly in the catalog table.
With those caveats stated, the rest of this page presents three things: a description of how drawdowns are distributed in depth and duration, a tabulation of which macro signals appeared before each drawdown, and an explicit accounting of the cases where the signals diverged from drawdowns in both directions, bear markets without warning signs, and warning signs without bear markets.
How deep, how long: the shape of every decline
The 17 drawdowns are not uniformly distributed. Six of them, about a third, were pullbacks of 10 to 15%, the kind of decline that resolves in months and barely registers in popular memory. Four were corrections of 15 to 20%. Four were bear markets of 20 to 30%. Three were severe bear markets of 30% or more: the global financial crisis (−50.8%), the dotcom bust (−43.7%), and the 1973–74 stagflation episode (−43.4%). Each of these episodes is situated in the macro regime it belonged to in the financial-crisis timeline.
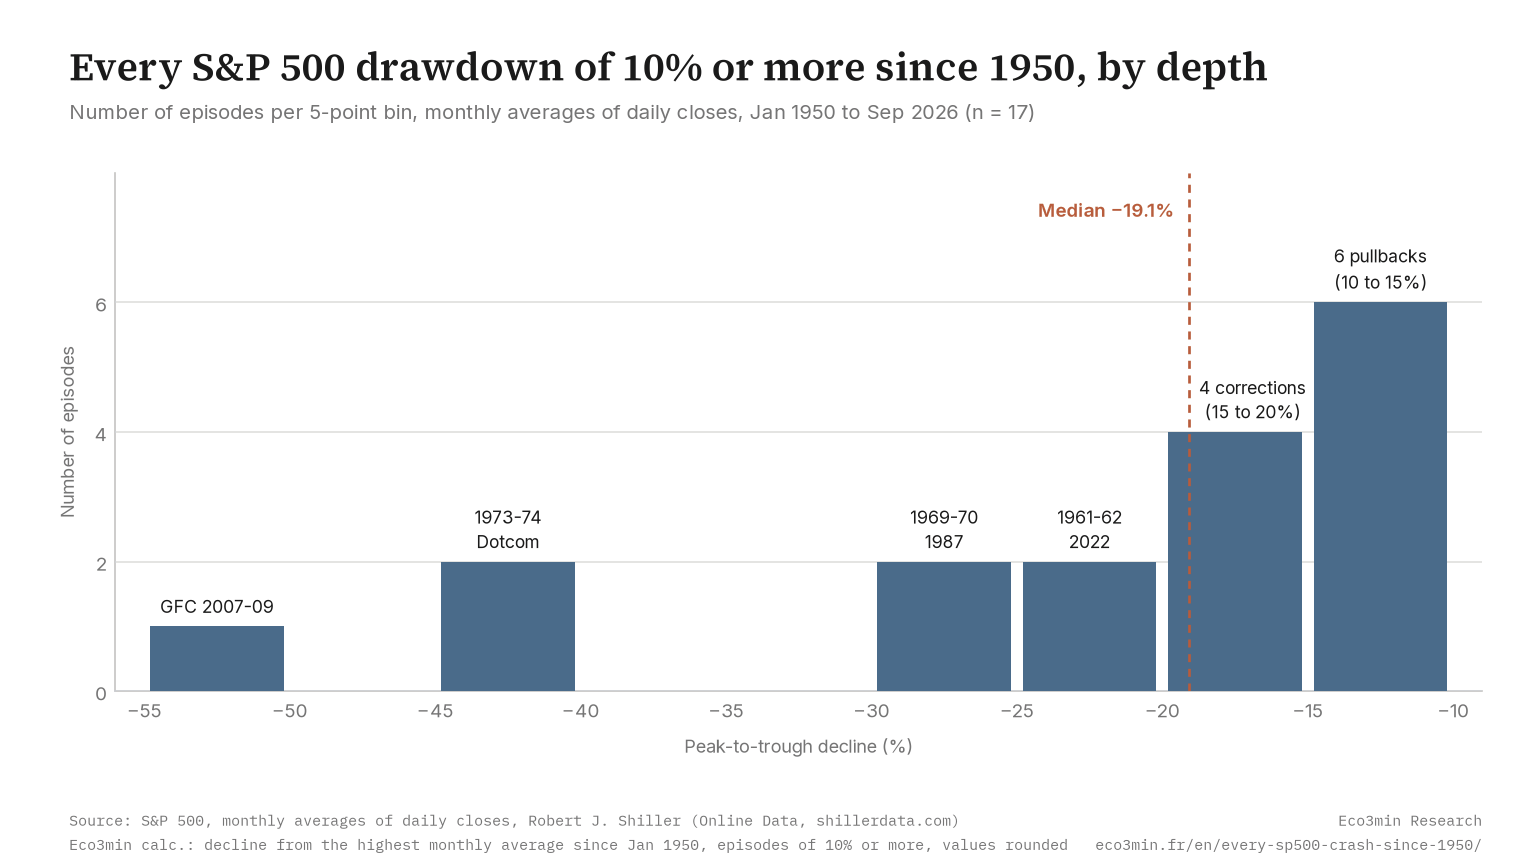
Recovery time tracks depth with remarkable regularity.
| Depth bucket | Episodes | Median peak-to-trough | Median trough-to-recovery | Median peak-to-recovery |
|---|---|---|---|---|
| Pullback (−10% to −15%) | 6 | 3.5 months | 4 months | 7.5 months |
| Correction (−15% to −20%) | 4 | 13 months | 7 months | 21.5 months |
| Bear market (−20% to −30%) | 4 | 8 months | 17 months | 23.5 months |
| Severe bear (≥30%) | 3 | 23 months | 51 months | 81 months |
Source: Eco3min calculations on the S&P 500, monthly averages of daily closes, Robert J. Shiller (Online Data, shillerdata.com). 1950–2026. n = 17 closed episodes.
The asymmetry is the result that matters: a pullback is over in about seven and a half months at the median; a bear market exceeding 30% takes almost seven years to recover fully on a nominal price basis. The correction bucket sits between the two, pulled up by the slow 1956–57 decline (26 months) and the 1980–82 Volcker disinflation decline (24 months); the 1966 Credit Crunch recovered in 19 months and the 2020 COVID-19 decline, which registers at −19.1% on monthly averages, in 7.
The single longest recovery in the dataset is the 1973–74 bear at 90 months. The second longest is the dotcom bust at 81 months. The third is the global financial crisis at 65 months. The clustering at the top is consistent with what total-return studies of the same period report: the three deepest bears are the three slowest recoveries, and the gap between them and everything else is large (the next longest, the 1969–70 bear, took 39 months).
The macro pattern: all 7 bear markets had warning signs
For each drawdown the catalog records four binary indicators, all defined relative to the peak date:
- Yield curve inversion: was either the 10-year minus 3-month or the 10-year minus 2-year spread negative, in monthly averages, in the peak month or in any of the 24 months before it? Convention follows Estrella and Mishkin (1998) and the New York Fed recession probability model.
- Real Fed Funds tight at peak: was the effective Fed Funds rate minus year-on-year CPI at or above +1.5% at the peak month? The 1.5% threshold approximates the post-1954 distribution median; the convention follows Reinhart and Sbrancia (2011) on real-rate regimes.
- High-yield credit spread blow-out: did the ICE BofA US High Yield index option-adjusted spread (FRED series BAMLH0A0HYM2) rise by at least 200 basis points from its trailing 12-month trough by or within six months of the peak? Series begins December 1996; flagged unobservable before that.
- Recession in window: did a recession in the FRED USREC series start within 12 months after the peak, or overlap the drawdown window?
The first three are the “macro stress signals” referenced in the hook. The fourth is included as context: recessions are not market-leading indicators, since they are dated retrospectively by the NBER and the announcement typically arrives many months after the trough of the equity drawdown.
| Signal | Hit rate | Notes |
|---|---|---|
| At least one signal observed | 7 / 7 | The only drawdown ≥10% with no signal, 1956–57 (−17.3%), stays short of the bear-market line on monthly averages. |
| Yield curve inverted in 24m before peak | 4 / 7 | Missing: Kennedy Slide 1961–62, 1973–74 stagflation bear (inversion from June 1973, after the peak), Black Monday 1987. |
| Real Fed Funds ≥ +1.5% at peak | 4 / 7 | Below threshold: 1969–70, GFC, 2022. |
| Recession in window (FRED USREC) | 4 / 7 | Non-recession bears: Kennedy Slide, Black Monday, 2022 bear. |
Source: Eco3min catalog. Signal definitions in methodology section. The high-yield credit signal is not tabulated: its result is given in the methodology.
The 7-of-7 figure is the headline number. Read at face value, every bear market since 1950, measured on monthly averages, was preceded by at least one classical macro stress signal within the prior 24 months. Across all 17 drawdowns ≥10%, 15 of the 16 with at least one observable signal were preceded by at least one, meaning the pattern extends, though less cleanly, to smaller declines as well; the exception is the 1956–57 decline.
This is the result that lets observers say things like “macro signals tend to flash before equity drawdowns.” The catalog confirms that the descriptive statement is true. What it does not establish, and the next section is dedicated to why, is that the signals constitute a predictive edge.
Why this is not a predictive edge
There are four reasons the 7-of-7 figure does not translate into a trading or allocation signal.
First, the three signals are not independent. Yield curve inversions, sharp rises in real Fed Funds, and high-yield credit spread widening are all expressions of the same underlying business cycle dynamic: a Fed tightening cycle in a late-expansion economy where credit risk premiums begin to reprice. Counting them as three separate signals overstates the information content. A more honest summary is that most bear markets in the catalog occurred during or after a Fed tightening cycle that ended badly, which is closer to a near-tautology than a discovery, because the Fed only tightens when it believes the economy is overheating, and overheating cycles end in recessions, and recessions compress earnings.
Second, the unconditional base rate of having a signal in any 24-month window is high. Since 1965, yield curve inversions alone have occurred in roughly half of all rolling 24-month windows (53% of months on the monthly definition used here). Add real-rate spikes and credit blow-outs and the base rate climbs further. A finding of “7 of 7 bear markets had a signal” against a backdrop of “more than half of all 24-month windows had a signal” is consistent with the signals being descriptive of the macro environment rather than predictive of equity returns. This is the single most important qualification in the dataset, and it is the reason this study is framed as a catalog and not as an inference. Descriptive of the macro environment is another way of saying descriptive of the regime: the unit of analysis in the macro-financial regimes overview, from the Great Moderation to the structural break.
Third, signals produce false positives. In monthly averages, the yield curve inverted in late 1966 with no recession, while a 17% decline was already underway. It inverted through most of 1989, and the next decline of 10% or more (mid-1990, −14.8%) stayed a pullback. It inverted in June 1998, a month before the LTCM decline, but the bear market did not begin until the August 2000 peak. The long inversion from July 2022 to November 2024 has so far been followed only by the 2025 pullback (−11.1%). A signal that fires in advance of every bear market in the catalog, but also fires many times in advance of nothing, is a signal with high recall and low precision: useful for narrative, not for portfolio construction. Our chronicle of historical crises gathers these episodes.
Fourth, n is small. Seven bear markets in 76 years is not a sample on which to base statistical claims. The conditional frequency of a macro signal preceding a bear market is 7 of 7, but a 100% point estimate on n=7 carries no informative standard error, and the count itself depends on measurement: on monthly averages the 1956–57 decline, which had no signal, stops at −17.3%, short of the bear-market line. The Estrella and Hardouvelis (1991) framing (that yield curve inversions are associated with subsequent recessions across many countries and periods) is more robust because it draws on a much larger sample. The 7-of-7 figure in this catalog is consistent with that larger literature, but it is the larger literature, not this catalog, that does the inferential work.
The point of stating these qualifications explicitly is not to dismiss the dataset. It is to make the dataset useful for the kind of work where it is genuinely informative: as a reference for “what happened” rather than “what will happen.” A market historian comparing the Volcker disinflation decline to the 2022 tightening bear can read both rows of the catalog side by side. An analyst writing about credit-led equity peaks can use the seven post-1996 episodes, where the credit flag is observable, as a structured reference. A journalist comparing the durations of bear markets can cite the median peak-to-recovery times. None of these uses requires the catalog to be predictive. A related fixed-income angle, how bond prices respond to rate moves, is set out in our breakdown of duration risk.
False negatives and false positives
The catalog contains three categories of edge case that deserve their own accounting.
The one drawdown without any signal: 1956–57
The 1956–57 decline is the only drawdown of 10% or more in the catalog where none of the three signals fired. On monthly averages the S&P 500 peaked in July 1956 and bottomed in December 1957, a decline of 17.3%: a correction, not a bear market, on this measure. At the July 1956 peak, real Fed Funds stood at about 0.8%, below the 1.5% threshold used in the catalog. The yield curve did not invert in the prior 24 months. The high-yield credit spread series did not exist. FRED USREC flags recession months from September 1957, so the business-cycle peak falls in August 1957, 13 months after the equity peak; that recession is captured by the recession column, not by the three forward-looking signals. Related material: our decoding of the record-high question.
Two observations are worth recording. The first is that the classification of this episode depends on the measure: on monthly averages it stops at −17.3%, and a measure on daily closes, which catches intra-month lows, is deeper by construction. The second is that the Fed Funds series itself begins in July 1954, so the 1956 reading is among the earliest observations available, a reminder that pre-1960s episodes operate at the edge of the signal-construction dataset.
Bear markets with thin signal coverage: Kennedy Slide and Black Monday
Two bear markets in the catalog register a signal but only barely.
The Kennedy Slide peaked in December 1961 and bottomed in June 1962 on monthly averages, a 22.5% decline with no recession (FRED USREC) and no yield curve inversion. The single signal that fires is real Fed Funds at about 1.7%, just above the 1.5% threshold. Published in the Federal Reserve’s record of FOMC rate decisions. The episode is conventionally read as a valuation reset in growth stocks combined with the Kennedy administration’s confrontation with US Steel over price hikes; it is the catalog’s clearest case of a bear market that does not fit a tightening-into-recession narrative.
The Black Monday 1987 bear peaked in August 1987 and bottomed in December 1987 on monthly averages, a 26.8% decline spanning the 19 October crash. Real Fed Funds at peak stood at about 2.4%, above the 1.5% threshold, but this was a residual elevation from the Volcker disinflation era rather than the signature of a fresh tightening cycle. No yield curve inversion. No recession (FRED USREC). The 1987 crash is widely attributed in the academic literature to the interaction between portfolio insurance and market microstructure during a period of rising rates, and it is the clearest case of a severe drawdown driven by trading dynamics rather than a macroeconomic regime change.
False positives: inversions without bear markets
The yield curve has inverted multiple times in episodes that did not produce a bear market or that produced a more modest decline.
- 1966: inversion from September 1966 to January 1967, during the Credit Crunch; no recession (FRED USREC); the equity decline, already underway, reached −17.3% on monthly averages, and the macro regime did not deliver the recession that the inversion typically anticipates.
- 1989: inversion in monthly averages through most of 1989; the next decline of 10% or more came in mid-1990 (−14.8%, a pullback on monthly averages), timed more tightly to the August 1990 Gulf War shock and the 1990 recession than to the inversion itself.
- 1998: one month of inversion (June 1998), just before the LTCM/Russia crisis; the resulting decline was −11.8% on monthly averages, not a bear market; the eventual bear market began at the August 2000 peak, after the curve had re-inverted in February 2000 and the Fed had completed a new tightening cycle.
The yield curve also inverted from June to September 2019 ahead of COVID, but the 2020 decline was an exogenous shock, not the recession the 2019 inversion would have signalled in the absence of the pandemic. This is a case where the signal was present and a major drawdown followed, but the causal chain conventionally implied by the signal did not run.
Sensitivity: depth thresholds and signal windows
Two methodological choices drive the headline numbers: the depth threshold used to define a “drawdown,” and the look-back window used to determine whether a signal “preceded” the peak. Both are reported at multiple values below.
| Threshold | Episodes | Median depth | Median peak-to-recovery |
|---|---|---|---|
| ≥10% | 17 | −19.1% | 21 months |
| ≥15% | 11 | −22.5% | 24 months |
| ≥20% | 7 | −29.0% | 39 months |
| ≥30% | 3 | −43.7% | 81 months |
| ≥40% | 3 | −43.7% | 81 months |
Source: Eco3min catalog. Closed episodes only. n decreases with threshold.
The threshold matters most at the −15% to −20% boundary. Of the 17 episodes in the catalog, 6 fall in the narrow band between −10% and −15%, pullbacks that resolve in months and rarely figure in popular discussion of “crashes.” Raising the threshold to −15% leaves 11. Raising it to the conventional bear-market line of −20% leaves 7: four declines of 17 to 19% on monthly averages (1956–57, 1966, 1980–82 and 2020) fall just short of it. Raising it to −30% leaves the three episodes that take a median of 81 months, almost seven years, to recover; no episode falls between −30% and −40%.
The look-back window for the signal indicators is set at 24 months following the Estrella and Mishkin (1998) convention. On monthly averages, the inversion that accompanies the 1973–74 stagflation bear starts in June 1973, five months after the January 1973 equity peak, so that bear does not count as “yield curve preceded” at 12 or 24 months. Tightening the window to 12 months cuts the yield-curve count from 4 of 7 bear markets to 2 (the dotcom bust and the global financial crisis) and the any-signal count from 7 to 6: the 1969–70 bear loses its only signal, an inversion that ended 23 months before its peak. Lengthening the window to 36 months adds the 1973–74 bear through the 1969–70 inversion, for 5 of 7.
The full catalog: 17 episodes
Every S&P 500 drawdown of 10% or more between January 1950 and September 2026, measured on monthly averages of daily closes, in chronological order, with the four macro indicators recorded for each. A dot (•) indicates the signal was present; a dash (–) that it was not; “n/a” that the data series did not yet exist. The study file is not offered for download; the methodology at the foot of this page lists every source.
| # | Episode | Peak | Trough | Recovery | Depth | P→R months | YC inv. | Real rates | Recession |
|---|---|---|---|---|---|---|---|---|---|
| 1 | 1953 pre-recession decline | 1953-01 | 1953-09 | 1954-03 | −11.1% | 14 | n/a | n/a | • |
| 2 | 1956–57 decline (1957 recession) | 1956-07 | 1957-12 | 1958-09 | −17.3% | 26 | – | – | • |
| 3 | 1959–60 recession decline | 1959-07 | 1960-10 | 1961-02 | −10.1% | 19 | – | • | • |
| 4 | Kennedy Slide | 1961-12 | 1962-06 | 1963-09 | −22.5% | 21 | – | • | – |
| 5 | Credit Crunch of 1966 | 1966-01 | 1966-10 | 1967-08 | −17.3% | 19 | – | • | – |
| 6 | 1969–70 recession bear | 1968-12 | 1970-06 | 1972-03 | −29.0% | 39 | • | – | • |
| 7 | Stagflation bear (1973–74) | 1973-01 | 1974-12 | 1980-07 | −43.4% | 90 | – | • | • |
| 8 | Volcker disinflation decline | 1980-11 | 1982-07 | 1982-11 | −19.4% | 24 | • | • | • |
| 9 | Black Monday 1987 | 1987-08 | 1987-12 | 1989-07 | −26.8% | 23 | – | • | – |
| 10 | Gulf War / 1990 recession | 1990-06 | 1990-10 | 1991-02 | −14.8% | 8 | • | • | • |
| 11 | LTCM / Russia crisis | 1998-07 | 1998-09 | 1998-12 | −11.8% | 5 | • | • | – |
| 12 | Dotcom bust | 2000-08 | 2003-02 | 2007-05 | −43.7% | 81 | • | • | • |
| 13 | Global Financial Crisis | 2007-10 | 2009-03 | 2013-03 | −50.8% | 65 | • | – | • |
| 14 | Q4 2018 tightening tantrum | 2018-09 | 2018-12 | 2019-04 | −11.5% | 7 | – | – | – |
| 15 | COVID-19 crash | 2020-01 | 2020-03 | 2020-08 | −19.1% | 7 | • | – | • |
| 16 | 2022 tightening bear | 2021-12 | 2022-10 | 2023-12 | −20.3% | 24 | • | – | – |
| 17 | 2025 tariff shock | 2025-02 | 2025-04 | 2025-07 | −11.1% | 5 | • | • | – |
Source: Eco3min. Price data: S&P 500, monthly averages of daily closes, Robert J. Shiller (Online Data, shillerdata.com). Macro indicators: Federal Reserve Board H.15 via FRED (GS10, TB3MS, GS2, FEDFUNDS), BLS CPI via FRED (CPIAUCSL), recession dates via FRED (USREC). The high-yield credit signal is described in the methodology and not shown in the catalog.
Methodology and data
Drawdown identification algorithm
Let P(t) be the monthly average of the daily closing levels of the S&P 500 in month t, as published by Robert J. Shiller (Online Data). Define the running peak M(t) = max(P(s)) for January 1950 ≤ s ≤ t. The drawdown at t is DD(t) = P(t)/M(t) − 1. An “episode” is the time interval between two consecutive new highs, i.e. between two distinct months in which M(t) increases. An episode is recorded as a drawdown if min(DD(t)) inside the interval is at most −10%. The peak month is the start of the episode, the trough month is the argmin of DD(t) inside the episode, and the recovery month is the end of the episode.
The algorithm produces 17 episodes between January 1950 and September 2026. It uses monthly averages, not daily closes or intraday levels, so peaks, troughs and recoveries are months and durations are counted in months. Episodes that began but have not yet reached a new high by the end of the sample are excluded as open episodes. As of the data cutoff (September 2026), all 17 episodes in the catalog are closed.
Macro signal definitions
Yield curve. The signal fires if either the 10-year Treasury yield minus the 3-month Treasury bill rate (FRED: GS10 minus TB3MS, from April 1953) or the 10-year minus the 2-year yield (GS10 minus GS2, from June 1976) was negative in monthly average in the peak month or in any of the 24 months before it. Both are Federal Reserve Board H.15 series; the monthly construction keeps the signal at the frequency of the price series, where daily spreads (T10Y3M, T10Y2Y) would catch brief inversions that monthly averages smooth out. Episodes whose window starts before April 1953 are flagged unobservable. Reference data: our 2s10s inversion dataset.
Real Fed Funds. Computed as effective Fed Funds rate (FRED: FEDFUNDS, monthly average) minus year-on-year headline CPI inflation (CPIAUCSL). Threshold +1.5% is approximately the median of the post-1954 distribution and aligns with the convention used by Reinhart and Sbrancia (2011) for distinguishing positive from negative real-rate regimes.
High-yield credit. The signal fires if the ICE BofA US High Yield index option-adjusted spread (FRED: BAMLH0A0HYM2) rose by at least 200 basis points from its trailing 12-month minimum by or within six months after the equity peak. The series is daily from 31 December 1996. Pre-1997 drawdowns are flagged unobservable, not absent. Since 1997, the signal fired before each of the 3 bear markets it can observe.
Recession in window. A recession is “in the window” if its start month in the FRED USREC series fell within 12 months after the equity peak, or if its peak-to-trough span overlapped the equity drawdown window. Recession dates are taken from the FRED USREC series (Federal Reserve Bank of St. Louis) and are not back-revised. Under that same dating, the last U.S. recession is the short one of spring 2020, the latest in a sequence that opens in 1948.
Limitations
- Nominal price index, monthly averages. Drawdowns and recoveries are computed on the S&P 500 price index as monthly averages of daily closes, excluding dividends and not adjusted for inflation. Averaging smooths short, sharp declines, so depths are shallower than on daily closes and some brief declines of 10% or more in daily closes do not appear. Total-return drawdowns are 0.2 to 6.8 percentage points shallower across the 17 episodes; real-terms recovery dates can be many years later than nominal-terms dates, especially in the 1973–74 episode.
- Pre-1957 S&P 500. The “S&P 500” as a 500-constituent index dates from March 1957. Before that date, Shiller’s series follows S&P’s predecessor composite index (90 stocks), chained into a single continuous series. This is the standard public convention but does not match what investors saw in real time before 1957.
- Signal observability. Of the 17 drawdowns, the 1953 episode has no observable signal (no monthly 10-year yield before April 1953, no Fed Funds before July 1954). The ten episodes before 1997 are unobservable on high-yield credit. The catalog flags every unobservable cell rather than imputing.
- Signals are correlated. The three signals are not independent indicators of distinct phenomena. They are co-symptoms of a Fed-led tightening cycle in a late-expansion economy. Counting “any signal” is therefore not the same as counting three orthogonal warnings.
- Sample size. Seven bear markets is a small n. No statistical significance claim is made anywhere on this page. The catalog is descriptive, not inferential.
Data download
The study file is not offered for download: it contains data whose owner restricts redistribution (a flag derived from the ICE BofA US High Yield spread, FRED BAMLH0A0HYM2, pre-approval required). The methodology lists every source. Required citation: “Eco3min, ‘Every S&P 500 Drawdown Since 1950’, eco3min.fr, 2026.”
Frequently asked questions
How many bear markets has the S&P 500 had since 1950?
Seven, where a bear market is defined as a peak-to-trough decline of at least 20% in monthly averages of the closing price index. The most recent is the 2022 tightening bear, which peaked in December 2021 and bottomed in October 2022, a decline of 20.3%, with nominal recovery in December 2023.
What was the deepest S&P 500 drawdown since 1950?
The global financial crisis of 2007 to 2009, at −50.8% on monthly averages from peak (October 2007) to trough (March 2009). The dotcom bust was the second deepest at −43.7% (peak August 2000, trough February 2003); the 1973–74 stagflation bear the third at −43.4%. Measures on daily closes are deeper by construction, since they catch intra-month lows.
How long does it take to recover from a bear market?
The median peak-to-recovery time for bear markets between 20% and 30% is 23.5 months, roughly two years. For severe bear markets of 30% or more, the median is 81 months, almost seven years. The single longest recovery in the catalog is the 1973–74 bear at 90 months (7.5 years).
Does a yield curve inversion always precede a bear market?
No. Of the 7 bear markets in the catalog, the yield curve inverted in the peak month or the 24 months before it in 4 of them. The three exceptions are the Kennedy Slide of 1961–62, the 1973–74 stagflation bear (inversion from June 1973, after the peak) and the 1987 Black Monday bear. Conversely, the yield curve has inverted in several episodes that did not produce a bear market (notably in 1966, 1989, and briefly in 1998) so the relationship is asymmetric in both directions.
Is this a predictive model?
No. This is a descriptive catalog, not a forecasting model. The three macro signals are not independent and produce both false negatives and false positives. The catalog documents which signals were present before each drawdown; it makes no claim about how to use those signals to anticipate future drawdowns. For predictive work, the New York Fed’s yield-curve recession probability model is the conventional reference.
Why start in 1950 rather than 1928 or 1900?
1950 is the conventional starting point for post-war US equity research (Damodaran, Shiller). Earlier samples include the 1929–32 crash, which is structurally distinct: no contemporaneous Federal Reserve Funds rate, no continuous T-bill regime, the gold standard still binding, and an entirely different financial-market plumbing. Including pre-1950 episodes in the same table without those caveats would over-state comparability.
Why does the catalog use nominal prices rather than total return or real terms?
The price index is the most widely cited benchmark in public references to bear markets and drawdowns. This catalog measures it on monthly averages of daily closes (Robert J. Shiller), so its depths are shallower than the daily-close figures usually reported by news outlets and brokers. Total-return drawdowns are 0.2 to 6.8 percentage points shallower (median 1.8); real-terms recovery dates can be many years later, particularly for the 1973–74 episode (real-terms recovery in August 1987 versus nominal in July 1980). Both adjustments are noted in the limitations section.
Where can I download the data?
The file is not offered for download (a flag derived from an ICE BofA spread series, FRED pre-approval required); the methodology lists every source, so the series can be rebuilt from them. Eco3min text and analysis: CC BY 4.0, with attribution. Required citation: “Eco3min, ‘Every S&P 500 Drawdown Since 1950’, eco3min.fr, 2026.”
Cite this study
Eco3min (2026). Every S&P 500 Drawdown Since 1950: A Catalog of 17 Episodes by Depth, Duration, Recovery, and Macro Regime. Eco3min Research. eco3min.fr/en/every-sp500-crash-since-1950
Eco3min text and analysis: CC BY 4.0. Data, files and charts remain subject to their producer’s terms, stated on each page; Eco3min grants no licence over third-party data.
Last updated — 3 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.