
Inflation and Exchange Rates: The Transmission Mechanism
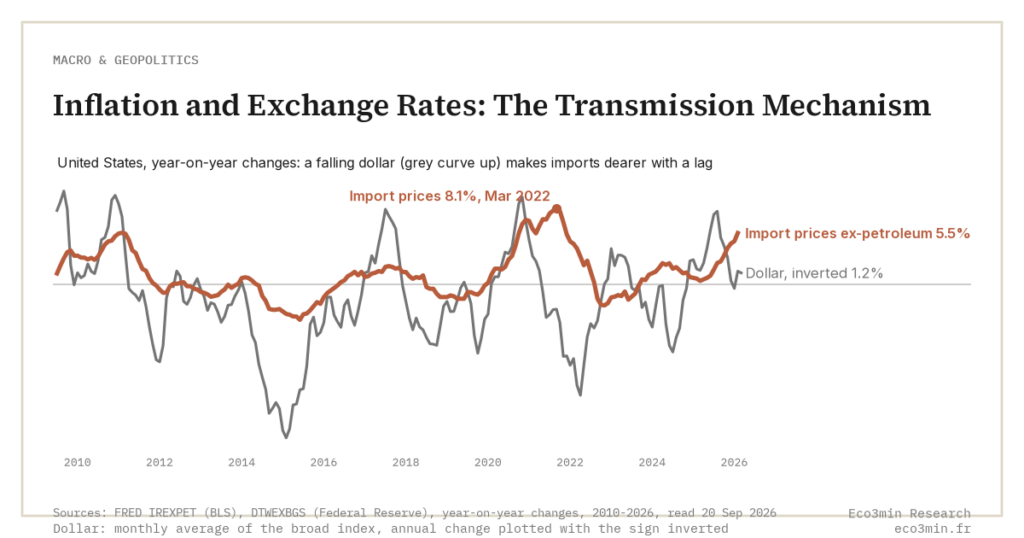
Inflation and the exchange rate move together, but the causal arrow runs in both directions, on different timescales, and through mechanisms that have shifted materially since the 1990s.
A depreciating currency mechanically raises the price of imports and feeds domestic inflation through input costs. A higher domestic inflation rate, sustained, mechanically erodes the currency’s external value, though the timing of each leg is anything but symmetric.
The pass-through literature has documented the relationship for forty years, but the parameters have changed. Imported intermediate inputs, dollar invoicing of global trade, and central-bank credibility have all reshaped how a currency move translates into the CPI, and how an inflation surprise translates back into the foreign-exchange market.
The two-way mechanism
The exchange rate appears in two distinct equations of the inflation system. On the cost side, depreciation raises the local-currency price of imported goods and intermediate inputs: a direct mechanical channel that shows up first in producer prices and then in consumer prices, with a lag typically measured in two to six quarters. On the demand side, a sustained inflation differential between two economies erodes the relative purchasing power of the higher-inflation currency; in the long run, the nominal exchange rate adjusts to restore relative price levels: the purchasing power parity hypothesis.
Neither leg operates cleanly. PPP fails on horizons shorter than five to ten years; pass-through coefficients vary by country, sector, and currency regime; and the relationship breaks down precisely in the periods that matter most, sharp surprise inflation episodes, because central banks intervene through interest rate policy and because firms strategically delay price adjustments. The two-way mechanism is real but operates with substantial slippage, and identifying the dominant direction in any given window requires careful empirical work.
The pass-through channel: from currency to CPI
Pinelopi Goldberg and Michael Knetter’s 1997 review article in the Journal of Economic Literature formalised the empirical literature on exchange-rate pass-through: the share of a currency depreciation transmitted to import prices, producer prices and consumer prices over different horizons. Burstein, Eichenbaum and Rebelo (2003) extended the framework by emphasising the role of imported intermediate inputs and distribution margins, showing why short-run pass-through can be much smaller than long-run pass-through. Cross-country estimates typically find pass-through coefficients of 50-90% to import prices, 20-50% to producer prices, and 5-20% to headline CPI, measured at one to two-year horizons. More context: the transmission of copper prices into measured inflation.
The empirical pattern that has emerged since 2000 is striking. Pass-through to headline CPI in advanced economies has declined materially compared to the 1980s, typically estimated at 5-15% in recent decades versus 25-40% in earlier ones. Several mechanisms drive the decline: greater central-bank credibility anchoring inflation expectations, increased dollar invoicing of global trade (which insulates domestic CPIs from local currency moves for non-dollar economies), and the integration of imported intermediates with substantial domestic value-added margins.
The 2022 European episode provided a recent test. The euro depreciated approximately 8% against the dollar between January and September 2022, while imported energy prices surged. ECB analysis published in 2023 estimated that the euro depreciation contributed roughly 0.3-0.5 percentage points to euro area inflation in 2022: non-trivial, but a small fraction of the total inflation surge driven primarily by global energy and food prices. The pass-through coefficient implied by the episode was at the lower end of the historical range, consistent with the broader decline. A broader view: weak euro, strong euro and imported inflation.
The reverse channel: from inflation to currency
The reverse leg, inflation differentials driving exchange rate moves, is the older and weaker empirical relationship. PPP regressions show convergence on horizons of five to ten years for tradable goods; deviations from PPP can persist for several years between economies with different inflation regimes. The chain of effects is traced in the macro-financial reading of inflation regimes. The theoretical foundation is sound: a currency cannot indefinitely buy fewer real goods than another currency without nominal depreciation. The empirical implementation is messier, because nominal exchange rates are dominated by capital flows and policy rate differentials in the short run.
The Argentine, Turkish and Venezuelan episodes of recent decades illustrate the long-run mechanism in extreme form. Sustained domestic inflation rates of 30-100% per year against a 2-5% U.S. inflation rate have produced cumulative currency depreciations of 90-99% over five to ten year windows. The relationship is mechanical and inevitable in this regime; it simply does not show up in advanced-economy data because no advanced economy sustains a multi-year inflation differential of that magnitude against its trading partners. Venezuela pushed that differential to its breaking point and entered the historical ledger of 50%-monthly crossings in November 2016.
For advanced-economy currency pairs, the inflation differential is typically too small to dominate over horizons shorter than a decade. The 2022-2024 U.S. inflation surge, despite running 2-5 percentage points above euro area inflation in early 2022, did not produce dollar depreciation: quite the opposite, because the Fed’s rate response was sharper and faster than the ECB’s. The capital-flow response to the rate differential dominated the PPP signal, as the standard policy transmission mechanism typically does in the short run.
The dollar invoicing complication
A structural feature of modern global trade complicates the pass-through analysis. More than half of global goods trade is invoiced in U.S. dollars (Gita Gopinath’s body of work, including the 2020 IMF DPN on dominant currency pricing). For most non-dollar economies, this means import prices respond more to the dollar exchange rate than to bilateral trade-partner exchange rates. A euro depreciation against the dollar raises European import prices broadly; a euro depreciation against the yen has minimal direct impact on European CPI even for European-Japanese trade flows. The figures are laid out in our review of common mistakes about the dollar and currencies.
The implication is that the relevant exchange rate for inflation transmission is, increasingly, the dollar, for nearly every country in the world that is not the United States. Dollar-denominated commodity prices, dollar-invoiced manufacturing inputs, and dollar-funded supply chains all transmit dollar moves to global CPIs. The 2022 dollar appreciation of approximately 14% on a broad trade-weighted basis (DXY/Federal Reserve broad index) produced inflationary pressures across most of the rest of the world, even for countries whose bilateral trade with the U.S. is modest.
The 2021-2024 episode in context
The 2021-2024 inflation regime displayed both legs of the mechanism, but with very different intensities. Pass-through from local currency to CPI operated at the lower end of historical ranges in advanced economies, consistent with the post-2000 decline. The dollar invoicing channel transmitted U.S. monetary tightening into inflationary pressure across emerging markets: the textbook strong-dollar inflation transmission documented in the analysis of strong dollar regimes and their global market impact. The reverse leg, inflation differentials driving currency moves, was overwhelmed by policy-rate-differential dynamics. Parity, reached in 2022, is the mark that episode left on the euro’s exchange rate against the dollar since 1999.
The episode reinforced a structural point. In a world where the Fed sets the global rate and the dollar invoices the bulk of trade, the exchange-rate channel of inflation transmission has become more concentrated on a single currency pair (anything-versus-USD) and less responsive to the bilateral trade structure. The implication for non-dollar economies is that inflation imported through the exchange rate is increasingly a function of U.S. monetary policy decisions: a structural exposure that cannot be hedged at the policy level by anything other than reduced trade dependence on dollar-priced inputs.
The external-price channel and the euro area’s exposure
Currency pass-through is only one of the two routes by which inflation is imported. The second is the external-price channel: when imported commodities or intermediates rise in their currency of denomination, typically the dollar for energy and most metals, the cost reaches importers whatever the exchange rate does. The two routes can add up or partly offset each other.
In 2022 the euro area met the two routes in unfavourable correlation. The exposure was structural: imports cover roughly 60% of the euro area’s total energy consumption, and covered more than 80% for natural gas before the 2022 disruption (Eurostat, 2022 energy statistics). The ECB’s Economic Bulletin estimated that energy alone added about 4 percentage points to the HICP at its peak in October 2022, against a counterfactual of stable energy prices. Euro area HICP inflation peaked at 10.6% that month (Eurostat), against a U.S. CPI peak of 9.1% in June 2022 (BLS). Food came later, with HICP food inflation peaking at 17.5% in March 2023 (Eurostat).
The U.S. position is the mirror image. Dollar strength in periods of global stress lowers the local-currency cost of U.S. imports and partly offsets other price pressures, and the mechanism reverses when the dollar weakens. Exposure to imported inflation rests on three structural variables. The first is openness, the import share of GDP. The second is import composition: dependence on a few essential imports, energy and food among them, raises transmission. The third is the invoicing currency.
The two routes also call for different policy readings. The exchange-rate channel responds to interest-rate differentials over months, while the external-price channel barely responds to domestic monetary policy at all. Tightening into an imported shock mainly compresses domestic demand without touching its source. The classic response tolerates the first-round effect while working to prevent second-round wage-price transmission. In the euro area the episode closed as energy prices normalised: by mid-2024 natural gas had fallen back sharply and HICP inflation had returned close to the 2% target.
When the relationship breaks down
Three configurations neutralise or invert the standard pass-through and PPP relationships. First, dollarisation or currency board regimes peg the nominal exchange rate, transferring the entire adjustment burden to domestic prices and wages: Hong Kong’s experience under its USD peg illustrates the resulting volatility in domestic inflation. Second, indexed wage and price-setting regimes (Argentina, Brazil historically) accelerate domestic inflation pass-through to the point where the nominal exchange rate must move continuously. Third, capital controls can suppress the short-run capital-flow response to interest differentials and let the PPP/inflation-differential channel dominate, as in China’s historical experience with the renminbi.
Outside these special cases, the modern advanced-economy default is asymmetric: the exchange rate transmits to inflation weakly and slowly; inflation transmits to the exchange rate even more weakly and on horizons longer than the policy or business cycle. The capital-flow and rate-differential channel dominates in real time, with PPP operating as a slow-moving anchor that becomes visible only on multi-decade horizons. PPP’s best-known test was devised by The Economist around McDonald’s flagship burger to judge whether currencies are fairly valued; divided by local net pay instead, the burger’s price yields the 2026 Big Mac index read in minutes of work across 16 OECD economies.
“A weak currency causes high inflation.” This is partially true but materially overstated for advanced economies. Pass-through coefficients to headline CPI in modern advanced economies are typically 5-15%, meaning a 10% currency depreciation adds, ceteris paribus, perhaps 0.5-1.5 percentage points to CPI over one to two years. The 1970s pattern of currency moves driving large inflation surprises has been substantially attenuated by improved central-bank credibility, dollar invoicing, and the integration of imported intermediates with domestic value-added margins.
The exchange rate is no longer the dominant inflation channel for advanced economies: the dollar is, even for countries that trade little with the United States. The full picture is drawn in our mapping of price regimes.
What the structural shift implies for the next inflation episode
The dominant policy consensus holds that the post-2022 monetary regime (higher real rates, more vigilant inflation targeting, restored central-bank credibility) has further reduced the exchange-rate pass-through to CPI in advanced economies. This is consistent with the trend of the past two decades and is partly self-reinforcing: when central banks respond credibly to currency-driven price pressures, firms and wage-setters discount the persistence of the shock and the pass-through coefficient falls.
The structural exposure to dollar-denominated inputs and dollar-priced commodities has not changed. Any next inflation episode that originates from dollar appreciation or U.S. monetary tightening will continue to transmit globally through the trade-invoicing channel rather than the bilateral exchange-rate channel: a feature, not a bug, of the dominant-currency architecture documented in the Gopinath literature. The implication is that the relevant exchange rate to monitor for inflation pass-through, in nearly every non-US economy, is increasingly the dollar against the local currency, not the trade-weighted basket.
- Inflation and exchange rates move together through two channels: pass-through from currency depreciation to import-driven CPI (Goldberg-Knetter framework), and PPP convergence over five-to-ten-year horizons driven by inflation differentials.
- Pass-through to headline CPI in modern advanced economies is typically 5-15%, substantially below the 25-40% of the 1980s, reflecting central-bank credibility, dollar invoicing, and domestic value-added margins on imported intermediates.
- Dollar invoicing of more than half of global trade (Gopinath body of work) has concentrated the exchange-rate inflation channel on a single currency pair (anything-vs-USD) for non-dollar economies.
- The 2022 episode confirmed both: euro depreciation contributed 0.3-0.5pp to euro area inflation (low pass-through); broad dollar appreciation transmitted inflationary pressure across emerging markets despite modest direct U.S. trade exposure.
The exchange-rate channel sits inside the wider system mapped in the complete guide to inflation mechanics, measurement and effects. It connects directly to the cost-push leg of the inflation diagnosis on the import-cost side, to the debt-erosion mechanism for foreign-currency-denominated debt, and to the corporate margin response that determines how much pass-through reaches consumer prices. For the dataset on global dollar dynamics, see the U.S. trade-weighted dollar index, the breakeven inflation framework for market-implied inflation expectations, and the real interest rate framework that anchors capital-flow responses to inflation surprises. The institutional context sits within the sub-pillar on the U.S. dollar in the systemic global monetary architecture.
Last updated — 3 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →The 1970s Stagflation: The Founding Trauma of Central Banks
From 6.2% inflation in 1973 to 13.5% in 1980, while unemployment climbed simultaneously to 9.0%: the 1970s United…
Gold and Inflation: Myth or Reality of the Safe Haven
Gold is not an inflation hedge: at least not in the way the marketing claims. The empirical record…
The Great Moderation (1990-2007): Why Inflation Disappeared
From the early 1990s to 2007, US output volatility fell by approximately 50%, inflation volatility by 70%, and…