
Cost-Push vs Demand-Pull Inflation: The Two Foundational Logics
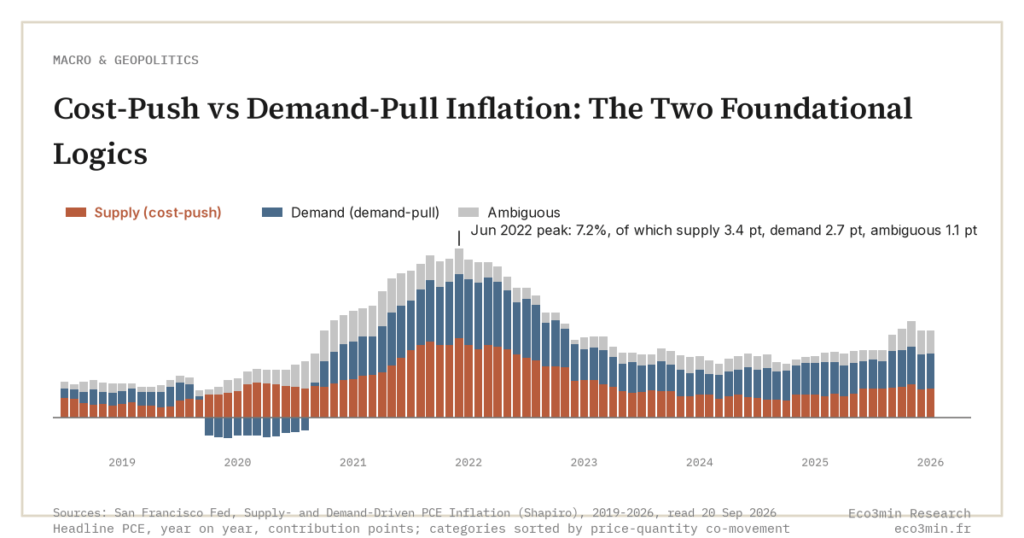
Same headline number, opposite causes: cost-push and demand-pull inflation share a price index but obey different equations. Confusing the two is how central banks lose a decade of credibility.
U.S. CPI peaked at 9.1% in June 2022, its highest reading since November 1981 (BLS). Yet later decompositions found that supply-side forces, not excess demand, explained the larger share of that spike. The diagnostic mistake explains why the policy response remained so contested.
Demand-pull inflation begins when spending outgrows what the economy can produce, cost-push inflation when production costs rise while demand holds steady.
- Demand-pull shifts aggregate demand outward: prices and real output rise together and unemployment falls, as after the roughly $5 trillion of U.S. federal transfers of 2020-2021 (CBO).
- Cost-push shifts aggregate supply inward: prices rise while output falls, the stagflation signature of the 1973 oil shock, when U.S. CPI went from 3.4% in 1972 to 11.0% in 1974 (BLS).
- The 2021-2024 surge mixed both. Eurozone HICP, peaking at 10.6% in October 2022 (Eurostat), was mostly imported energy costs, while the U.S. episode carried a larger demand share.
The two logics behind the same index
Every inflation episode is, mechanically, a story of either too much money chasing too few goods, or too few goods being chased by stable money. That binary framing (too much money, or too few goods) is exactly what the map from inflation type to the cover that holds turns operational. Both push the same index up. Both demand radically different responses. The standard framework, taught since Keynes’ General Theory (1936) and formalised by Friedman in the 1960s, separates two paths to a higher price level: an aggregate demand shift outward (demand-pull), or an aggregate supply shift inward (cost-push, also called supply-shock inflation). Related deep-dive: Commodities: Inflation Hedge or Amplifier?.
Demand-pull: when spending outruns capacity
Demand-pull inflation arises when nominal aggregate demand grows faster than the productive capacity of the economy. In the textbook formulation, it is the situation Keynes described as an inflationary gap: real output is at or above potential, unemployment sits below its non-accelerating rate, and additional spending, public or private, translates almost entirely into prices rather than quantities. The U.S. post-pandemic stimulus is the canonical recent illustration: between March 2020 and March 2021, federal transfers totalling roughly $5 trillion (CBO, 2022) coincided with supply still partially constrained, producing an output gap that turned positive by mid-2021 (CBO Real Potential GDP series). Adjacent reading: What Is Inflation? A Rigorous Definition and Why It Matters.
Cost-push: when supply contracts behind stable money
Cost-push inflation works in reverse. The price level rises not because spending accelerates, but because the cost structure of producing the existing basket shifts upward — through energy prices, intermediate inputs, wages, or trade frictions. The 1973 oil shock is the historical reference: the OPEC embargo of October 1973 quadrupled crude prices in roughly six months, and U.S. CPI accelerated from 3.4% in 1972 to 11.0% in 1974 (BLS) without any prior demand boom. The mechanism is a leftward shift of aggregate supply, which raises prices and reduces output simultaneously — the empirical signature of stagflation. Related reading: Inflation and Demographics: The Invisible Pressure on Pensions.
Demand-pull and cost-push inflation compared
The quickest way to tell the two apart is to look at what happens to output and jobs while prices climb. Prices climbing in a booming economy point to demand. In a stalling one, they point to costs. Output settles it.
| Demand-pull inflation | Cost-push inflation | |
|---|---|---|
| Origin | Total spending (households, firms, government, exports) grows faster than productive capacity | The cost of producing the same basket rises: energy, raw materials, wages, trade frictions |
| Curve that shifts | Aggregate demand, to the right | Aggregate supply, to the left |
| Price level | Rises | Rises |
| Real output | Rises, above potential | Falls |
| Unemployment | Falls below its non-accelerating rate | Rises (stagflation) |
| Typical triggers | Fiscal stimulus, credit expansion, loose monetary policy, an export boom | Oil and gas shocks, supply-chain bottlenecks, a sharp currency depreciation, bad harvests |
| Historical reference | U.S. 2021-2022: $1.9 trillion American Rescue Plan, vacancy-to-unemployment ratio above 1.9 throughout 2022 | 1973-1974 oil embargo, and the eurozone in 2022 after the cut in Russian gas supply |
| Textbook central bank response | Tightening compresses spending and closes the output gap | Central banks have generally looked through first-round effects and tightened when wages and expectations started to follow |
How economists actually decompose an inflation episode
The textbook distinction is conceptually clean but empirically tangled, because most real-world episodes blend both. Eco3min lays this out in the inflation regime framework. The methodological response, refined since the 1990s, is statistical decomposition: separate the share of CPI growth attributable to supply shocks from the share attributable to demand strength using either Phillips-curve residuals, structural VAR identification, or Beveridge-curve mapping. The reference work for the 2021-2024 episode is Bernanke and Blanchard (NBER Working Paper 31417, 2023), which decomposed 11-country inflation across four channels: energy, food, supply-chain bottlenecks, and labour-market tightness. Their headline finding for the United States: supply-side drivers (energy + bottlenecks) explained roughly 60% of the 2021-2022 inflation surge, while demand pressure via labour-market tightness contributed approximately 40%, a ratio that flipped progressively as 2023 unfolded.
The San Francisco Fed runs a parallel monthly decomposition (the framework developed by Adam Shapiro) splitting PCE inflation into supply-driven, demand-driven, and ambiguous components. Our analysis of how inflation arrives in successive waves through history shows the supply share peaked above 50% in mid-2022 before fading toward neutrality by late 2023, confirming the time-varying mix. The sibling topic is taken up in the article on Inflation and the Value vs Growth Rotation: What the Literature Documents.
The 2021-2024 case: a diagnostic battlefield
The recent inflation episode became a textbook case of diagnostic ambiguity. In one camp, economists including Larry Summers and Olivier Blanchard warned as early as February 2021 that the American Rescue Plan ($1.9 trillion, signed March 2021) would generate excess demand large enough to push inflation well above the Fed’s 2% target. In the other camp, central bankers, and notably ECB officials, initially characterised the price surge as “transitory,” reflecting bottlenecks in shipping, semiconductors, and energy that would resolve as supply normalised.
By 2023, the data settled into a more nuanced picture. Eurozone HICP, which peaked at 10.6% in October 2022 (Eurostat), was overwhelmingly cost-push: the European Central Bank’s 2023 Bulletin attributed the bulk of the surge to imported energy after Russia’s invasion of Ukraine compressed natural gas supply. U.S. PCE inflation, which peaked at 7.2% in June 2022 (BEA), carried a larger demand component, consistent with a tighter labour market (the vacancy-to-unemployment ratio held above 1.9 throughout 2022, a postwar record) and a more expansionary fiscal stance. The transatlantic divergence (same direction, different mix) is itself evidence that the two logics matter empirically. The cost-push side is illustrated by the copper channel running from PPI to CPI. A complementary lens on this period appears in our work on the difference between structural and cyclical inflation drivers, which maps the cost-push/demand-pull split onto a longer time horizon.
Why the diagnosis dictates the response
The policy stake is large. A pure demand-pull shock has a textbook response: tighter monetary policy compresses spending, the output gap closes, inflation cools. The cost is a contraction in real activity, but the trade-off is well understood since Phillips first estimated his curve on UK data 1861-1957. A pure cost-push shock changes the calculus: tightening into a supply contraction risks amplifying the recession without addressing the source of inflation, since the central bank cannot drill more oil, build more containers, or end a war. The standard prescription is to “look through” first-round effects and act only if second-round effects (wage indexation, expectations de-anchoring) become visible. We unpack this asymmetry in our coverage of the rate-hike mechanism central banks deploy against inflation.
The mistake in either direction is symmetric and historically costly. In the 1970s, the Fed under Arthur Burns repeatedly assumed inflation was cost-push and refused to tighten decisively, allowing expectations to de-anchor — a misdiagnosis Volcker had to undo with the deepest postwar recession. In 2021-2022, several central banks made the opposite error: they assumed the surge was supply-driven and “transitory,” waited too long, and then had to tighten faster than markets had priced. The mirror angle is handled in the article on Bitcoin and Inflation: An Empirical Test of the Store-of-Value Narrative. The Fed funds rate moved from 0.25% in March 2022 to 5.50% by July 2023 — 525 basis points in 16 months, the steepest cycle since 1981 (Federal Reserve H.15).
The cost-push/demand-pull split is not theoretical taxonomy: it is the diagnostic that determines whether tightening cures the disease or amplifies the recession. The full picture is drawn in the complete analysis of inflationary forces.
Beyond inflation: real wages and corporate margins move in opposite directions
The two logics also produce different distributional outcomes. Demand-pull episodes typically coincide with rising real wages early in the cycle, because labour-market tightness lifts nominal wages faster than prices initially, before the gap closes. Cost-push episodes, especially energy shocks, tend to compress real wages immediately, because the price shock hits before wages adjust. The 2022 European data illustrates the pattern: euro-area negotiated wages grew 4.7% year-on-year in Q4 2023 (ECB), while HICP had peaked at 10.6%, leaving real wages roughly 5 percentage points below their 2021 trajectory. This compression is one reason the eurozone tightening cycle could be slower than the U.S. one without de-anchoring expectations: the silent erosion of purchasing power even when nominal salaries rise was the macro buffer absorbing the shock.
Corporate margins behave inversely. In demand-pull episodes, margins tend to expand as firms exercise pricing power into excess demand. In cost-push episodes, margins compress as input costs rise faster than firms can pass through. The 2022 controversy about greedflation, whether corporate markups contributed independently to inflation, sits exactly at this intersection, and we examine the underlying data in a dedicated piece on the structural shift of the inflation regime tied to deglobalization, where margin behaviour is one of the diagnostic variables.
Treating “supply” and “transitory” as synonyms. A supply shock can be persistent (demographics, energy transition, deglobalization), and a demand shock can be quickly absorbed if monetary policy reacts. The duration of a shock is independent of its cause, and assuming otherwise was the systematic error of 2021-2022.
The structural twist: when the line between supply and demand blurs
The classical framework assumes aggregate supply and aggregate demand are independent, but several modern phenomena undermine that separation. Fiscal dominance, large-scale balance-sheet expansion, and persistent supply-side reconfiguration (deglobalization, ageing labour forces, climate-related disruptions) generate inflation profiles that resist clean attribution. The pillar piece on the complete framework for understanding inflation mechanisms, measurement, history and effects develops this point: the 1970s framework (clean Phillips curve, well-anchored expectations, predictable transmission) may not generalise to a regime where supply shocks recur and fiscal policy operates near the zero lower bound.
The dataset on U.S. inflation history since 1913 shows that long-run inflation episodes have rarely been monocausal: the post-WWII surge combined demand release and supply rebuilding; the 1970s combined oil shocks and accommodative monetary policy; the post-2020 episode combined fiscal stimulus, supply-chain breakdown, and an energy shock. The honest analytical posture is to accept that the cost-push/demand-pull split is a diagnostic axis, not a binary classification.
- Demand-pull inflation arises from aggregate demand exceeding productive capacity; cost-push from aggregate supply contracting under stable demand. Same index, opposite mechanisms.
- The Bernanke-Blanchard 2023 decomposition attributed roughly 60% of the 2021-2022 U.S. inflation surge to supply factors and 40% to demand pressure, with the mix evolving over time.
- Misdiagnosing the source historically costs central banks credibility: Burns underestimated demand in the 1970s; several central banks underestimated demand in 2021-2022.
- The two logics produce opposite distributional effects: demand-pull lifts real wages early and expands corporate margins; cost-push compresses both.
Beyond the binary: a diagnostic posture, not a classification
The most useful framing for the reader is not “which type is this?” but “what mix is this, and how does the mix evolve over the next four quarters?” Energy shocks fade if upstream prices stabilise; demand pressure persists if labour markets remain tight. The 2024-2026 European disinflation was largely an energy normalisation; the residual core inflation in services reflected the lagged demand-pull component still working through the system. The investor lens, the household lens, and the central-bank lens all converge on the same question: what share of inflation can monetary policy address, and what share lies beyond its reach?
This question structures the rest of the cluster: the role of how inflation expectations form and why they anchor or de-anchor, the dynamics of wage-price spirals as an amplification mechanism, and the limits of the Phillips curve as a guide when supply shocks recur. Each adds a layer to the diagnostic.
Frequently asked questions
What is the difference between demand-pull and cost-push inflation?
Both raise the price level, but through opposite doors. Demand-pull inflation comes from spending outgrowing productive capacity, so output and employment rise with prices. Cost-push inflation comes from a jump in production costs, so output falls as prices rise. Real GDP and unemployment during the episode are the practical tell.
What are the three types of inflation?
Macroeconomics usually lists three sources: demand-pull, cost-push and built-in inflation, the grouping Robert J. Gordon formalised as the “triangle model”. Built-in inflation is the part that persists on its own once wages and prices are set with past inflation in mind, the loop taken apart in how a wage-price spiral sustains itself. A cost-push or demand-pull shock that feeds this loop outlasts its original cause.
What is an example of demand-pull inflation?
The U.S. in 2021-2022 is the most documented recent case. The $1.9 trillion American Rescue Plan, signed in March 2021, landed on an economy whose output gap turned positive by mid-2021 (CBO), and the vacancy-to-unemployment ratio stayed above 1.9 throughout 2022. Supply bottlenecks were active at the same time, which is why decompositions still split that episode between the two causes.
How is cost-push inflation shown on a diagram?
On the AD-AS diagram above, cost-push inflation is a leftward shift of the aggregate supply curve, from AS0 to AS1. The new equilibrium sits higher and further left, with a higher price level and lower real output. Demand-pull inflation is the mirror case, a rightward shift of aggregate demand that raises both.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Inflation and Stocks: 100 Years of Data
One hundred years of equity returns under different inflation regimes produce a counterintuitive empirical pattern: stocks have historically…
MMT and Inflation: What Modern Monetary Theory Actually Says
MMT is treated either as the doctrine of unlimited money printing or as a self-evident truth about monetary…
Inflation Expectations: How They Form and Why They Matter
Inflation expectations: the forward-looking variable central banks watch most closely, because once they de-anchor, every other inflation diagnostic…