Social Security Trust Fund: Full Benefits Through 2034, Then 83%
Social Security's trust fund, under current law
All figures: SSA 2026 OASDI Trustees Report. Toggle the views below.
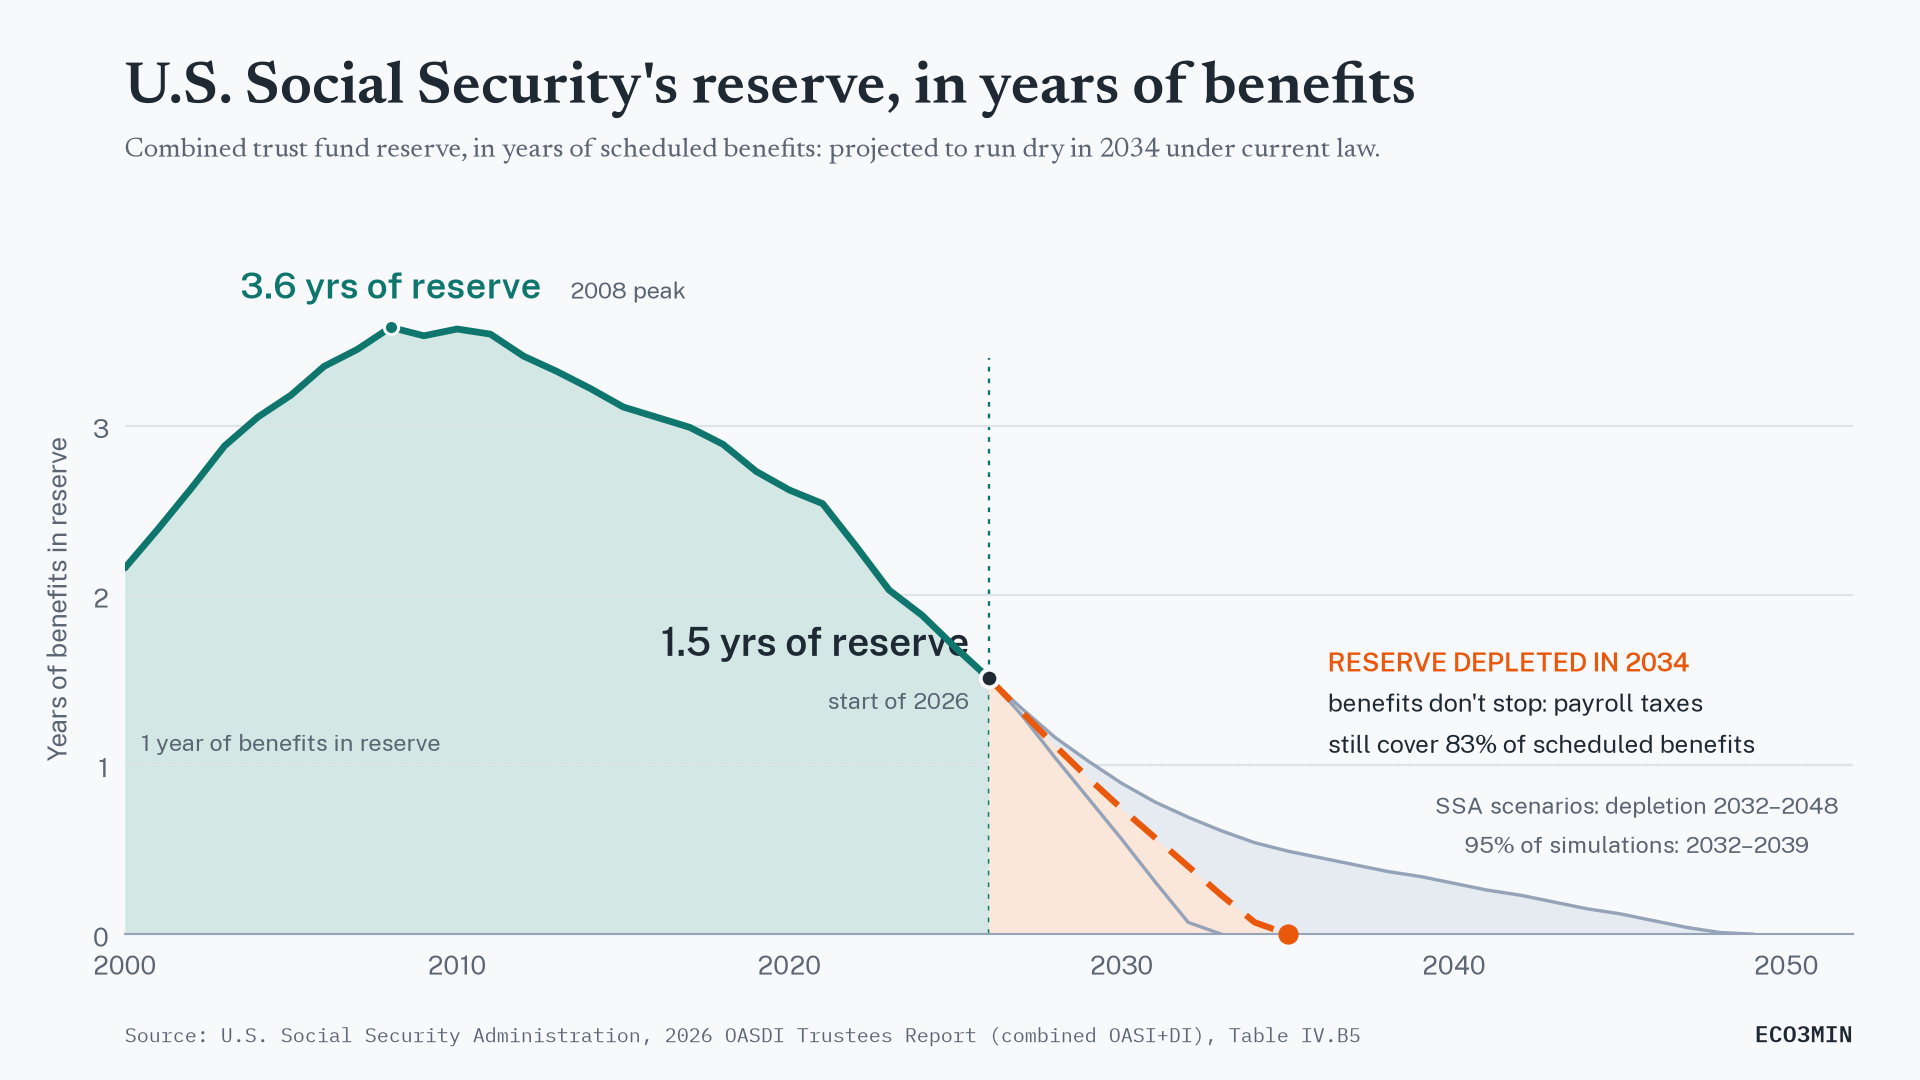
In short. Social Security is projected to pay full benefits through 2034; after that, under current law, continuing payroll taxes would still cover 83% of scheduled benefits, a 17% shortfall, not zero. The combined trust fund peaked at about 3.6 years of benefits in reserve in 2008; on the Trustees’ best estimate that reserve runs dry in 2034, with a range across official scenarios of 2032 to 2048.
The combined Social Security trust fund, the reserve that backs U.S. retirement and disability benefits, is being drawn down. On the Social Security Administration’s 2026 best-estimate (“intermediate”) projection, the combined fund is sufficient to pay scheduled benefits in full through 2034. When the reserve is depleted, the program does not stop: continuing payroll-tax income would still cover 83% of scheduled benefits, declining to 65% by 2100, unless Congress changes the law. The reserve depletion date is the most-cited number in the debate, but it sits inside a range, 2032 in the high-cost scenario, 2048 in the low-cost scenario, with 95% of the SSA’s stochastic simulations falling between 2032 and 2039.
This page places that drawdown on a long timeline and documents what “depletion” does and does not mean, with the underlying dataset available for download. The narrower point established by the data is that the common framing, that Social Security is “going bankrupt” or “won’t be there”, does not match the Trustees’ own arithmetic: the system faces a real, sizable shortfall that grows the longer action is deferred, but not a fall to zero.
Key Findings at a Glance
Headline: Full benefits projected through 2034; then 83% payable under current law, a 17% shortfall, not zero.
Source & basis: SSA 2026 OASDI Trustees Report (released June 9, 2026), combined OASI+DI, intermediate assumptions (set February 2026)
Reserve at end of 2025: about $2.56 trillion in special-issue U.S. Treasury securities
Reserve peak: about 3.6 years of benefits (358% of one year’s cost) in 2008
Reserve now (start of 2026): about 1.5 years of benefits (151% of one year’s cost)
Combined depletion (best estimate): 2034 (third quarter), range 2032 (high-cost) to 2048 (low-cost); 95% of stochastic runs land 2032–2039
Payable at depletion (combined): 83% of scheduled benefits, declining to 65% by 2100
Retirement fund alone (OASI): depletes in the fourth quarter of 2032, with 78% of scheduled benefits then payable
Disability fund (DI): not projected to deplete within the 75-year window
75-year actuarial deficit: 4.42% of taxable payroll (up from 3.82% in the 2025 report)
Demographic driver: covered workers per beneficiary fell from 3.2–3.4 (1974–2008) to about 2.6 in 2025, projected to reach 2.3 by 2040
In 2008, Social Security had 3.6 years of benefits banked. On current projections, that reserve runs dry around 2034.
What the trust fund actually is
The common framing of Social Security’s finances is that the program is “going bankrupt” or “won’t be there” for younger workers. That framing is widely held, and it is not baseless: the system has run a cash-flow gap since 2021, when total cost first exceeded total income, and its cost has exceeded non-interest income every year since 2010. The reserve that bridges that gap is finite.
What the reserve is, precisely, is an accumulated balance held in special-issue U.S. Treasury securities. It was built up deliberately. Following the 1983 reforms, payroll-tax income was set above current benefit cost so that the baby-boom generation would pre-fund part of its own retirement; the combined reserve rose for a quarter-century, peaking in 2008 at 358% of one year’s cost, about 3.6 years of benefits held in reserve. Since then the ratio has declined, with a single uptick in 2010, to 151% (about 1.5 years) at the start of 2026. The fund is now being drawn down, as designed, to help pay the benefits of the generation that pre-funded it.
Measuring the reserve in years of benefits rather than dollars makes the trajectory legible: a reserve worth three-plus years of benefits in 2008, worth under two years today, and, on the best estimate, worth essentially nothing by 2034. At the end of 2025 the combined reserve stood at about $2.56 trillion, down from $2.72 trillion a year earlier and from a nominal peak of about $2.91 trillion at the end of 2020.
When the reserve runs dry, and how uncertain that date is
On the Trustees’ intermediate (best-estimate) assumptions, the combined OASI and DI reserve declines to about 7% of one year’s cost at the start of 2034 and is depleted during that year. The single date, 2034, is the figure that dominates headlines, but it is a point estimate inside a distribution. The Trustees publish three scenarios: depletion in 2034 under the intermediate case, 2032 under the high-cost case, and 2048 under the low-cost case. Their stochastic model, which runs 5,000 simulations, places the depletion year between 2032 and 2039 in 95% of runs.
The chart above shows this as a fan: a single historical line through 2025, then three diverging paths. The width of the fan is the honest measure of how much is unknown, and it is the reason a precise single-year claim is more accurately read as a central estimate than as a certainty. The date has also moved between reports: the 2024 report put combined depletion at 2035 and the 2025 report at 2034. The 2026 report keeps it in the same quarter, the third of 2034, while the 75-year deficit widened from 3.82% to 4.42% of taxable payroll. The date depends on income and cost through 2034; the deficit covers the whole 2026-2100 horizon, where the lower fertility assumption is the largest contributor to the revision.
What “depletion” does, and does not, mean
Depletion of the reserve does not mean benefits stop. Payroll taxes continue to flow in, and under current law that continuing income would cover 83% of scheduled benefits at the combined-fund depletion in 2034, a share that declines to 65% by 2100. Stated as a cut, depletion implies an automatic reduction of about 17% in 2034, growing to 35% by 2100, absent congressional action.
Three qualifications belong here, and they cut in both directions.
First, the “83%” combined figure assumes a legal change that has not happened. By law, OASI (retirement and survivors) and DI (disability) are separate funds, and money cannot move between them without legislation. The retirement fund alone is projected to deplete earlier, in the fourth quarter of 2032, at which point OASI income would cover 78% of scheduled retirement benefits, not 83%. The combined 83% figure presupposes that Congress would authorize cross-fund transfers. For a retired worker on the average benefit, which the SSA estimates at $2,170 a month in January 2027 after the 3.6% cost-of-living adjustment, the OASI-only path to 78% implies a reduction on the order of $480 a month if nothing is changed before 2032.
Second, “the trust fund pays benefits through 2034” understates the financing question. The reserve is held in U.S. Treasury securities, that is, it is intra-governmental debt. Redeeming it to pay benefits requires the Treasury to raise the cash, through taxes, borrowing from the public, or spending reductions elsewhere. The reserve is a real legal claim that genuinely backs benefits through depletion; it is not, however, a pool of cash sitting apart from the rest of the federal budget. Both readings, “the fund is real” and “redeeming it has a general-budget cost”, are correct, and the gap between them is where much of the public disagreement lives. For the broader picture: the systemic-fragilities and debt framework.
Third, a 17–22% cut is materially serious even though it is not zero. Social Security is the majority of income for a large share of beneficiaries, and for that group an automatic reduction of one-sixth to over one-fifth would be consequential. “Not bankruptcy” is an accurate correction to the headline; it is not a statement that the shortfall is small.
Why the reserve is draining
The drawdown is demographic before it is anything else. The number of covered workers supporting each beneficiary held between 3.2 and 3.4 from 1974 to 2008; it has fallen since, to about 2.6 in 2025, and is projected to reach 2.3 by 2040 as the baby-boom generation retires and lower-birth-rate cohorts replace it at working ages. A pay-as-you-go system whose worker-to-beneficiary ratio falls runs a structural gap unless its tax rate or benefit formula adjusts.
Three revisions moved the 2026 projection. The Trustees lowered the assumed ultimate fertility rate from 1.90 to 1.75 children per woman, the largest single contributor, which alone reduces the 75-year actuarial balance by 0.33% of taxable payroll. They lowered the assumed ultimate level of temporary or unlawfully present immigration from 1.35 million to 1.2 million a year from 2035 (0.12 point). And the One Big Beautiful Bill Act, signed July 4, 2025, reduces many beneficiaries’ taxable income and with it the trust funds’ income from the taxation of benefits (0.16 point). With the one-year advance of the valuation period and other data, economic and method updates that partly offset one another, the 75-year actuarial deficit rose from 3.82% of taxable payroll in the 2025 report to 4.42% in 2026. A companion question: why the Social Security claiming age is a critical decision.
What closing the gap would take
The Trustees quantify the size of the shortfall in two standardized ways, both descriptive rather than prescriptive. To keep the combined fund solvent across the full 75-year window starting in 2026, revenue would have to rise by the equivalent of an immediate, permanent payroll-tax increase of 4.25 percentage points (from 12.40% to 16.65%), or scheduled benefits would have to fall by the equivalent of an immediate, permanent 25.2% reduction applied to all current and future beneficiaries, or some combination. The arithmetic of deferral is the part most relevant to the depletion date: if action is delayed until the reserve is depleted in 2034, the same 75-year solvency would require a 4.90-point tax increase (to 17.30%) or a 28.5% benefit reduction, larger changes concentrated on fewer years and fewer cohorts.
These figures are the Trustees’ own illustrations of magnitude. They are not a menu of recommendations, and the historical record offers no single template: past solvency packages (1977, 1983) combined tax increases, coverage expansions, a higher retirement age, and benefit-formula changes phased in over years.
Key Dates to Watch
Invalidation of the current reading: enactment of a solvency package (a payroll-tax change, a benefit-formula change, a retirement-age change, or a general-revenue transfer) would move the projected depletion date and the payable share. Absent legislation, the reading stands.
Confirmation signal: the 2026 Trustees Report held the combined depletion year and widened the 75-year deficit. If the 2027 report holds or advances that year and the deficit widens again, the trajectory documented here would be reinforced. A later date or a narrower deficit would soften it. Companion analysis: The debt-ceiling liquidity study.
Calendar catalysts: the next OASDI Trustees Report (typically released in the first half of the year) and the Congressional Budget Office’s long-term budget and Social Security updates are the scheduled releases that would revise these figures.
Counter-Arguments and Limitations
The date is a projection, not a measurement. Depletion in 2034 is the intermediate estimate; the official range is 2032 to 2048 and the stochastic 95% interval is 2032 to 2039. Economic growth, immigration, fertility, mortality, and disability incidence all feed the result, and a sustained surprise in any of them would move the date materially. Related coverage: The cluster on macro-financial regimes.
“Combined” is a legal fiction used for illustration. The OASI and DI funds are separate. Presenting them combined is standard SSA practice for showing the system’s overall status, but the operative dates for retirement specifically are the OASI numbers (2032, 78%).
The trust-fund accounting is genuinely contested in interpretation, not in arithmetic. The reserve balance and the redemption mechanics are not in dispute; what people disagree about is whether describing benefits as “funded through 2034” adequately conveys that redemption draws on the unified federal budget. This page documents both the balance and the mechanics so the reader can weigh the framing.
Projection changes are incremental, and the framing is robust to them. A 20% swing in the deficit or a few-year move in the date would not change the structural conclusion, a sizable, deferrable shortfall short of zero. A change large enough to overturn that conclusion (for example, restoring permanent solvency without legislation) is not present in any of the three official scenarios.
Common Misinterpretations
“Social Security is going bankrupt.” The program cannot “go bankrupt” in the corporate sense: payroll taxes continue regardless of the reserve, and they would fund 83% of scheduled benefits (combined) or 78% (OASI alone) at depletion. The accurate statement is a reserve depletion and an automatic benefit reduction, not a fall to zero.
“It won’t be there for me.” On current law and current projections, a worker retiring after 2034 would receive a reduced benefit, not no benefit. The size of the reduction depends on whether and how Congress acts before then.
“The trust fund is just IOUs / was raided.” The reserve is invested, by law, in interest-bearing U.S. Treasury securities, the same instrument held by private and foreign investors. It was not diverted to other spending in a way that removed the legal claim; it earns interest and is redeemed to pay benefits. The interpretive point above, that redemption draws on the general budget, is the substantive version of this concern.
“The 2034 date keeps slipping, so it’s not credible.” The combined date has in fact moved both later and earlier across reports (2035 in the 2024 report, 2034 in the 2025 and 2026 reports). Movement reflects updated economics and law, not a lack of credibility; the multi-decade direction, a declining reserve ratio since 2008, has been consistent.
Methodology and Sources
Primary source. Social Security Administration, 2026 Annual Report of the Board of Trustees of the OASI and DI Trust Funds, combined OASI+DI, intermediate assumptions (assumptions set February 2026; report released June 9, 2026). All plotted series are SSA-published values; none are interpolated.
Reserve runway. The trust fund ratio, reserves at the beginning of a year as a percentage of that year’s cost, is taken directly from Table IV.B5 of the report (historical values through 2025, then the three scenarios). A ratio of 100% equals one year’s cost held in reserve; the chart re-expresses the ratio as years (ratio ÷ 100). Because roughly 99% of program cost is benefit payments, “years of cost” and “years of benefits” are used interchangeably in the lay framing; the precise definition is reserves ÷ annual cost.
Scenarios and uncertainty. Alternative I (low-cost), II (intermediate, best estimate), and III (high-cost) are the Trustees’ standard scenarios. The combined fund depletes during 2048, 2034 and 2032 under I, II and III respectively. The 2032–2039 window is the 95% interval from the report’s 5,000-run stochastic model.
Payable share. 83% at combined depletion in 2034 and 65% by 2100 are SSA-published. The intermediate path between those two endpoints is shown as a straight segment; only the endpoints are SSA values. OASI-alone figures (depletion in the fourth quarter of 2032, 78% payable, 62% by 2100) are likewise SSA-published.
Solvency illustrations. The +4.25-point payroll-tax figure (to 16.65%), the 25.2% benefit-reduction figure, and the deferred-to-2034 figures (+4.90 points, to 17.30%; 28.5%) are the Trustees’ standardized illustrations of the 75-year actuarial deficit (4.42% of taxable payroll), not Eco3min estimates.
Context figures. Reserve balances ($2.56 trillion end-2025; $2.72 trillion a year earlier; ~$2.91 trillion nominal peak at end-2020), beneficiary and worker counts (about 70 million and 185 million in 2025), worker-to-beneficiary ratios, and the effects of the One Big Beautiful Bill Act are from the same report. The average retired-worker benefit ($2,170 a month estimated for January 2027, after the 3.6% COLA) is from the SSA’s 2027 COLA fact sheet.
Reproducibility. The full dataset, historical and projected trust fund ratios for all three scenarios, the payable-share and depletion figures, the demographic and solvency figures, with a source field per row, is available below as CSV. The chart is generated with Python (matplotlib).
Frequently Asked Questions
Is Social Security going bankrupt?
No, in the sense that the program cannot run out of all funding while payroll taxes continue. On the Trustees’ best estimate, the combined trust fund reserve is depleted in 2034; at that point continuing payroll-tax income would cover 83% of scheduled benefits (78% for the retirement fund alone, depleted in 2032), declining to 65% by 2100, unless Congress acts. The accurate description is a reserve depletion and an automatic benefit reduction, not a bankruptcy.
Will I get nothing when the trust fund runs out?
On current law and current projections, a person receiving benefits after depletion would get a reduced benefit, on the order of 83% of the scheduled amount (combined) or 78% (retirement fund alone), not zero. The size of any reduction depends on whether Congress changes the law before then.
Why do different sources give different dates (2032, 2033, 2034, 2035)?
The dates refer to different things. 2034 is the combined OASI+DI fund on the SSA’s intermediate assumptions, in both the 2025 and 2026 reports. 2032 is the retirement fund (OASI) alone in the 2026 report, which the 2025 report put in 2033. 2035 was the combined date in the 2024 report. All sit inside the official 2026 range of 2032 to 2048.
What is the difference between OASI and DI?
OASI is the retirement and survivors fund; DI is the disability fund. They are legally separate. OASI is the fund under pressure (depletion projected in 2032, 78% payable). DI is not projected to deplete within the 75-year window; its reserve ratio is projected to rise. The widely cited combined “OASDI” date assumes the two could be merged, which would require legislation.
Is the trust fund “real,” or just IOUs?
Both descriptions point at the same fact. The reserve is held in interest-bearing special-issue U.S. Treasury securities, a real legal claim that earns interest and is redeemed to pay benefits. Because those securities are obligations of the federal government, redeeming them to pay benefits requires the Treasury to raise the cash from taxes, borrowing, or other spending. The reserve genuinely backs benefits through depletion; redeeming it is not free to the broader budget. Redemption of that kind lands on a budget already running full-employment deficits above 5% of GDP, an unusual starting point for an extra draw.
What would it take to close the gap?
The Trustees illustrate the 75-year shortfall as the equivalent of an immediate, permanent payroll-tax increase of 4.25 percentage points, or an immediate, permanent 25.2% reduction in scheduled benefits, or a combination. Delaying action until depletion in 2034 raises those figures to 4.90 points or 28.5%. These are descriptive measures of the deficit’s size, not recommendations; actual policy choices would combine measures and phase them in.
Download the Complete Dataset
Historical and projected trust fund ratios (all three Trustees scenarios), payable-share and depletion figures, demographic and solvency figures, with a source field per row.
Source: eco3min.fr, SSA 2026 OASDI Trustees Report. Eco3min text and analysis: CC BY 4.0. Data, files and charts remain subject to their producer’s terms, stated on each page; Eco3min grants no licence over third-party data.
Conclusion
Social Security’s combined trust fund is being drawn down from a reserve worth about 3.6 years of benefits at its 2008 peak to, on the best estimate, essentially nothing by 2034. The reserve depletion is real, and the resulting automatic shortfall, about 17% combined, 22% for the retirement fund alone, is sizable and grows the longer action is deferred. It is also not zero: payroll taxes would continue to fund the large majority of scheduled benefits under current law. The wider context: who bears retirement risk now.
The gap between “going bankrupt” and “a deferrable shortfall short of zero” is the substance of the policy debate, and the dataset behind this page is meant to let readers locate themselves in it precisely rather than rhetorically. This page documents the Trustees’ arithmetic and the range around it; it does not forecast which way Congress will act, and it will be updated as new Trustees and CBO figures are published.
Last updated — 21 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader.
Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it.
Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Regulated and tax values: the rates, indices, caps and brackets with legal effect cited on this page are set by official decision, change over time and apply according to individual circumstances. Only the official publication in force on the relevant date is authoritative (for example the Journal officiel, INSEE, Banque de France, the IRS or the Social Security Administration). To revise a rent, sign or challenge a contract, or file a return, check the value at the source or with a professional.