
Stocks vs bonds: what the long-run data shows
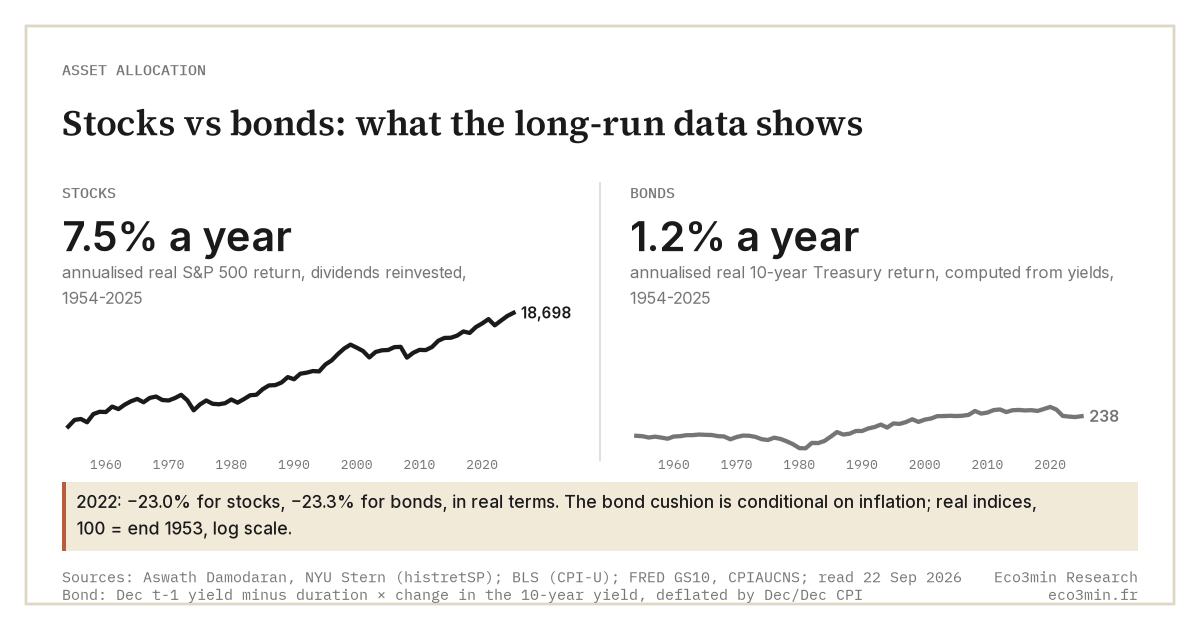
Stocks are residual claims on corporate earnings; bonds are fixed claims on a defined stream of payments. Over 1900–2024, US equities returned roughly 6.6% a year in real terms versus far less for bonds (Dimson-Marsh-Staunton, 2025), but the decisive difference is not that return gap. It is that bonds only cushion equity drawdowns when inflation is low and stable, a property 2022 stripped away.
In this comparison
Why this comparison matters
Stocks and bonds are usually framed as opposites: one for growth, the other for safety. That framing is incomplete. Both are claims on future cash flows, valued off the same discount rate, and their relationship is not fixed: it shifts with the inflation regime. The year 2022, when both fell hard together, was a reminder that the safety half of a balanced portfolio is conditional rather than guaranteed, and that the conditioning variable is inflation.
What stocks are
A stock is a residual claim on a company’s profits: shareholders are paid after every other obligation, but they capture the upside when earnings grow. Long-run returns come from three sources: dividends, earnings growth, and changes in the valuation multiple investors are willing to pay. Because nominal earnings tend to rise with prices over time, equities behave as a claim on a growing nominal stream. Over 1900–2024, US equities delivered about 6.6% annualized real returns, the highest of any major asset class (Dimson-Marsh-Staunton database, 2025).
→ Complete breakdown: What drives stock market returns over the long run?
What bonds are
A bond is a fixed claim: the issuer promises defined coupon payments and the return of principal at maturity. Its price moves inversely to yields, when market rates rise, the fixed coupons of an existing bond become less attractive, so its price falls, and the longer its duration the larger that move. Over 1900–2024, US government bonds returned far less than equities in real terms (DMS, 2025), but with far smaller drawdowns in most regimes. The exception is inflation: because the payments are nominal and fixed, rising inflation erodes their real value directly.
→ Complete explanation: Why do bond prices fall when yields rise?
The key differences
Claim structure. Equity value rises with nominal earnings, which tend to grow alongside inflation over the long run; a nominal bond’s payments are fixed in advance, so inflation erodes their real value. This is the structural reason the two assets can respond in opposite directions, or the same direction, to a given macro shock. Built around that split in behaviour, the All Weather portfolio associated with Ray Dalio weights its assets by how they respond to growth and inflation surprises rather than by expected return.
Return and risk. The excess return equities have historically earned over government securities (the equity risk premium) has stayed positive globally relative to Treasury bills over the long run (DMS/UBS Yearbook, 2025). That premium is compensation for far larger losses: a deep equity bear market can cost 40–50%, while high-quality government bonds rarely fall that far in a single episode.
Diversification, conditionally. Inside a portfolio, bonds matter less for their own return than for how they move relative to stocks. That co-movement is not a constant of nature: it is the dimension investors most often misread, and the one that decided whether 2008 and 2022 felt alike or opposite. Misreading it is the kind of error that the common mistakes about asset allocation are made of.
How they behave across regimes
In recession-driven, disinflationary shocks the two diverge: in 2008 equities fell sharply while 10-year Treasuries rallied, cushioning a 60/40 portfolio. In inflation-driven shocks they converge: in 2022 the Bloomberg US Aggregate lost 13.0%, its worst calendar year on record. The S&P 500 also fell 18.1% that year. A 60/40 mix also had its worst year since 1937 (Morgan Stanley). The pivot is the inflation regime. When inflation is low and stable, the stock-bond correlation tends to be negative and bonds cushion equities; when inflation is high and volatile, the correlation turns positive and both fall to the same shock, rising real rates, because the same discount rate is repricing both claims at once.
Bonds hedge equities in a disinflationary world and abandon them in an inflationary one: the diversification is borrowed from the regime, not built into the asset.
→ Framework: Asset allocation across market regimes
The common confusion
The frequent error is to treat the negative stock-bond correlation of roughly 2000–2021 as a permanent law of markets. It was the feature of a specific regime: two decades of low, stable inflation. Across the full 1900–2024 record the correlation has changed sign repeatedly, sitting positive through much of the high-inflation 1970s and early 1980s, and again in 2022. Bonds are a diversifier of equities in some regimes and a co-casualty in others; the property belongs to the regime, not to the bond. Properties that belong to a regime rather than to an asset turn up wherever the sample is thin, as in the concentration that governs a fine wine index.
Practical observation
What the data suggests for framing your own analysis:
- Question to ask yourself: in the current inflation regime, is the stock-bond correlation more likely to behave as it did in 2008 or as it did in 2022?
- Data to monitor: the rolling stock-bond correlation, the level and volatility of CPI, and the level of real (inflation-adjusted) 10-year yields.
- Historical parallel: 2008 (bonds up, equities sharply down) versus 2022 (bonds −13%, equities −18%), two opposite outcomes set by the inflation backdrop.
- What the literature documents: the long-run Dimson-Marsh-Staunton dataset on equity and bond real returns and risk premia.
This is descriptive information to help you frame your own analysis. Eco3min does not provide investment advice.
Go deeper
📊 Related question: What is the equity risk premium and how is it measured?
📁 Context: Why has the 60/40 portfolio evolved in the 2020s? · Portfolio allocation architectures
Related guides
Frequently asked questions
How do stocks and bonds differ as long-run investments?
Stocks are residual claims on corporate earnings that grow over time; bonds are fixed claims on a defined set of payments. Over 1900–2024, US equities returned about 6.6% annualized in real terms against far less for bonds (DMS, 2025). Equities paid for that gap with far larger losses: deep bear markets have cost equity investors 40–50%, while high-quality bonds historically fell far less, except when inflation surged, as in 2022.
When do bonds stop diversifying equities?
Bonds diversify equities when the two move in opposite directions, which has historically held in low, stable inflation regimes: the stock-bond correlation was negative through most of 2000–2021. When inflation rises sharply, the correlation flips positive and both assets fall to the same shock, rising real rates. In 2022 the S&P 500 fell 18.1% in the very year the US Aggregate had its worst calendar year on record, the clearest recent example of bonds offering no cushion.
What does the long-run return gap between stocks and bonds reflect?
The gap is the equity risk premium: the extra return investors have historically required to hold a residual claim on uncertain earnings rather than a fixed claim. Globally, that premium has stayed positive over Treasury bills in the long run (DMS/UBS, 2025). It is not a free lunch: it is paid for with the volatility and drawdown risk that high-quality bonds, in most regimes, do not carry. Every asset class advertises a long-run number, and the question that decides it is always what the holder kept: the distance between a headline index and a holder’s return. Long-run series of that kind are drawn from listed companies alone, and that universe stopped expanding for the reasons behind why capital found it easier to stay private.
Last updated — 3 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →TIPS vs nominal Treasuries: what breakevens reveal
Nominal Treasuries pay a fixed coupon; TIPS adjust their principal with realised CPI inflation. The real choice between…
Fed vs ECB: two mandates compared
The Federal Reserve operates under a dual mandate (maximum employment and stable prices) set by the US Congress.…
LEI vs PMI: comparing leading indicators
The LEI is a single composite of ten forward-looking series published monthly by The Conference Board; a PMI…