
The Investing Mistakes That Cost Beginners the Most
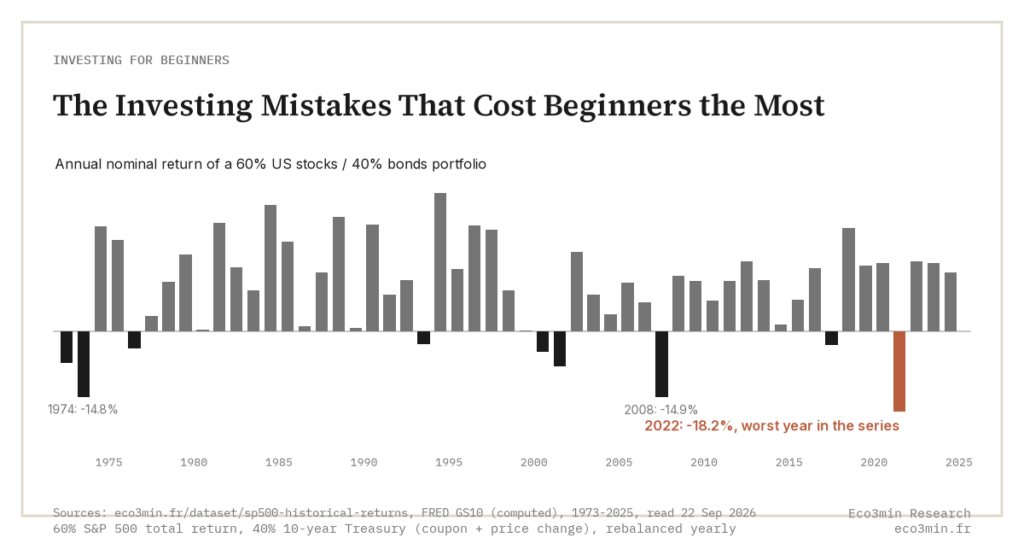
The costliest mistakes aren’t technical. They’re not about “timing” or “diversification.” They’re errors of context: correct rules applied in a regime where they no longer work.
Every beginner guide lists the same mistakes: panic selling, trying to time the market, not diversifying. These warnings are useful. But they’re superficial: they describe symptoms without tracing the cause. The cause, in most cases, is a misunderstanding of the economic context.
The costliest mistakes aren’t discipline failures but reading failures: applying a correct rule in a regime where its conditions of validity have disappeared.
- In 2022, the 60/40 portfolio lost 16%, its worst year since the 1970s: “diversify” assumes a stock-bond correlation that is a regime property, not a law.
- Behavioral biases cost the average investor about 1.1 points per year over twenty years (Dalbar). With a 1.5-point gap over 30 years at $200 a month, the shortfall reaches roughly $61,000 (Eco3min calculation), on par with fees and taxes combined.
- Record inflows to growth funds in 2021 (ICI) right before the Nasdaq’s 33% drop in 2022 illustrate the mechanism: buying the regime that just ended.
Mistake #1: Confusing displayed return with real return
The most widespread and most silent error. A bond fund showing 4% in 2022 seemed positive. With CPI at 9.1% (BLS), purchasing power dropped by over 5%. The same mechanism applies to real estate: a house bought for $400,000 and sold for $420,000 three years later shows a “5% gain.” If cumulative inflation was 12%, the real return was −7%, before closing costs and maintenance.
The distinction between real and nominal returns is the first filter to apply to any financial decision.
Mistake #2: Applying the rules of a regime that has changed
From 2009 to 2021, an exceptional environment prevailed: near-zero rates, low inflation, abundant liquidity. In this regime, almost everything worked. Stocks, bonds, real estate, crypto, the 60/40 portfolio(all went up. In 2022, the regime shifted) particularly as interest rates transmitted through the economy and as markets diverged from the real economy. The consequences were brutal for those still operating on the old playbook:
The 60/40 portfolio lost 16%, its worst year since the 1970s. Stocks fell 19% (S&P 500). Long bonds fell 31% (ICE BofA). The correlation between them, usually negative, turned positive. The “diversification that always works” stopped working, because it worked in a specific regime, not universally.
Flows into tech/growth funds and crypto peaked exactly at the top. Inflows to equity growth funds hit records in 2021 (ICI), right when the Nasdaq was about to drop 33%. Bitcoin peaked in November 2021, then lost more than three quarters of its value from peak to trough (CoinGecko). Investors buy when euphoria peaks and sell when fear peaks: the exact inversion of any allocation logic. This gets a fuller treatment in our roundup of historical stress episodes.
US home prices stalled in most markets after the fastest rate-hiking cycle in 40 years pushed mortgage rates from 3% to 7.5%. The narrative that “real estate always goes up” was calibrated on the 2012-2022 cycle, itself powered by a once-in-a-generation decline in rates from 4.5% to 2.7%. That cycle reversed.
The common thread: rules that worked perfectly in one regime were extrapolated into a different one. The error isn’t in the rule; it’s in the absence of conditionality. The sub-pillar Reading the Cycle, Adjusting Exposure develops the framework for identifying regime changes without making predictions.
Mistake #3: Believing that “diversify” is enough to protect you
Diversification rests on the assumption that assets don’t all decline simultaneously. In a low-inflation, stable-rate regime, this is historically verified: when stocks fall, bonds rise (negative correlation). But when inflation becomes the dominant problem, this correlation flips: stocks and bonds fall together, and “diversification” stops cushioning anything.
In 2022, that’s exactly what happened. “Diversify” is not advice; it’s an implicit bet on a correlation regime. The sub-pillar Asset Allocation Fundamentals deconstructs the assumptions behind each diversification approach.
Mistake #4: Underestimating the impact of fees and taxes
An investor choosing an actively managed fund at 1.0% annual fees instead of an index ETF at 0.03% loses ~0.97 points per year. On $300/month over 25 years, that difference represents roughly $34,000 less (about 16% of the total): 9 years of monthly contributions erased by fees alone. The large majority of active funds underperform their benchmark over 15 years in the US (SPIVA, S&P Global).
Taxes work the same way. A Roth IRA at 0% tax on withdrawals preserves significantly more than a taxable account at 15% LTCG, and taxes hit nominal gains, including the portion that merely compensates for inflation.
Mistake #5: Letting emotions drive decisions
The average investor underperformed the index by about 1.1 points per year over the twenty years to end-2024 (Dalbar QAIB 2025). Not because of fees, but because of their own decisions: buying at the peak of optimism, selling at the peak of fear, changing strategy after a bad year.
Over 30 years, a gap of 1.5 points a year (an illustrative Eco3min assumption) turns $200/month at 7% ($244,000) into $200/month at 5.5% ($183,000). The difference (about $61,000) is the cost of behavioral biases: on par with the impact of fees and taxes combined. The best antidote isn’t willpower; it’s automation. An automated DCA into a diversified ETF eliminates nearly all emotional decisions. The sub-pillar The Traps of the Mind analyzes these mechanisms in depth.
Mistake #6: Confusing quantity of information with quality of understanding
The beginner investor has access to more information than ever: financial news feeds, YouTube recommendations, Reddit threads, Substack newsletters. The problem isn’t lack of information; it’s excess, and the absence of a framework to separate signal from noise. Following markets daily doesn’t make you a better investor. Understanding the regime you’re in(inflation high or low, rates rising or falling, cycle expanding or contracting) fundamentally changes the reading of every decision, which requires knowing how to read macro-financial indicators.
The article Structuring Financial Decisions Over Time develops this approach.
The common denominator
Every mistake above has the same root: applying a rule without understanding the conditions under which it works. “Diversify” works, except when correlations break. “Invest regularly” works, except when real returns are zero for 13 years. The solution isn’t to abandon these rules; it’s to understand their conditionality. That’s what the Eco3min framework provides.
Frequently asked questions
Why is selling during a downturn so costly?
Because the sale turns an unrealized loss, which can recover, into a permanent one, and it almost always comes with missing the rebound: the best market days cluster during or right after the worst ones. In March 2020, the S&P 500 plunged in five weeks and recovered its level in about six months; whoever sold at the trough took the full decline without participating in the recovery.
Why can stocks and bonds fall together?
The negative correlation between the two (bonds rising when stocks crash) is not a law: it is a property of low-inflation regimes. When inflation becomes the central problem, as in 2022 or the 1970s, rising rates push bond prices and equity valuations down simultaneously. The correlation turns positive, and “60/40 diversification” stops cushioning exactly when it is needed. The trade-offs between allocation frameworks built for different regimes are compared in 60/40 vs. all-weather.
How long do market downturns last?
It depends entirely on their nature. Corrections of 10% or more have occurred about once a year on average since 1928 (Ned Davis Research) and often resolve within months. Bear markets tied to a one-off shock can be brief (2020: recovery in six months); those tied to a regime change stretch over years (2000–2013 and 1965–1982: more than a decade without real progress). The nature of the regime, not the initial depth of the fall, drives the duration.
What this path taught you
| Concept | What everyone says | What Eco3min adds |
|---|---|---|
| Method | DCA + long horizon | DCA compounds on real return, not nominal, and that depends on the regime |
| ETFs | Diversification + low fees | ETFs don’t protect against market risk, inflation, or index concentration |
| Accounts | IRA/Roth = less tax | Taxes hit nominal gains, including the portion that just compensates inflation |
| Amount | Invest what you can | Duration (exponential) beats amount (linear). Fees are the most powerful free lever |
| Real returns | The concept missing from 95% of guides. The only one that measures what your money can buy | |
| Inflation | It erodes savings | The urgency to invest depends on the real return of cash, which changes with the regime |
| Markets | Markets track the economy | Prices reprice expectations and financing conditions, which move ahead of current activity, and sometimes against it |
What’s next?
You have the foundations. The natural question is: how do you know which regime you’re in? That’s what the rest of Eco3min is about. Here, to start, is where the classification stands today, computed from public institutional data:
Current regime
Transition / mixed signals
Growth and underlying inflation are both classified neutral: none of the seven cyclical regimes applies, hence this transition label.
Growth
On trend
Underlying inflation
Stable
Financial conditions
Neutral
NoteUnderlying inflation stable (2.3%), but an energy shock is under way: Brent +92% year on year (Oct 2026). Headline inflation exceeds the persistent inflation the classification measures.
Three entry points depending on your interest:
Last updated — 25 September 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Regulated and tax values: the rates, indices, caps and brackets with legal effect cited on this page are set by official decision, change over time and apply according to individual circumstances. Only the official publication in force on the relevant date is authoritative (for example the Journal officiel, INSEE, Banque de France, the IRS or the Social Security Administration). To revise a rent, sign or challenge a contract, or file a return, check the value at the source or with a professional.
Read next
Full pillar →PEA vs. Taxable Brokerage Account: Which Should You Choose in France?
Educational content only. This does not constitute personalized tax or investment advice. Consult a licensed financial professional. Tax…
Real vs. Nominal Returns: The Most Important Distinction in Personal Finance
Disclosure: Independent educational content. Eco3min does not provide personalized investment advice. All investing involves risk of loss. A…
IRA, 401(k) & Roth vs. Taxable Brokerage: Which Account to Use
Disclosure: Independent educational content. Tax rules described are based on US federal tax law at time of writing…