
Behavioral Biases in Investing: Why Discipline Fails at the Worst Moment
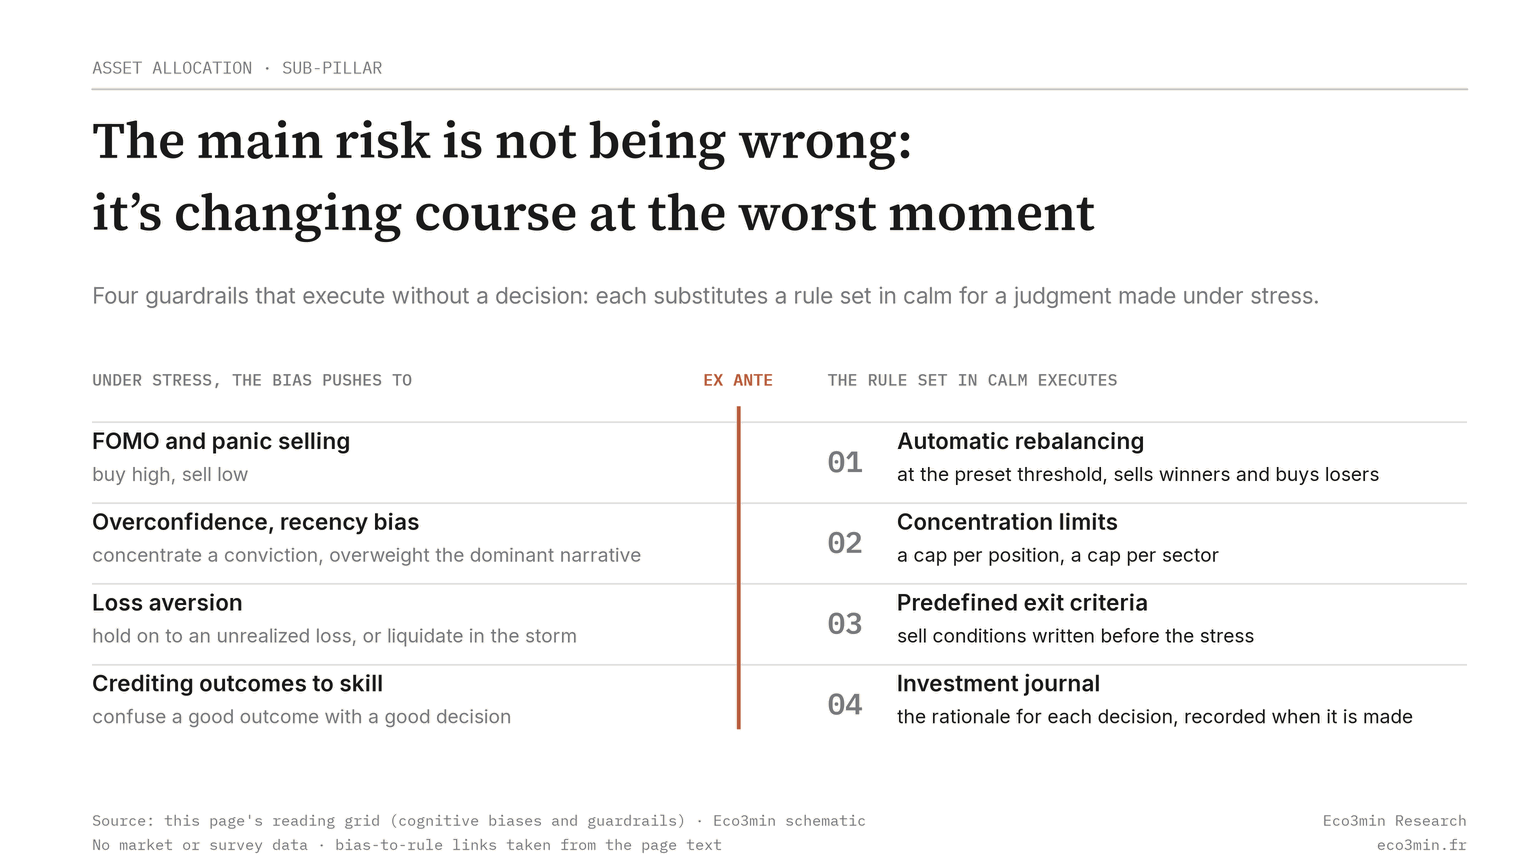
Eco3min schematic, no market data, based on this page’s reading grid · eco3min.fr
This page expands one facet of the pillar Investment Strategies. It formalizes the thesis that the main risk is not being wrong: it’s changing course at the worst moment. The sub-pillar Managing Risk addresses market risks (volatility, correlation, leverage, concentration); this one addresses internal risk: the cognitive biases that turn sound strategies into costly mistakes.
The main risk is not being wrong: it’s changing course at the worst moment. The most costly investment mistakes are not technical. They do not stem from flawed fundamental analysis or lack of information. They result from cognitive biases that push investors to abandon rationally built discipline at the exact moment it would be most useful. The data are unambiguous: the average investor underperforms the market by 1.5% per year (Dalbar QAIB, 2024), not due to incompetence, but inability to remain disciplined under emotional pressure. Equity fund outflows peaked in October 2022 (ICI): exactly at the S&P 500 bottom (October 13, 2022). Flows into tech/growth funds hit records in 2021 (ICI): precisely when valuations were most stretched and downside risk highest. Investors buy when enthusiasm peaks and sell when fear peaks: the exact inversion of allocation logic.
This sub-pillar does not claim to eliminate biases: they are part of human cognition and resist willpower. It formalizes the mechanisms through which each bias interacts with market regimes to produce specific mistakes, and the structural safeguards that limit their impact. Among those mechanisms, the partitioning of money into separate mental pots gives the way mental accounting reorders financial decisions its practical grip.
Recency bias: calibrating portfolios to a regime that no longer exists
Recency bias leads investors to extrapolate the recent regime as permanent, internalizing the properties of a specific period as universal laws. It is the most structurally destructive bias in the current regime because it sustains allocations calibrated to 2009–2021 in a world whose properties changed in 2022.
The reflexes the decade hard-wired
- Buy-the-dip always works (43 consecutive successes, Goldman Sachs)
- Bonds hedge crashes (negative correlation)
- Tech structurally outperforms (Nasdaq, Bloomberg)
- Low VIX means safety; cash is a drag
What the regime change invalidated
- Buy-the-dip failed (S&P −19%, no V-shaped recovery for several months)
- Bonds amplified losses (long Treasuries −31%, ICE BofA)
- Tech underperformed (Nasdaq −33%; far deeper losses for unprofitable tech)
- VIX reverted to ~20 (CBOE); cash became yield-bearing at 5.25% (T-bills, Fed)
Recency bias is especially dangerous after prolonged regimes: the properties of 2009–2021 were internalized through 12 years of continuous reinforcement. The longer a regime lasts, the more permanent its features appear, and the more violent the shock when it shifts. This mechanism is documented in the sub-pillar Allocation Foundations: implicit assumptions become invisible through repeated validation.
Survey data show the reflex at work: investors’ expectations of stock returns move with recent past returns and against the returns that models expect (Greenwood and Shleifer, Review of Financial Studies, 2014). Availability, since recent performance is the most visible, and confirmation bias amplify it. The same reflex shows up in fund selection. Choosing a fund or ETF mainly on its one- to three-year performance picks the products that benefited from the recent market regime rather than those that are structurally robust. Past performance is a descriptor, not a predictor. What would invalidate this reading is evidence that some managers deliver persistent outperformance, identifiable ex ante, across different market regimes. The SPIVA persistence scorecards of S&P Dow Jones Indices (mid-2025) find such persistence statistically marginal and difficult to distinguish from luck over the horizons observed.
The industry sends savers two messages at once. It uses past performance as a marketing tool while printing the regulatory warning that it is not indicative of future results, a line that is read and rarely internalised. The message of attraction wins over the message of caution.
FOMO: fear of missing out amplified by passive flows and index concentration
Fear Of Missing Out, anxiety about missing opportunities, is the strongest driver of buying at market tops. As assets rise, stories of easy gains multiply, social pressure intensifies, and investors who didn’t participate feel growing urgency to join: precisely when valuations are most stretched.
The current regime amplifies FOMO through two mechanisms. Passive management and ETF flows create a self-reinforcing loop: cap-weighted ETF inflows mechanically buy already overweight stocks, pushing prices higher, increasing index weights, attracting more passive flows. Index concentration (the Magnificent Seven weigh heavily in the S&P 500, S&P Global) means investors without those seven stocks visibly and painfully underperform. In 2023, investors holding the S&P 500 excluding the Magnificent Seven returned far less than the full index (Goldman Sachs), a visible gap creating massive psychological pressure to conform.
The technology narrative (generative AI since 2023, crypto in 2021, SPACs in 2020) fuels concentrated FOMO episodes. Nvidia’s share price multiplied several times between early 2023 and March 2024 (Nasdaq). Watching such gains without participating generates pressure comparable to historical bubbles, except tech narratives may have real fundamentals, making it far harder to distinguish structural trends from bubbles in real time.
Confusing recent performance with future potential. Late entrants in bull cycles buy at high prices without accumulated gains to cushion corrections. Reading the cycle phase early enough to avoid late-stage entries is the diagnostic challenge addressed in our sub-pillar on cycle analysis and portfolio regime positioning. Tech/growth fund flows peaked in 2021 (ICI): precisely when outperformance was about to reverse. FOMO structurally leads investors to buy dominant narratives when they are most expensive.
Panic selling: loss aversion amplified by leverage and liquidity
Loss aversion (losses hurt roughly twice as much as equivalent gains please, per Kahneman & Tversky, 1979) produces two opposite behaviors depending on context. Facing moderate unrealized losses, investors hold on, refusing to sell in hopes of recovery, locking capital in losing positions. Facing severe loss threats (crashes, volatility spikes), they panic sell, liquidating to “stop the bleeding,” converting temporary losses into permanent ones.
The current regime amplifies both behaviors. Leverage, more widespread after a decade of near-zero borrowing costs, turns moderate losses into intolerable ones, triggering forced selling. The VIX hit 65 in August 2024 during the yen carry trade unwind (CBOE), leveraged investors faced synchronized margin calls, forcing liquidations at the worst moment. Taken from the Cboe daily VIX history. Order book depth declined 50% in the E-mini S&P since 2019 (JPMorgan), meaning panic sales now move prices far more than in the prior decade. Selling in illiquid markets means selling far below last quoted prices.
The documented irony: equity fund outflows peaked in October 2022 (ICI), the exact S&P 500 bottom (Oct 13). Investors selling that day missed the rebound of the next two years. Loss aversion produced the very outcome it sought to avoid: permanent loss through capitulation at the trough. The article on the cost of strategy changes quantifies the damage from emotional abandonment.
Confirmation bias: thesis entrenchment
Confirmation bias drives investors to seek, interpret, and remember information that confirms preexisting beliefs while ignoring contradictory evidence. In investing, this cognitive filter can sustain mistaken convictions long after facts invalidate them.
Digital echo chambers amplify confirmation bias with unprecedented efficiency. Social media algorithms surface content aligned with expressed preferences: tech bulls mostly see tech-bull analyses. Online communities (FinTwit, Reddit r/wallstreetbets, crypto Telegram groups) reinforce shared convictions without exposure to dissenting views. The effect is measurable: retail investors active on online investment forums display stronger confirmation bias and higher portfolio turnover than non-participants (Barber & Odean, 2008). The beliefs that circulate hardest there are dismantled in the big misconceptions about money and markets.
Confirmation bias interacts with regimes specifically. During prolonged bull markets (2009–2021), bias reinforced dominant theses (“stocks always rise long term”), and markets validated that conviction for 12 years. The confrontation with regime change in 2022 was harsher because convictions had been reinforced for a decade. Mitigating confirmation bias requires deliberate search for opposing arguments, illustrated in the article on consequences of a good idea without strategy.
Overconfidence: the product of prolonged bull markets
Overconfidence (overestimating analytical skill, underestimating uncertainty, attributing success to skill and failure to bad luck) is the most pernicious bias because it reinforces itself through success. A streak of gains convinces investors they discovered superior methods, even when gains result from fortunate alignment with favorable regimes.
The 2009–2021 regime produced widespread overconfidence. The S&P 500 delivered an exceptional return between 2010 and 2021 (S&P Global). The Nasdaq outperformed even more. Investors holding tech ETFs since 2015 quadrupled capital: naturally attributing results to skill rather than zero-rate regimes compressing discount rates and mechanically inflating growth valuations. Overconfidence leads to three destructive behaviors: excessive concentration (“tech will keep winning”), rising leverage (“borrow to buy more”), and high trading frequency (“I can time corrections”). Empirical studies show negative correlation between trading frequency and net performance: costs, taxes, and timing errors erode returns (Barber & Odean, 2000). The same authors later split that sample by gender, which is where differences in investing behaviour between men and women first became measurable.
The test of overconfidence is regime change. Truly skilled investors distinguish what stems from competence (process, discipline, allocation) versus regime (correlations, liquidity, rates). Overconfident investors attribute everything to the former, and discover the difference at the next inflection.
Anchoring: the purchase price trap
Anchoring leads investors to evaluate assets relative to arbitrary reference points, typically purchase prices, rather than current fundamentals. Investors who bought at €100 refuse to sell at €80 “to avoid realizing losses,” even if fundamentals justify €60. Conversely, they sell at €120 “to lock gains,” even if fair value is €150. Anchoring turns positions into emotional bets on returning to entry price, detached from fundamental analysis.
Markets have no memory of individual purchase prices. The only relevant question is: “If I didn’t own this position, would I buy it at today’s price?” If not, holding it equals buying it: anchoring’s opportunity cost. For the broader picture: the limits of a record price as a signal.
Guardrails: ex-ante rules for imperfect brains
Knowing biases is insufficient to neutralize them: cognitive psychology has shown this since Kahneman and Tversky. Investors aware of loss aversion still panic sell beyond psychological tolerance. Investors aware of FOMO still buy tech peaks under social pressure. The solution is not knowledge: it is ex-ante rules executed mechanically regardless of emotional state.
Four guardrails that execute without a decision
Each substitutes a rule set in calm for a judgment made under stress: it is their automatic execution that makes them work, not the investor’s willpower.
Automatic rebalancing
A predefined rebalancing threshold mechanically enforces selling winners and buying losers, countering both FOMO and panic selling. It converts a destructive bias (buy high, sell low) into constructive discipline.
Concentration limits
A per-position cap prevents overconfidence from turning conviction into fatal concentration; a per-sector cap prevents recency bias from overweighting the dominant narrative.
Predefined exit criteria
Defining sell conditions ex ante (deteriorating fundamentals, a broken technical threshold, a changed thesis) removes emotional choice during stress. The decision is made in calm and executes in the storm.
Investment journal
Recording the rationale for each decision creates an objective record that separates good decisions from good outcomes and reveals the patterns where biases emerge most strongly.
Investment discipline →The main risk is not being wrong: it’s changing course at the worst moment. The average investor underperforms markets by 1.5% annually (Dalbar QAIB) not through incompetence but emotional discipline failure. Each bias interacts with market regimes to produce specific mistakes: recency bias sustains allocations built for 2009–2021 in changed conditions; FOMO is amplified by passive flows and index concentration; panic selling is intensified by leverage and market illiquidity; overconfidence is the product of 12 bull market years. Bias awareness is insufficient: only structural guardrails (automatic rebalancing, concentration limits, predefined exits, investment journals) replace emotional judgment with mechanical discipline. The most valuable investment rules are those that execute automatically: discipline is built in calm and deployed in storms. Companion analysis: the false assumptions investors make about investor behavior.
Further reading
Investment discipline: when consistency creates performance, Showing discipline outperforms talent over full cycles.
A good idea without strategy: How confirmation bias turns sound intuition into costly error.
The cost of changing strategy: The price of emotionally abandoning allocations.
← Back to Investment Strategies
Last updated — 29 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Portfolio Risk Management: Survival First, Performance Second
For every drawdown incurred, the gain required to break even follows |DD| / (1 − |DD|): −25% requires…
Reading the Economic Cycle: Aligning Portfolio Exposure with Market Regimes
Calendar-year total returns in 2008 and 2022: US stocks −37% and 20-year Treasury +27% in the 2008 demand…
Portfolio Allocation Architectures: Regime Assumptions, Fragilities, and Structural Risks
Rolling 24-month correlation between the monthly total returns of US stocks (S&P Composite, Robert J. Shiller) and of…