
Bitcoin vs gold: store of value compared
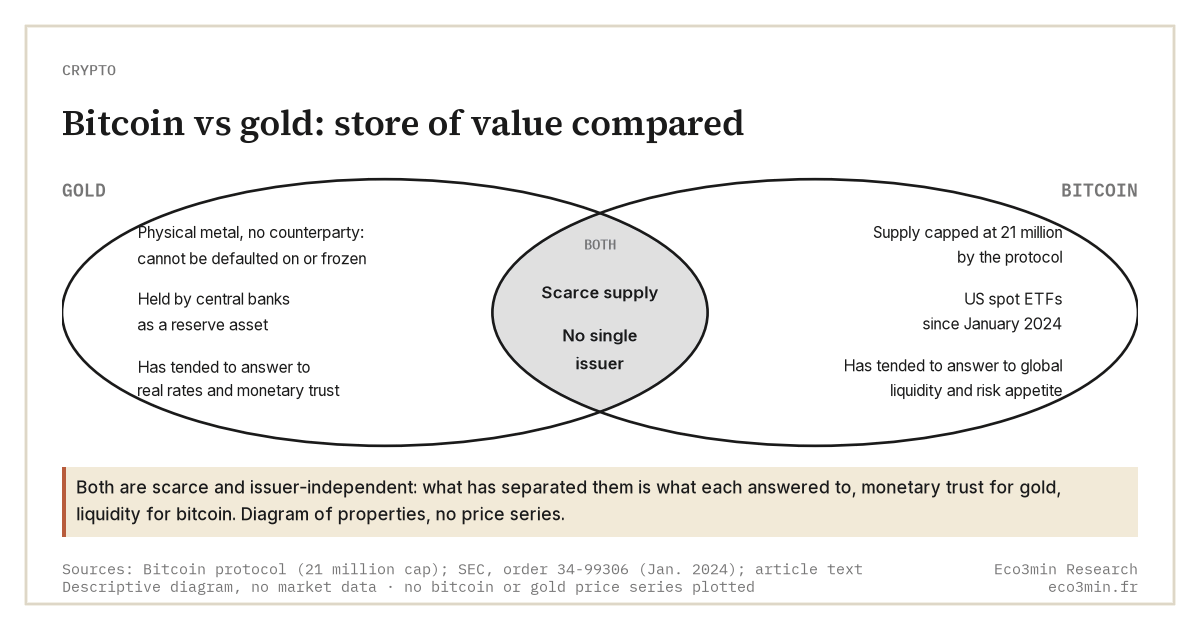
Bitcoin and gold are both framed as scarce “hard money,” but they have not behaved the same way. Gold carries roughly a third of Bitcoin’s volatility, holds a low-to-negative correlation with equities, and is accumulated by central banks as a reserve with no counterparty risk. Bitcoin, since 2020, has traded increasingly like a high-beta risk asset that moves with the Nasdaq, not against it. The real difference is less about scarcity than about what each one correlates with.
In this comparison
Why this comparison matters
“Digital gold” became shorthand for Bitcoin almost from inception, and the parallel is intuitive: both have a capped or slowly growing supply, and neither depends on a single issuer. The label matters because it implies the two assets play the same portfolio role: a holding that protects when everything else falls. The record of the past five years complicates that picture. Gold has behaved as a monetary-instability hedge; Bitcoin has behaved more like a leveraged claim on global liquidity.
What Bitcoin is
Bitcoin is a decentralized digital asset launched in 2009, with a supply algorithmically capped at 21 million coins. Its scarcity is now extreme: by April 2024 its stock-to-flow ratio had surpassed gold’s among liquid assets. That stock-to-flow jump is a direct product of the programmed halving and bitcoin issuance. The launch of US spot Bitcoin ETFs in January 2024 pulled it into mainstream allocation, yet it remains highly volatile: according to CME Group, annualized realized volatility stood near 52% at the end of Q1 2025, and its daily standard deviation ran several times that of the S&P 500.
What gold is
Gold is a physical monetary metal with several thousand years of use as a store of value. It carries no counterparty: it cannot be defaulted on, printed, or frozen, which is precisely why central banks hold it, having been net buyers year after year for more than a decade (→ why central banks keep accumulating gold). They added more than 1,000 tonnes a year from 2022 to 2024, according to the World Gold Council. Its annualized volatility is only a fraction of Bitcoin’s.
→ Complete explanation: Why is gold a hedge against monetary instability, not inflation?
The key differences
Mechanism. Gold’s value rests on physical scarcity and a multi-millennial Schelling point; Bitcoin’s rests on a fixed digital supply schedule and network security. Both are issuer-independent, but gold’s monetary role is settled while Bitcoin’s is still being priced by the market. That difference in maturity, more than scarcity, shapes how each one trades.
Volatility and correlation. This is where the “digital gold” framing breaks. Gold’s correlation with equities is low to negative in stress, whereas Bitcoin’s correlation with the Nasdaq-100 averaged 0.52 in 2025, more than double its 2024 level (LSEG data). Before 2020 that correlation sat near zero; institutional adoption and the 2024 ETFs pulled Bitcoin into the same liquidity pool as equities (→ how Bitcoin correlates with traditional risk assets).
Behavior across the cycle. Gold has tended to bid when real rates fall and monetary trust erodes; Bitcoin has tended to rise when liquidity is abundant and risk appetite is high, and to fall hard when it is not. The asymmetry is consistent across the last two cycles.
How they behave across regimes
The two assets answer to different switches. In abundant-liquidity, risk-on phases such as 2020-2021, Bitcoin has tended to outrun gold, amplifying the same forces that lift the Nasdaq. In monetary-stress episodes (the 2022 reserve freezes that accelerated central-bank gold buying, or sharp risk-off drawdowns) gold has held while Bitcoin often sold off alongside equities. A 2025 study using DCC-GARCH models found that after the January 2024 ETF launch, Bitcoin’s correlation with the S&P 500 rose significantly while its relationship with gold stabilized near zero. The deciding parameter has been the state of global liquidity and risk appetite, not inflation alone. A related perspective: the trade-offs across bitcoin access methods.
Both are scarce; only one of them, so far, has traded like a safe haven.
→ Framework: Crypto-assets: liquidity, cycles and real rates
The common confusion
The frequent error is to treat Bitcoin as a drop-in substitute for gold in a portfolio’s defensive sleeve. The “digital gold” label captures a real similarity (capped supply, no issuer), but conflates monetary properties with market behavior. An asset can be scarce and still trade as high-beta risk. Over the past five years Bitcoin has more often amplified equity moves than offset them, which is the opposite of what a defensive holding is expected to do. Closer to gold in substance, silver and platinum as investment metals still carry an industrial component that ties part of their price to the economic cycle.
Practical observation
What the data suggests for framing your own analysis:
- Question to ask yourself: in the scenario I am concerned about, is the threat a liquidity contraction or a loss of monetary trust? Historically the two assets have answered to different ones.
- Data to monitor: Bitcoin’s rolling correlation with the Nasdaq-100 and S&P 500; gold’s correlation with real rates and the dollar.
- Historical parallel: in 2022, gold ended roughly flat while most assets fell with rising rates, whereas Bitcoin declined alongside the Nasdaq.
- What the literature documents: DCC-GARCH studies after the 2024 ETF launch record a rising Bitcoin–equity correlation and a near-zero Bitcoin–gold relationship.
This is descriptive information to help you frame your own analysis. Eco3min does not provide investment advice.
Go deeper
📊 Structural read: Bitcoin as a monetary asset: liquidity cycles and real rates
📁 Dataset: US net liquidity index (Fed, TGA, RRP)
Related guides
Frequently asked questions
How is Bitcoin different from gold as a store of value?
Both have a capped or slowly growing supply and no single issuer, which is the source of the “digital gold” parallel. The difference shows up in behavior: gold has carried a fraction of Bitcoin’s annualized volatility, which ran near 52%, along with a low correlation with equities. Bitcoin’s correlation with the Nasdaq rose to about 0.52 in 2025. Gold’s monetary role is settled and central banks hold it as a reserve; Bitcoin’s role is still being priced by the market. Pricing that role happens against a monetary backdrop, which is why the behaviour of crypto assets under different monetary regimes is where the answer gets decided.
When has Bitcoin moved with stocks rather than with gold?
Before 2020, Bitcoin’s correlation with equities sat near zero, which fed its “uncorrelated” reputation. That changed as institutional adoption grew and the US spot ETFs launched in January 2024: a 2025 DCC-GARCH study found Bitcoin’s correlation with the S&P 500 rose significantly post-ETF while its link to gold stabilized near zero. In practice, Bitcoin has tended to rally with the Nasdaq in risk-on phases and to fall with it when risk appetite contracts, behaving as a liquidity-sensitive risk asset rather than a safe haven.
Why do central banks hold gold but not Bitcoin?
Gold has no counterparty and cannot be frozen, which became salient after reserve freezes in 2022. Central banks bought more than 1,000 tonnes a year from 2022 to 2024, according to the World Gold Council. Bitcoin’s volatility, shorter track record, and custody and regulatory considerations have so far kept it outside official reserve frameworks, although that describes current practice, not a forecast. For other questions framed the same way, see the rest of our paired breakdowns.
Last updated — 3 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →LEI vs PMI: comparing leading indicators
The LEI is a single composite of ten forward-looking series published monthly by The Conference Board; a PMI…
Stablecoins vs CBDCs: private vs public digital money
A stablecoin is privately issued digital money pegged to a fiat currency, mostly the dollar, and backed by…
Proof-of-work vs proof-of-stake: the economics
Proof-of-work secures a blockchain by burning external energy; proof-of-stake secures it by locking internal capital. The real difference…