
Hidden Unemployment: What Labor Slack Says Beyond the Jobless Rate
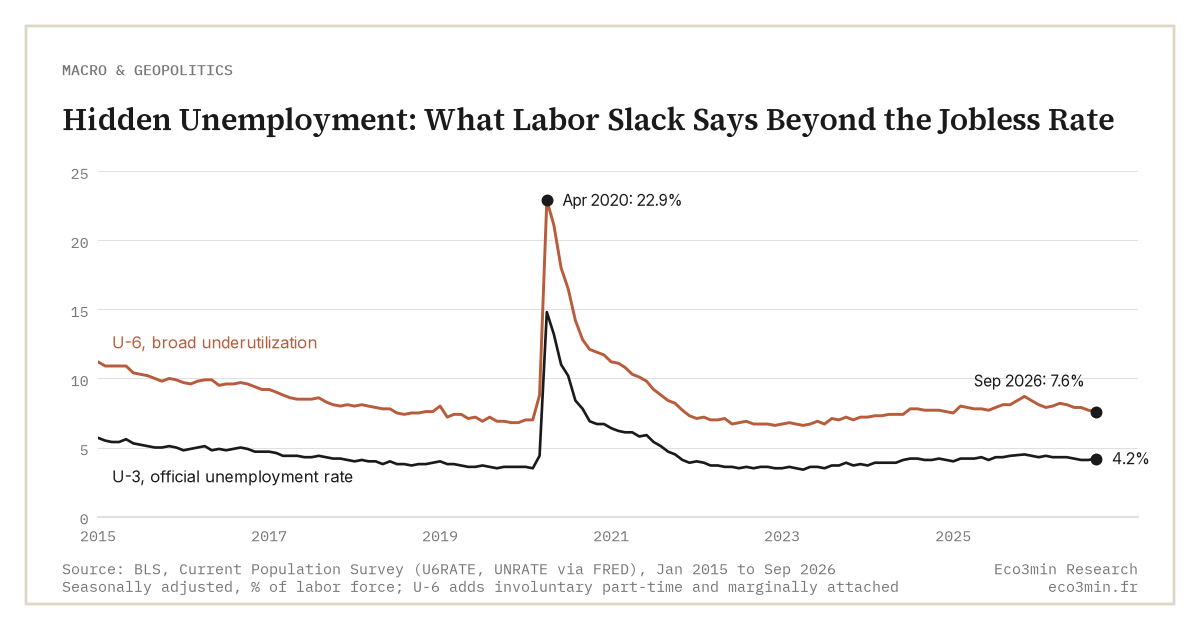
The gap between US broad and official unemployment, 3.4 points in September 2026, is practically where it stood in 2019: there is no hidden pool of idle labor.

The official unemployment rate counts only people without a job who are looking for one and can take it. The broader U-6 measure adds involuntary part-time work and people loosely attached to the labor market, and it is the better gauge of the slack employers could actually draw on.
In the US, that slack is no larger than in 2019, and in the euro area it is smaller. The idea of hidden unemployment building up behind low headline rates does not survive the data.
TL;DR
The gap between US broad and official unemployment, 3.4 points in September 2026, is practically where it stood in 2019: there is no hidden pool of idle labor.
- U-6 was 7.6% in September 2026 against a 7.2% average in 2019, with official unemployment at 4.2% against 3.7% (BLS).
- Overall participation, at 61.8%, is below 2019; prime-age participation, at 83.7%, is above it.
- In the euro area, broad underemployment fell from 15.0% at end-2019 to 12.7% in the second quarter of 2026 (Eurostat).
What the jobless rate leaves out
The official US unemployment rate, U-3, counts people who did not work, were available and looked for a job in the past four weeks. Someone who would like more hours, or who has stopped looking while still wanting work, is not in it. The Bureau of Labor Statistics therefore publishes a set of alternative measures from the Current Population Survey. The broadest, U-6, adds people working part-time for economic reasons and those marginally attached to the labor force, including discouraged workers (series U6RATE).
The common reading treats the gap between U-6 and U-3 as hidden unemployment that widens when the economy weakens. It can widen, and it did in 2020, when U-6 reached 22.9% in April. That is not what it is doing in 2026.
A gap back at its 2019 level
In September 2026, U-6 stood at 7.6% and U-3 at 4.2%. In 2019, before the pandemic, they averaged 7.2% and 3.7%. Both measures are slightly higher, but the gap between them, 3.4 points, is practically the 2019 gap of 3.5 points. The pool of involuntary part-timers and marginally attached workers has not grown faster than unemployment itself.
Hidden slack is moving with visible slack.
U-6 has nonetheless drifted up from its post-pandemic low of 6.6% in December 2022, and U-3 from 3.4% in April 2023. The labor market has loosened since then, in the open, through the official rate, rather than through a hidden reserve. How those monthly figures change once revised is covered in the revised US jobs figures for January 2024 to June 2026.
Participation: an age effect
The labor force participation rate looks like evidence of hidden unemployment: 61.8% in September 2026, against a 2019 average of 63.1%. Its decline, however, reflects who makes up the population more than people dropping out. Prime-age participation, for 25 to 54-year-olds, stood at 83.7% in September 2026, above its 2019 average of 82.5%. Fewer working-age adults are outside the labor force than before the pandemic. The overall rate falls because a larger share of the population is past usual retirement age.
A second signal points the same way. The share of workers holding more than one job, 5.5% in September 2026 against 5.1% in 2019 (series LNS12026620), has edged up without spiking. A surge in multiple jobholding would suggest workers short of hours or income in their main job; the series does not show one. Long-run participation data are in the US labor force participation series.
Reading the fall in overall participation since 2019 as workers hiding outside the labor market. Prime-age participation is higher than in 2019, at 83.7% against 82.5%: the decline in the overall rate comes from an older population.
The euro area comparison
Eurostat publishes a comparable broad measure, labour market slack, which adds underemployed part-timers and people available but not seeking to the unemployed, as a share of the extended labor force (series lfsi_sla_q). For the euro area it fell from 15.0% in the fourth quarter of 2019 to 12.7% in the second quarter of 2026, with unemployment down from 7.1% to 6.2% and involuntary part-time from 3.3% to 2.7%. The European reserve is thus smaller than before the pandemic, a stronger result than the stable US gap.
What would bring slack back
A slowdown in which employers cut hours before headcount would first push up involuntary part-time work, then unemployment. The indicator to watch is the part-time-for-economic-reasons component of U-6, published each month with the jobs report: it captures adjustment through hours, which firms often use before touching staff numbers. A widening of the U-6 to U-3 gap beyond its 2019 level would be the first sign that slack is building where the headline rate does not show it. Our U-6 unemployment rate dataset carries the full series, and the Beveridge curve data show how job openings and unemployment move together.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →How U.S. jobs data changes after revisions, January 2024 to June 2026
TL;DR Between January 2024 and June 2026, 26 of the 30 monthly U.S. payroll figures were revised down…
Why Financial Signals and the Real Economy Diverge Persistently
Equity markets near record highs while industrial production stagnates: this configuration recurs whenever the financial sphere operates with…
T10YIE vs TIPS Yield: Decomposing Real Yield and Inflation Expectations
The nominal 10-year Treasury yield is not an indivisible number: it decomposes into the TIPS real yield and…