
Housing Inflation: Why Shelter Weighs Six Times More in the US CPI
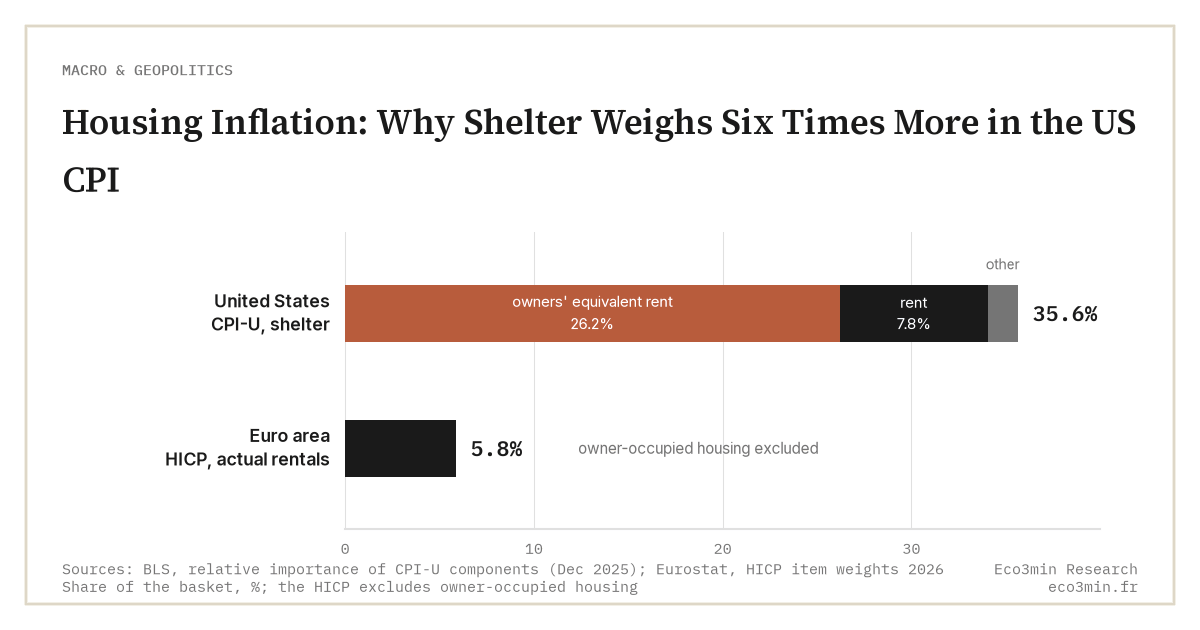
Shelter is 35.6% of the US CPI against 5.85% for rents in the euro area HICP: a sixfold weight that comes mostly from the rent imputed to homeowners.

Housing makes up more than a third of the US consumer price index and less than 6% of the euro area’s. That difference in measurement, more than any difference in markets, explains why housing dominated the US inflation debate and barely featured in Europe’s.
The two indexes do not count the same thing: the US one imputes a rent to homeowners, the European one leaves it out. Since spring 2026, housing has been rising more slowly than overall inflation on both sides of the Atlantic.
TL;DR
Shelter is 35.6% of the US CPI against 5.85% for rents in the euro area HICP: a sixfold weight that comes mostly from the rent imputed to homeowners.
- US shelter inflation fell from 8.2% in March 2023 to 3.4% in August 2026 (BLS).
- In August 2026 it ran 0.28 point below headline CPI, while euro area rents ran 0.6 point below headline HICP (Eurostat).
- Owners’ equivalent rent alone weighs 26.2% of the CPI-U, more than four times all euro area rents in the HICP.
Two indexes, two definitions of housing
According to the Bureau of Labor Statistics relative importance table, shelter accounted for 35.625% of the US consumer price index (CPI-U) in December 2025. Most of it is not rent actually paid. Owners’ equivalent rent, an estimate of what homeowners would pay to rent their own home, weighs 26.204%. Rent of primary residence, paid by tenants, weighs 7.840%.
The euro area’s harmonized index (HICP) works differently. Eurostat has excluded owner-occupied housing since the index began, treating it as an investment rather than consumption. Only actual rentals remain, at 58.49 per thousand in 2026, or 5.85%, according to the HICP item weights. Housing in the broad sense, including water and household energy, reaches 14.6%.
One word, two realities.
The usual reading attributes the persistence of US inflation in 2023-2024 to a tighter housing market than Europe’s. Part of the gap, though, comes from how the indexes are built: the same pace of rent increases weighs six times more in the US index than in the European one.
Slow disinflation in the US
US shelter inflation peaked at 8.2% year over year in March 2023, according to the CUSR0000SAH1 series. It came down slowly: 5.6% in March 2024, 4.0% in March 2025, 3.4% in August 2026. In August 2026, owners’ equivalent rent was rising 3.4% and rent of primary residence 3.0%.
That slowness is built into the method. The index tracks rents on units already leased, many of which have not changed hands in months, rather than only the rents on new leases. A turn in market rents therefore feeds into the index only as leases renew.
A gap that turned negative in both regions
Throughout 2023-2025, US shelter rose faster than headline inflation. The gap was +3.3 points in March 2023 and still +0.6 point in February 2026. It flipped in March 2026 and stood at −0.28 point in August. Euro area rents followed the same path: 1.3 points above headline HICP in January 2026, 0.6 point below it in August, at 2.6% against 3.2%.
Housing did not suddenly give way. Headline inflation rose instead, driven by energy after the effective closure of the Strait of Hormuz in late February 2026, while housing kept easing slowly. The negative gap therefore signals a change in inflation’s engine more than a housing slowdown.
Comparing US and European housing inflation directly. The CPI includes owners’ equivalent rent, 26.2% of the basket, while the HICP excludes it: the same pace of rents weighs six times more in the US.
What to watch
The indicator to watch is the gap between housing and headline inflation in each region, published monthly by the BLS and Eurostat. It would turn positive again if energy prices eased faster than rents. A second signal is the ratio of owners’ equivalent rent to tenants’ rent in the US: OER has risen faster than rent since early 2025, at 3.4% against 3.0% in August 2026, which keeps the largest component of the CPI the stickiest. The link between real rates and home prices is covered in the long history of real interest rates, and the reading framework for inflation in the Eco3min inflation framework.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Inflation Explained: Mechanisms, Measurement, History and Effects — The Complete Guide
Definitions, the four official measures, stacked causes, a century of documented episodes and effects on debtors, savers and…
US–China Semiconductor War: The Real 2026 Battlefield
Late-2025 US restrictions still target ≈40% of China's advanced AI compute capacity, while Beijing tightens critical-mineral exports. The…
Hidden Unemployment: What Labor Slack Says Beyond the Jobless Rate
The gap between US broad and official unemployment, 3.4 points in September 2026, is practically where it stood…