
Output Gap: Why Closing the Gap Doesn’t Always Mean a Stronger Economy
The output gap between actual and potential GDP structures the cycle's adjustments — but potential itself moves. A closing gap can signal accelerating activity or, just as easily, a downward revision of potential. The distinction matters for monetary and fiscal policy calibration.

The gap between potential growth and observed growth often reveals invisible tensions in the economy. When activity rises above or stays below its true capacity, those imbalances shape the cycle’s adjustments — through prices, employment, and investment.
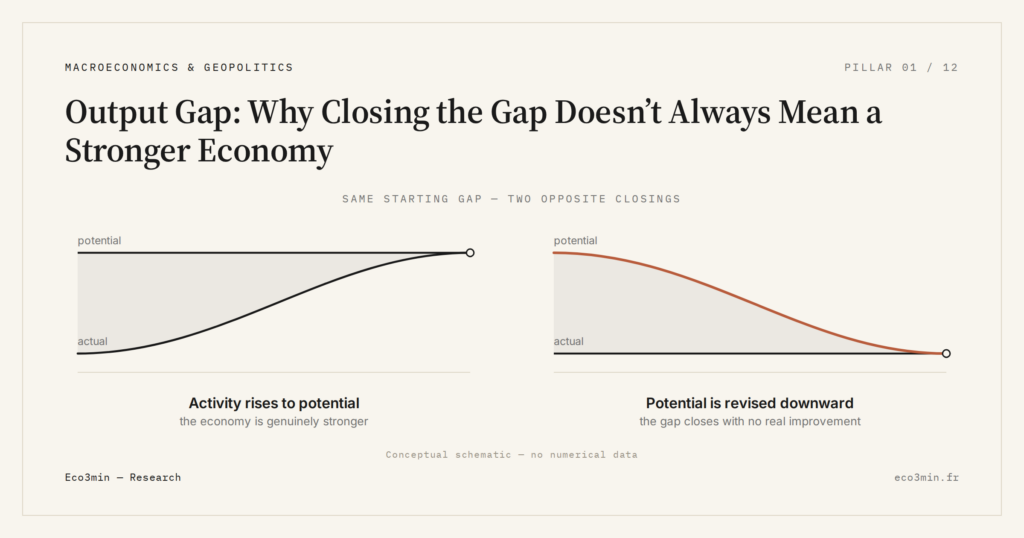
The output gap, the difference between actual and potential GDP, structures the tensions of the economic cycle and sheds light on its longer adjustments. The trickier part is that potential itself moves.
TL;DR
The output gap can close through shrinking capacity rather than stronger activity: the CBO projects US potential growth at 2.7% in 2024, 2.2% in 2026 and 1.8% in 2035.
- For 2025, the OECD (Economic Outlook, June 2026) puts the output gap at -0.6% of potential GDP in the euro area and -0.1% in the United States; the CBO, with its own US potential, gets +1.4%.
- The OECD does not project a closing euro-area gap: -0.6% in 2025, -0.8% in 2026 and 2027.
- For the same economy and year, the OECD and the CBO differ by 1.5 points: uncertainty about potential is enough to flip the sign of the gap.
Observed growth gets attention because it is measurable and immediate. Potential growth, more abstract, nevertheless structures the cycle. The gap between the two reveals either room for catch-up or a deeper constraint on productive capacity, and it conditions adjustments in investment and employment. Ignoring this distinction amounts to reading the cycle without its long-term anchor, conflating cyclical variation with structural constraint.
What changes without making noise is the estimate of potential itself. Estimates of potential change from one edition to the next and from one institution to another, a subtle drift that materially changes how the cycle is read, without ever making headlines.
The output gap refers to the difference between actual GDP and potential GDP — the level of production an economy can sustain without generating lasting inflationary pressures. A negative gap means the economy is producing below capacity: resources sit idle, which weighs on prices and investment. A positive gap means the economy is running hot, and cost pressures intensify.
In its June 2026 Economic Outlook, the OECD estimates the 2025 output gap at -0.6% of potential GDP in the euro area and -0.1% in the United States. The Congressional Budget Office, which computes its own US potential GDP, instead puts the US economy above capacity, at +1.4% in 2025 (series GDPC1 and GDPPOT). The very sign of the gap depends on the estimator, which also blurs any reading of why the ECB and the Federal Reserve are not operating on the same monetary timetable. Productivity and its role in the economic cycle is the decisive variable here: it determines the level of potential, and therefore the size of the gap.
A potential that is not fixed
The most common mistake is to treat potential growth as a constant. In practice it evolves with the capital stock, the active population, and productivity gains. The CBO projects US potential growth declining from 2.7% in 2024 to 2.2% in 2026 and 1.8% in 2035; the OECD puts euro-area potential growth at 1.05% in 2026, after 1.1% to 1.5% a year over 2023-2025. The implication is uncomfortable: the output gap may close not because the economy accelerates, but because potential itself falls, a phenomenon the real-cycle analytical framework identifies as a major signal.
The consequences are direct for the investment cycle in the economy. If potential drops, firms adjust their capacity plans downward, which reduces net investment flows and compresses future productivity. This self-reinforcing mechanism (less potential leads to less investment, which further reduces potential) is one of the most discreet but powerful drivers of the long-term cycle. It also means that policy interventions calibrated on a stale estimate of potential systematically misfire.
- The output gap structures the cycle by showing whether the economy is producing above or below capacity — information GDP alone does not provide.
- Potential growth is not fixed: a downward revision can create the illusion of a closing gap without any real improvement in activity.
- Any economic policy calibrated on the output gap inherits the uncertainty around the underlying estimate of potential.
Consequences for fiscal and monetary policy
The output gap directly conditions the calibration of fiscal policy across the economic cycle. A negative gap calls for fiscal support; a positive gap calls for consolidation. But if the estimate of potential is biased (which is common, with revisions sometimes larger than the gap itself) policy responds to the wrong signal. The risk is mechanical: persistent pro-cyclicality.
The OECD does not project a closing of the euro-area output gap: it would move from -0.6% in 2025 to -0.8% in 2026 and 2027 (June 2026). A closing, if it came, could reflect a downward adjustment of potential rather than an acceleration of activity. The 1.5-point gap between the OECD and the CBO on the US economy shows that the same uncertainty weighs on judging how restrictive monetary policy needs to be. The structural fundamentals of the cycle remind us that these estimates are constructions, not direct observations, and that policy treating them as observations imports an error of category.
A positive technology shock (faster AI adoption in production processes, for example) could raise potential growth and reopen the output gap on the upside. The scenario is mentioned in several recent institutional reports, but it remains conditional: productivity gains tied to AI do not spread at the same pace across sectors and geographies, and their materialisation is likely to take several cycles. A closing driven by lower potential and a closing that would actually signal a stronger economy are not the same closing.
Last updated — 6 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →The Real Economic Cycle: Investment, Productivity and the Hidden Drivers of Growth
Ahead of each of the six US recessions since 1980, investment growth peaked 4 to 12 quarters in…
US–China Semiconductor War: The Real 2026 Battlefield
Late-2025 US restrictions still target ≈40% of China's advanced AI compute capacity, while Beijing tightens critical-mineral exports. The…
Hidden Unemployment: What Labor Slack Says Beyond the Jobless Rate
The gap between US broad and official unemployment, 3.4 points in September 2026, is practically where it stood…