
Why Property Markets Remain Cyclical Despite Public Policy
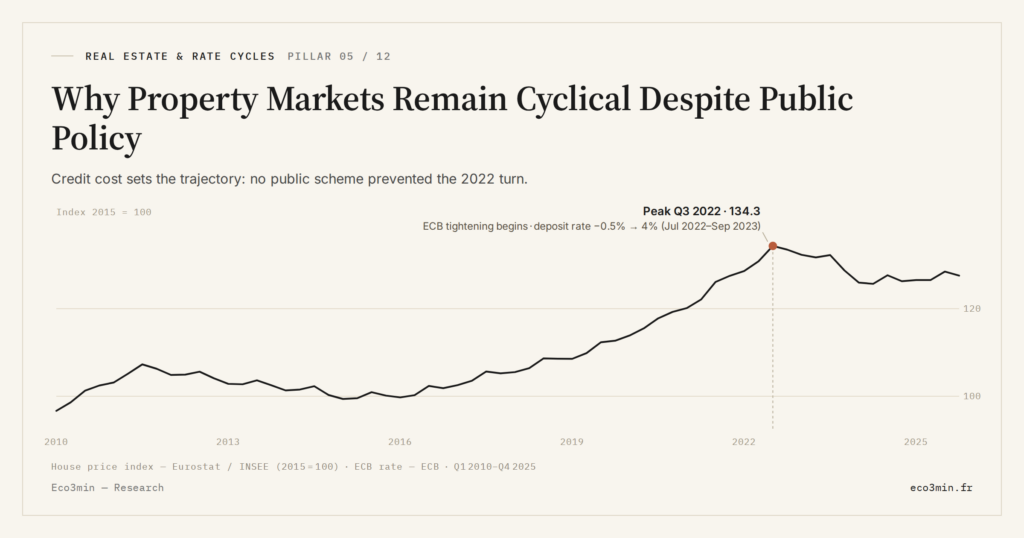
French house prices peaked in the third quarter of 2022 and stood 6.5% lower in mid-2026, despite tax schemes, rent caps and credit rules: the price of credit set the path, and policy lags often amplified it.

Housing policy acts through tax breaks, rent rules and lending standards that take years to design and apply. The price of credit moves far faster, so the cycle usually turns before the measures meant to steady it reach buyers.
France, whose housing market carries a dense set of public tools, shows how far that toolkit reaches, and where the credit cycle overrides it.
TL;DR
French house prices turned in 2022 despite a dense set of public schemes: the price of credit set the trajectory, and policy timing often amplified it.
- Eurostat’s French house price index peaked at 134.3 (2015 = 100) in the third quarter of 2022 and stood 6.5% lower in the second quarter of 2026, after the ECB lifted its deposit rate from −0.5% to 4% between July 2022 and September 2023.
- A 2% annual tax reduction under the Pinel scheme weighs little against a 200 basis point move in mortgage rates, which raises the monthly payment on a 20-year loan by about 20%.
- Dwellings authorised in metropolitan France fell from 469,900 in 2022 to 308,400 in 2024 (Insee), and the 2025 rebound to 359,900 left them 23% below their 2022 level.
French housing comes with a thick rulebook: dedicated tax incentives, state-backed loans for low-income buyers, rent caps in large cities, energy standards and binding limits on mortgage underwriting. None of it prevented the turn of 2022. Eurostat’s house price index for France reached 134.3 in the third quarter of 2022, with 2015 as the base year, then fell 6.5% by the second quarter of 2026, its latest release. Over the same window the European Central Bank took its deposit facility rate from −0.5% in July 2022 to 4% in September 2023.
Nor was 2022 the first reversal. Between 2011 and 2015 the French index lost 7%, and Spain’s fell 30% between 2010 and 2014, both on Eurostat data. The common reading is that a state with this many levers can smooth the housing cycle, or at least cushion its troughs. The French record supports a narrower claim. Policy acts on the symptoms of the cycle, such as prices, affordability and vacancy, while its drivers (the cost of credit, demographics, land and expectations) sit largely outside its reach. Its timing can even reinforce the phase it set out to correct.
Policy works on legislative time, credit on central-bank time
A housing measure passes through several filters before it changes behaviour: diagnosis, parliamentary debate, a vote, implementing decrees, take-up by banks, developers and households, and only then an effect on prices. The gap between recognising a problem and measuring a result runs to years. A central bank moves its policy rate at a scheduled meeting, and mortgage pricing follows within months.
Policy arrives in years. Credit reprices in weeks.
That difference in speed decides where a measure lands in the cycle. When a government announces support for first-time buyers after sales have collapsed, markets are often already pricing easier credit, and the recovery is under way before the scheme reaches its public. A tool calibrated at the bottom then delivers its full effect on the way up, feeding the next upswing rather than cushioning the trough it targeted. How monetary policy feeds through mortgage credit into prices sets that sequence, and the legislative calendar adds its own delay on top. The lag is built into lawmaking, so counter-cyclical housing policy tends to come late.
Tax incentives: a small lever beside the price of credit
France has run a long series of tax schemes for buy-to-let investors and first-time buyers. Among them, the Pinel scheme offered a tax reduction worth 2% of the purchase price per year over its first nine years; it closed to new investments on 31 December 2024, according to the government’s public service portal. Its renovation-focused sibling, Denormandie, remains open until the end of 2027, and the zero-rate PTZ loan still supports first-time buyers.
Set that 2% against the cost of borrowing. On a 20-year loan, a 200 basis point rise in the mortgage rate lifts the monthly payment by about 20% for any starting rate between 1% and 3% (calculation by Eco3min, constant term). Borrowing capacity follows that payment.
The asymmetry produces a pro-cyclical bias. When credit is cheap, tax breaks stack on top of already high borrowing capacity and help push prices up. When credit tightens, they absorb only a fraction of the shock and cannot rescue projects that no longer pay. The same ordering shows up in why rate hikes do not always lower prices: adjustment runs through financing capacity and volumes first, prices and rents later, and a fiscal incentive sits downstream of a channel it does not control.
Rent caps and building targets: where the effect leaks
Paris has capped rents on new leases since 1 July 2019, under the ELAN housing law of November 2018, and several other French cities have followed. The city’s own guidance lists what falls outside the cap: social housing, leases under the 1948 law, serviced residences and short-term holiday lets. That exemption gives owners a way around the rule. What a cap gains on the observed rent path it can lose on the number of homes offered for long-term letting, on maintenance that can no longer be priced in, and on the quality of matches between tenants and homes.
On the supply side, support for construction runs into frictions no budget line removes quickly: scarce buildable land in high-demand areas, longer permitting, and building costs tied to materials and energy prices. According to Insee’s series of authorised dwellings, the 12-month total for metropolitan France fell from 469,900 in 2022 to 308,400 in 2024, a drop of a third, while official construction targets were maintained. The partial recovery to 359,900 in 2025 still left permits 23% below their 2022 level. One reading is that the gap between target and outcome reflects a saturated transmission chain more than a lack of political will.
Credit rules: the state’s strongest lever, and its own brake
Where the French state weighs most is access to credit. It backs the social home-ownership loan (PAS), whose financing and guarantee are managed by the SGFGAS, and it funds the PTZ. Those channels act on borrowing capacity directly, which is why they matter more than any tax schedule.
The same channel is capped by the High Council for Financial Stability (HCSF), France’s macroprudential authority. Its decision of 29 September 2021 turned earlier recommendations into a legally binding rule from January 2022: the debt-service-to-income ratio may not exceed 35%, and loan terms may not exceed 25 years, with banks allowed to depart from the criteria for 20% of each quarter’s new loans. Those ceilings limit how far lower rates can lift what a household is allowed to borrow, so a fall in rates passes less fully into effective demand than it would without them. One public objective, supporting buyers, runs into another, containing household debt.
The United Kingdom offers a useful comparison. In June 2014 the Bank of England’s Financial Policy Committee asked regulators to limit mortgages at 4.5 times income or more to 15% of new lending. In 2022 it dropped its companion affordability stress test, with effect from 1 August, judging the income cap more effective at restraining household debt in a scenario of rapidly rising house prices. Macroprudential tools on both sides of the Channel are built to lean against an upswing. They can restrain a boom, but they cannot lift a market out of a trough.
Assuming that a housing measure announced at the bottom of the cycle will act on the trough it targets. Implementation lags push most of its effect into the next upswing, when the need has already faded. Judging a scheme means dating its effect against the credit cycle, not against the date of the announcement.
What policy can do, and what would weaken this reading
None of this makes housing policy pointless. On targeted goals such as protecting vulnerable tenants, funding energy renovation or supporting declining areas, its effects are measurable. The ambition to smooth the national cycle is what meets hard limits: acting on symptoms remains possible, acting on the drivers requires levers that sectoral policy does not hold. The pillar on real estate, credit and rate cycles maps those drivers.
Two configurations could weaken the argument. Tighter coordination between monetary policy and housing rules, of the kind the UK income cap attempts, may reduce the amplitude of the upswing, at some cost to allocative efficiency. A sustained supply shock, with large-scale building in high-demand areas, would also change the picture, though it takes decades to deliver. Conversely, the reading would be reinforced if the next recovery opens a wider gap between announced housing plans and the actual path of permits and prices.
What to watch
For households, the timing of credit weighs more on access to housing than the calendar of support schemes. For developers and institutional landlords, the robustness of business plans depends first on financing cycles. At the macro level, monetary transmission runs through housing with particular directness, which is also why property is often mistaken for an automatic hedge against inflation.
Three measures test policy against its stated aims. The first is the gap between construction targets and authorised dwellings, published monthly by Insee as a 12-month total. The second is the debt-service ratio of first-time buyers relative to the HCSF ceiling. The third is the share of transactions that actually qualify for a given scheme. Together they show how far each measure travels before the credit cycle overtakes it.
The credit cycle behind property prices follows its own clock. Long-lived assets financed with debt and constrained by land answer to that clock first, and sectoral policy can bend their path at the margin without setting it.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Regulated and tax values: the rates, indices, caps and brackets with legal effect cited on this page are set by official decision, change over time and apply according to individual circumstances. Only the official publication in force on the relevant date is authoritative (for example the Journal officiel, INSEE, Banque de France, the IRS or the Social Security Administration). To revise a rent, sign or challenge a contract, or file a return, check the value at the source or with a professional.
Read next
Full pillar →Mortgage Credit Cycle: How Monetary Policy Transmits to Housing Prices
French mortgage lending fell 56% between 2022 and 2024, yet the national house price index never dropped more…
Real Rates and Property Valuation: Why Inflation Alone Does Not Protect Prices
A property’s value is its net income capitalized at a rate the market sets, and that rate is…
Rent Pass-Through: How Lease Structure Decides If Inflation Reaches the Landlord
US rents adjust to inflation only when a lease resets, not continuously. Fixed terms, renewal smoothing and survey…