
Volmageddon 2018: when innovation amplifies volatility

Products that rebalance daily turn a rise in VIX futures into forced purchases of more VIX futures, at a known hour. On 5 February 2018 that loop helped push the VIX up 115.6% in one session and ended the XIV note.
TL;DR
Volmageddon is the name traders gave to 5 February 2018, when the VIX rose 115.6% in one session and short-volatility products built on VIX futures lost more than 90%.
- Leveraged and inverse products all had to buy VIX futures before 16:15: the BIS counts 115,862 contracts, about a quarter of the market, in the single minute of 16:08.
- The buying need is arithmetic. A −1x or a 2x product has to buy twice the day’s rise times its starting assets, so a 96% rise in futures means 1.92 of purchases per 1 of assets.
- In 2017 the VIX closed below 10 on 52 sessions, against 9 in all the previous years of the series. After the shock it needed 13 sessions to fall back below its 2 February close; XIV was terminated.
Volmageddon is the nickname traders gave to the shock of Monday 5 February 2018, when the Cboe Volatility Index (VIX) closed at 37.32 against 17.31 one session earlier and exchange-traded products betting against volatility lost most of their value within an afternoon. The S&P 500 fell 4.2% that day, a large move that still does not account for the jump in the VIX. The BIS Quarterly Review of March 2018 compared the rise with what past equity falls would imply and found it far above that level; its model estimates pointed to dynamics inside the options and VIX futures markets.
XIV, the best-known casualty, did not track the VIX index. It tracked VIX futures, and a −1x exposure to futures that almost double leaves almost nothing. The index recovered in 13 sessions. XIV never came back. Those internal dynamics can be written down as a short calculation, and the loss attributed to XIV ranges from 84% to 97% depending on the document.
What happened on 5 February 2018
The VIX closed at 17.31 on 2 February and at 37.32 on the 5th, up 115.6%, according to FRED series VIXCLS. An Eco3min calculation on the whole series makes this the largest one-day percentage rise on record, well ahead of the next ones; the rises of March 2020 were larger only in points. Other episodes are set out in the history of major VIX spikes, and the daily closes are in the VIX volatility index dataset.
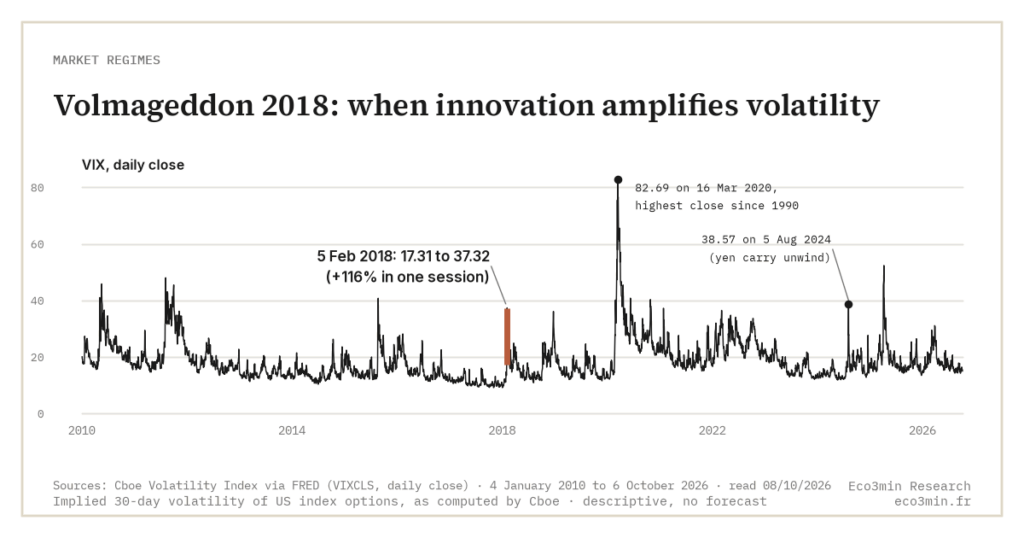
The decisive minutes came at the end of the day. The BIS sees signs of other participants bidding up VIX futures from about 15:30, ahead of a rebalancing they could anticipate just before 16:15, when the products publish their net asset value. Trading then spiked to 115,862 contracts in one minute at 16:08, at highly inflated prices.
How a record calm built the position
Volatility had rarely been so low. The VIX closed below 10 on 52 sessions in 2017, against 9 sessions in all the previous years of the series (Eco3min calculation on VIXCLS). Its record low dates from that year too, in November.
Products that sold volatility grew in that climate. SLCG Economic Consulting ties the 2017 run-up in XIV to the long stretch of low equity volatility. The BIS puts the assets of selected leveraged and inverse volatility products at about $4 billion at end-2017, and VIX futures open interest at a daily average of 590,000 contracts in 2017 against about 180,000 in 2011. Marketed for short-term hedging, these products were often held as long-term bets on low volatility, a practice the BIS likened to “collecting pennies in front of a steamroller”.
A low reading is easy to misread. The VIX is an implied measure taken from option prices: it combines expected volatility with a risk premium, and it says nothing about how many participants hold the same position. The same question returned with the low-volatility regime of 2023–2026.
The mechanics: why inverse and leveraged products buy together
An inverse product holds a short position in VIX futures; a leveraged one holds a long position worth a multiple of its assets. Both rebalance daily to keep their target exposure, usually in the last hour of trading. A day when futures rise therefore pushes both to the same side of the market, even though their holders hold opposite views.
The size of the purchase follows from simple arithmetic. Take an inverse product with assets of 100 and a short position of 100. If futures rise 30%, assets fall to 70 and the short position is now worth 130. Returning to −1x means cutting the short to 70, so the product buys 60. A 2x product with assets of 100 and a long position of 200 ends the same day with assets of 160 and a position of 260; its target is 320, so it also buys 60. In both cases the purchase equals twice the day’s rise times starting assets.
Apply that to the rise SLCG measured in the relevant futures by 16:15 on 5 February, about 96%, and the need reaches 1.92 per 1 of starting assets, while an inverse product is left with 0.04 of assets. This is an idealized calculation for a product rebalancing once at the close, not a record of the trades executed. It does show why products worth about $4 billion could matter. The need grows with the rise, it falls due at a known time, and each purchase lifts the price that sets the next one. That is the feedback loop the BIS identifies, a mechanism that belongs with the mechanics of price formation more than with any change in expectations. SLCG goes further and argues that the late futures trades appear intended to trigger the unwind; that is one consultancy’s thesis, and this page does not rely on it.
Reading XIV’s fall of about 96% as a response to the VIX’s 115.6% rise. The two figures look linked, yet the index itself cannot be bought and XIV referenced the VIX futures curve. The figure that set its value was the weighted rise in the February and March contracts, up 112.5% and 86.8% at the last trades before 16:15 according to SLCG, or about 96%.
The pressure did not stay in volatility markets. Dealers that sold VIX futures to the products hedged by shorting E-mini S&P 500 futures, which added to the fall in equities, and the BIS finds that peaks and troughs in VIX futures led those in E-mini futures that day. The same logic of synchronized fund positioning applies well beyond exchange-traded notes.
What happened to XIV: 84%, 90% or 96%?
Credit Suisse gave the closing indicative value of its VelocityShares Daily Inverse VIX Short Term ETN as $108.3681 on the Friday. It then announced an acceleration event: the intraday value on the Monday had fallen far enough to trigger the note’s early-termination clause, which the BIS describes as a loss of 80% or more from the previous close. Holders would receive the closing indicative value on a later valuation date.
Published loss figures do not agree. The BIS writes 84%. The CFA Institute summary of the Financial Analysts Journal article by Patrick Augustin, Ing-Haw Cheng and Ludovic Van den Bergen (third quarter 2021) gives more than 90% for short-volatility products. SLCG, in a private analysis of March 2018 that is not a regulatory finding, gives a revised indicative value of $4.2217, which implies a fall of 96.1% from the Friday value, while its own opening line says 97%. Not every document states the price it uses. One reading is that the gap separates traded prices from indicative value: SLCG reports buyers paying an average of $28.60 after 16:15, against a value it places between $4.22 and $4.41. This page uses 96% for the fall in indicative value on 5 February. Holders who stayed until redemption received $5.99 per note according to SLCG, 94.5% below the Friday value, because the payment used the indicative value of 15 February.
What the shock left behind
The VIX closed back below its 2 February level after 13 sessions. XIV’s end came from a clause in its terms, the fall through 80%. SVXY, a similar fund, also plunged more than 90% in extended trading on the Monday, kept trading, and from late February aimed for half the inverse move of its index, according to Financial Planning (27 February 2018).
The products do not carry the whole explanation. The VIX had already been rising before the Monday, and equities were falling before the close, so the trigger lay outside the rebalancing. The BIS writes that these strategies appear to have been a key factor, and that the positions were relatively small in aggregate. The CFA Institute summary stresses the opposite side of the same fact: the large share of VIX futures contracts held by leveraged products. One reading reconciles the two: small against equity markets, large in a narrow futures market. On that reading, the measure to watch is the rebalancing need of leveraged and inverse products over VIX futures open interest. It describes exposure to the loop and gives no date.
Volmageddon 2.0 and the later shocks
The closest later case is 5 August 2024, when the VIX closed at 38.57. BIS Bulletin 90 (27 August 2024) attributes the amplification to the unwinding of leveraged trades in equities and currencies, puts FX carry trades at a rough ¥40 trillion ($250 billion) going in, and points to procyclical deleveraging and margin increases. Its account runs through leverage, margins and currencies, the territory of the yen’s long slide and the 2024 unwind, and its key takeaways do not name end-of-day product rebalancing. What the two BIS accounts share is amplification by rules: rebalancing targets in 2018, deleveraging and margin increases in 2024.
Higher levels do not by themselves show the same mechanism. The VIX set its record close in March 2020 and closed above its 2018 level again in April 2025, and nothing in the series separates the initial shock from any amplification. The label “Volmageddon 2.0” raises the same question. In February 2023 JPMorgan’s Marko Kolanovic applied it to the rise of same-day options, and Bank of America strategists pushed back a week later, arguing that those options serve too many different strategies for one failure to spread far. The test of any such claim is the calculation above: how much has to be bought, by when, and against what depth of market.
The case gives no critical VIX level, no timetable and no estimate of the next episode. It belongs to the silent adjustment regimes as an example of amplification by rules, and to the wider question of where financial innovation meets systemic risk. Its narrower lesson is mechanical: a low VIX and a large rebalancing need can coexist, and only the second one is written into a product’s rules.
Common questions about Volmageddon
When was Volmageddon?
On Monday 5 February 2018. Most of the damage to volatility products came in the final hour of trading and just after the equity close.
What caused Volmageddon?
Falling equities and a rising VIX started it. Daily rebalancing by leveraged and inverse volatility products then required large purchases of VIX futures at a known time, and those purchases raised the price that determined further purchases. The BIS and the CFA Institute summary of the Financial Analysts Journal article both describe this feedback loop.
Was XIV an ETF, and what happened to it?
XIV was an exchange-traded note rather than an ETF: a debt security with a clause allowing early termination after a fall of 80% or more. Its indicative value fell about 96% on 5 February 2018. Its issuer, Credit Suisse, announced the acceleration the next day.
Last updated — 6 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Eurozone Fragmentation: Sovereign Spreads and the Euro
The euro is issued by a monetary union without a complete fiscal union: twenty-one sovereign debts coexist under…
Why the Euro Moves Against the Dollar: the ECB-Fed Differential and Euro-Specific Forces
To first order, EUR/USD tracks the policy differential between the ECB and the Federal Reserve; to second order,…
Yen Carry Trade: The Hidden Leverage Shaking Forex and Portfolios
The yen has weakened ≈25% against the dollar since 2022, fueling a carry trade that funds positions in…