
60/30/10 Portfolio Grid: Reading Allocation After Zero Rates
Higher rates, positive real yields, wider dispersion: the 60/30/10 split is best read as an analytical grid for examining a portfolio's risk structure, not as a recommended allocation. What changes when bonds and cash earn a coupon again.

TL;DR
How to read a 60/30/10 split in a regime of higher rates, positive real yields and wider dispersion: an interpretive grid, not a prescription.
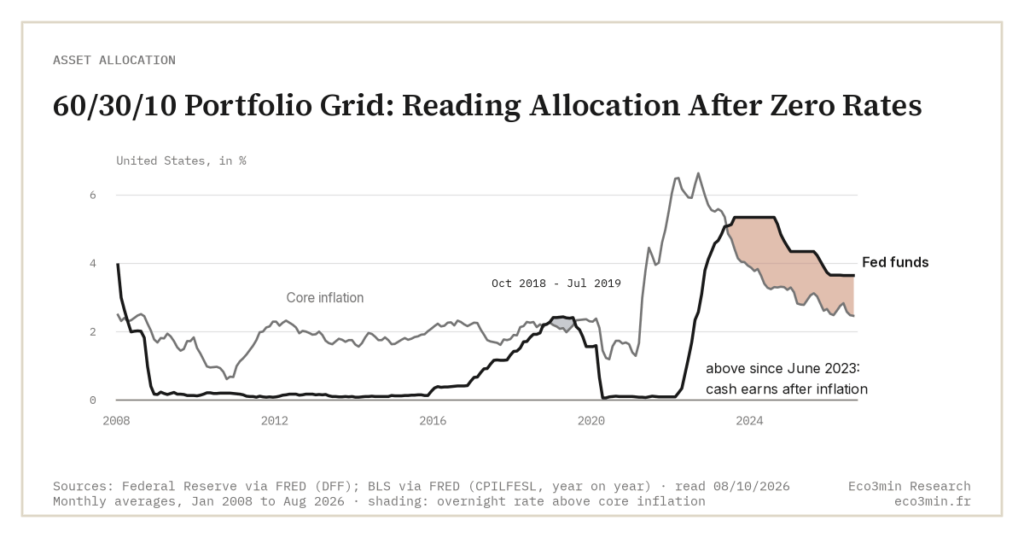
- Positive nominal and real yields have restored an economic role to the bond component, which it had largely lost in 2010–2021.
- Cash now carries a yield, so it can absorb shocks rather than only wait; portfolio structure matters as much as line selection under stress.
- Index stability can mask underlying fragility, with equity indices still concentrated in a handful of mega-caps even at highs.
The end of the zero-rate era has changed the underlying mechanics of asset allocation. For more than a decade, most portfolio results were driven by rising equity markets and multiple expansion, both compatible with a falling cost of capital. The return of positive real bond yields and a higher cost of capital reshuffles that landscape. Portfolio structure, how the components interact under stress, now matters as much as the selection of individual lines. Background: our analysis of investment discipline and long-term portfolio performance.
This reading fits into a broader logic of financial education across macroeconomic regimes: understanding the mechanism comes before optimising the result.
In brief
- Positive nominal and real yields have restored an economic role to the bond component, which had largely lost it during 2010–2021.
- Cash now carries a yield: it can absorb shocks rather than only waiting.
- Equity indices remain concentrated in a handful of mega-caps even at index highs, which means index-level stability can mask underlying dispersion.
- Allocation rules inherited from the zero-rate decade are losing relevance in the current regime.
- A 60/30/10 split is one way to read a portfolio in terms of risk structure rather than past performance: an analytical grid, not a recommended split.
What is actually changing in markets
- The US 10-year Treasury yield averaged 4.14% in December 2025 and reached 4.96% on 21 September 2026, against a 0.52–1.88% range in 2020–2021 (FRED, DGS10).
- Headline inflation across the OECD stood at 3.6% in December 2025, down from a 10.6% peak in October 2022, and was back at 4.1% in July 2026, not yet settled durably near central-bank targets (OECD consumer price statistics).
- Equity ETF flows have remained heavily concentrated in US technology and AI-linked names through 2024 and 2025, reinforcing concentration risk in cap-weighted indices.
- Cash yields stood at 3.64% in the US (effective fed funds rate) and 1.93% in the euro area (€STR) at the end of 2025, and at 3.88% and 2.44% on 21–22 September 2026, which restores the opportunity cost calculation between cash and risk assets, without erasing the long-run drag of excess cash holdings over a full cycle.
These dynamics belong to a more fragmented market regime, in which aggregate performance can mask significant gaps between sectors and asset classes.
Macro reading: what the regime changes in the analytical grid
Between 2010 and 2021, most outperforming portfolios benefited from an exceptionally accommodative monetary backdrop. The steady decline in rates mechanically supported valuations across asset classes. That mechanism is now weaker. In a world of more moderate growth and cautious monetary policy, the contribution of bond coupons and liquidity becomes visible again in total-return arithmetic. For context: next-generation guaranteed vehicles by regime.
The reading of these balances remains closely tied to the structure of the macroeconomic cycle, especially as reflected by signals such as the yield curve, which continues to inform expectations for growth and monetary policy.
How the 60/30/10 grid is read at Eco3min
A 60/30/10 split, understood as an analytical grid, distributes a portfolio across three functional roles:
- Equities (60%): long-run growth engine, but sensitive to the economic cycle and to valuation. This is the part of the portfolio that captures real growth in productive capital.
- Bonds (30%): a source of more predictable return and a volatility buffer when real rates are positive. This is the part of the portfolio that earns a contractual cash flow.
- Cash (10%): a source of optionality. This is the part of the portfolio that absorbs shocks and finances transitions.
The grid is not a universal split and is not presented here as such. It is an interpretive frame for examining the trade-off between expected return, volatility, and liquidity in a given regime. Read this way, the question stops being “what is the right allocation” and becomes “what does my current allocation say about the regime I am implicitly betting on”. Eco3min examines this in commodities across inflation regimes.
The grid is only meaningful at the right point in the decision chain. The take on structuring financial decisions over time shows that asset allocation is never an isolated choice: it comes after a stabilised budget, a built liquidity margin, and a clarified time horizon. Applied earlier in the chain, even a theoretically robust grid produces incoherent trade-offs.
To be read properly, this analytical grid must be set against a broader view of structured asset allocation, which distinguishes the long-term core, satellite positions, and defensive pockets. It also presupposes that the monthly budget leaves enough room for manoeuvre: a point developed in the analysis of the 50/30/20 budget as the foundation of investment capacity.
Structural indicators to monitor
- Gap between bond yield and cash yield: documents the trade-off between immediate liquidity and duration exposure.
- Concentration of equity indices: an excessive share for the largest names can mask underlying market fragility. The top 10 names in the S&P 500 represented 37.8% of the index on 31 August 2026, a historically high level (S&P Dow Jones Indices).
- Average duration of the bond sleeve: determines portfolio sensitivity to rate moves.
- Weight of highly volatile assets: a marginal share contains the impact of tail shocks at the portfolio level.
Three plausible macro scenarios
Scenario 1: Moderate growth, contained inflation
Global growth runs close to potential and inflation stabilises slightly above central-bank targets. Bond yields stay positive without acute pressure. In this setting, the complementarity between equities and bonds remains functional, and the 60/30/10 grid keeps its analytical balance.
Scenario 2: Inflationary resurgence
Fresh price pressures force central banks to hold rates higher for longer. Long-duration assets become more sensitive, and the average duration of the bond sleeve turns into a central parameter rather than a passive choice. The grid still reads, but the bond component shifts function.
Scenario 3: Pronounced slowdown
A weakening in growth and earnings triggers a correction in equity markets, while monetary easing supports bond assets. Cash takes on a buffer and transition role rather than an opportunity-cost one. The relative weight of the three components matters less than their interaction under stress. Whether bonds cushion equities or fall alongside them decides that interaction, a question at the core of how correlations shape risk across a portfolio.
Reading, not prescription
The current regime brings asset allocation back to the centre of risk management. A grid such as 60/30/10 should be read as an analytical lens for interpreting the trade-offs between risk, return, and liquidity, not as a recipe. In a less predictable environment, portfolio robustness depends less on market forecasting than on the coherence of the construction across several macro scenarios. Worth reading alongside: our analysis of choosing investments in the light of the macro cycle.
What a portfolio holds matters less than what it is exposed to. The return of positive real rates makes that distinction visible again; diversification is measured by the nature of the risks carried, not by the number of lines on a statement.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Investment Discipline and Long-Term Portfolio Performance
Long-term portfolio performance is not driven by stock selection or market timing. It is driven by decision discipline:…
What Guaranteed Savings Products Have Paid: Fixed Annuity and Stable Value Yields Through the Rate Cycle
US guaranteed savings products credit a rate that trails the bond market rather than tracking it. Through the…
Beneficiary Designations, the Step-Up in Basis, and the 10-Year Rule: How US Accounts Transfer at Death
At death, most US financial accounts pass outside the will, straight to a named beneficiary, under tax rules…