
Low Rates and Growth: When Stimulus Becomes Drag
Persistent low rates do not mechanically deliver growth. Beyond a certain duration, they preserve unviable firms, divert credit toward asset markets and erode bank intermediation — turning the stimulus into its opposite.

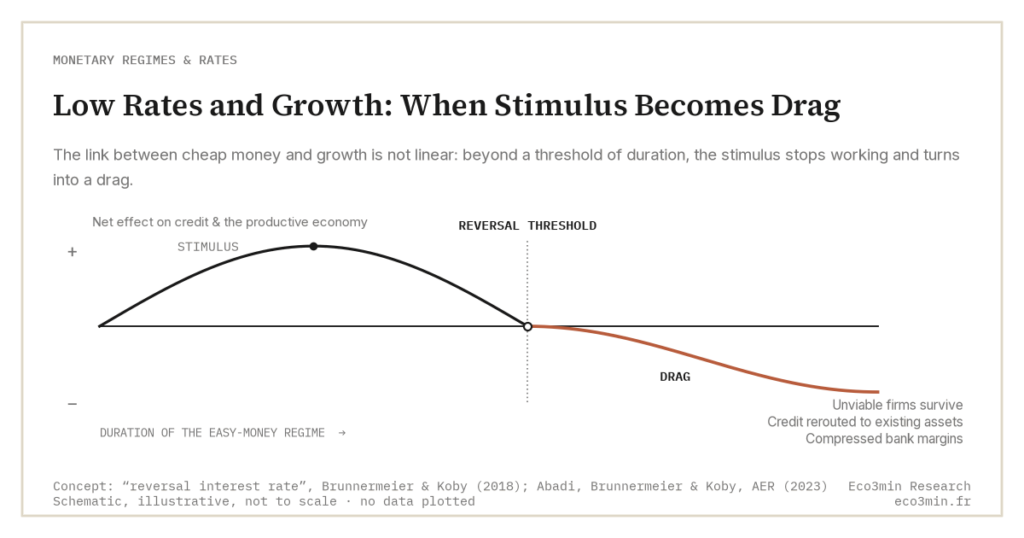
The standard reading that low rates mechanically lift growth treats the link as linear and permanent. The eurozone’s decade of negative short-term real rates says otherwise: distortions accumulate, and beyond a certain duration the stimulus reverses into a drag.
TL;DR
Across the eurozone's decade of negative short-term real rates (2012-2022), real GDP growth averaged about 1.5% a year on a compound basis (Eurostat); past a point, cheap money stops feeding the channels it targets and erodes them.
- The BIS put 'zombie' firms at about 12% of listed companies in fourteen advanced economies by 2016, up from about 2% in the late 1980s, once the real cost of capital stopped filtering out businesses that could not cover it.
- Euro area banks' net interest income fell to 1.14% of total assets in 2020 from 1.35% in 2010 (ECB consolidated banking data), thinning the buffer that funds lending; the 'reversal interest rate' (Brunnermeier and Koby, 2018) marks where further easing tightens credit instead of loosening it.
- The return to mildly positive real rates in early 2026 reads in this framing as restored filtering rather than a brake on growth, a profitability test on investment that registers only slowly in GDP.
What the post-2012 record shows is not that easy money failed outright, but that it stopped working, and started actively damaging the channels it was meant to feed.
Persistent low rates do not deliver growth automatically. The case for non-linearity, capital misallocation, and the reversal threshold.
The proposition that cheap money supports growth is one of the least contested in policy discourse. The chain of reasoning is short: lower funding cost, more investment, faster activity. The eurozone tested that premise for a full decade. Between 2012 and 2022, short-term real rates stayed negative in all but four months, and average real GDP growth came in at 1.5% per year on a compound basis (Eurostat). Productivity slowed, R&D capex did not scale, and the share of fragile firms climbed. The coincidence is striking enough to warrant looking past the textbook channel and reconsidering how real rates structure capital allocation in the first place.
The reasoning stops at the first round
The direct channel is real: lower rates cut financing costs, and projects at the margin of viability become viable. The same pattern shows up across cycle phases, as the analysis of inverted-curve episodes and subsequent equity rallies documents. But the offsetting effects are routinely skipped. The first one is the survival of firms whose business model cannot cover the normal cost of capital. The BIS measured the drift: “zombie” firms rose from about 2% of listed companies in fourteen advanced economies in the late 1980s to about 12% by 2016 (Banerjee and Hofmann, BIS Quarterly Review, September 2018), a ratchet the authors tie to reduced financial pressure, that is, to a real cost of capital that no longer played its filtering role.
The second is the rerouting of credit toward existing assets rather than productive investment. The BIS lists capital misallocation among the costs of very low rates held for very long, alongside the build-up of debt and the declining profitability of financial intermediaries (Annual Economic Report 2024, Chapter II). Euro area house prices rose 47% between Q1 2015 and Q4 2022, against 12% for real GDP over the same years (Eurostat), absorbing a growing share of available financing. The shift in capital allocation under prolonged negative rates is exactly the mechanism behind the perverse effects of negative real rates on the productive base.
The channel erodes the channel
The third effect is the one that most directly breaks the linear model: persistent low rates compress the very intermediation margin that is supposed to deliver credit. Euro area banks’ net interest income dropped to 1.14% of total assets in 2020, from 1.35% in 2010, and to a series low of 1.10% in 2021 (ECB consolidated banking data). Thinner margins mean less capacity to absorb non-performing loan losses, which pushes banks to ration credit to riskier borrowers, the same borrowers that low rates were supposed to bring back to the financing table. Related analysis: our note on the transmission of monetary policy to company results.
Brunnermeier and Koby named this self-defeating dynamic the “reversal interest rate” (NBER working paper, 2018; American Economic Review, 2023, with Abadi): the policy rate below which further easing tightens credit conditions instead of loosening them. An ECB model places it at around −1% per annum for the euro area, a level that depends on how well capitalised banks are (Darracq Pariès, Kok and Rottner, ECB Working Paper No 2487, November 2020). It remains one of the clearer pieces of evidence that the relationship between rates and credit is not monotonic.
Treating the rate–growth link as linear and permanent. Low rates do stimulate at the start; the effects deteriorate, and can flip sign, with duration. Capital misallocation, compressed bank margins and the survival of unviable firms are structural drags that surface with a lag, making the policy look effective long after it has stopped working.
What this implies for the current regime
The return to mildly positive real rates in early 2026 is not, on this reading, a brake on growth. It is a return to filtering. Restoring a profitability test on investment, rebuilding bank margins and pruning the unviable end of the productive base are improvements that take time to register in GDP and look painful in the short run. The bank margin is already measurable: euro area net interest income recovered to 1.47% of total assets in 2023 and 1.40% in 2025, above its 2010 level (ECB). The ECB has since raised its deposit rate to 2.25% from 17 June 2026 and to 2.50% from 16 September 2026. The variable that matters is not the level of rates at a given moment but the duration over which a regime persists, and the volume of distortions that regime has time to accumulate inside the financial conditions that feed those distortions.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Why Markets Can Rise Despite an Inverted Yield Curve
An inverted yield curve can coexist with rising markets without invalidating the signal. The lag reflects a structural…
Central Banks Diverge: Fed, ECB, BoE and BoJ After the Easing Cycle
After a shared easing cycle, the Fed and the ECB are hiking again, the BoE hesitates and the…
The Yield Curve: What the Level Says That the Slope Doesn’t
A flat curve can sit at 1.5% or at 4.2%: the slope is the same, but the cost…