The After-Tax Cost of Moving Cash Into Equities

Comparing a savings account’s yield with an equity return at their headline rates is a false calculation: it ignores tax, which does not hit the two the same way. A regulated savings rate is net; an equity portfolio’s return is gross, and the wrapper decides what survives.
This piece quantifies the gap after tax, wrapper by wrapper, using French savings products and equity wrappers as the case study. It stays strictly descriptive: it measures the after-tax cost and return of moving capital, it does not say the move should be made.
A regulated savings rate is quoted net of tax; an equity return is gross, and the wrapper holding it decides what fraction survives taxation.
- France’s Livret A, at 1.5% net since February 2026, is exempt from income tax and social levies, so the headline rate is the rate actually received.
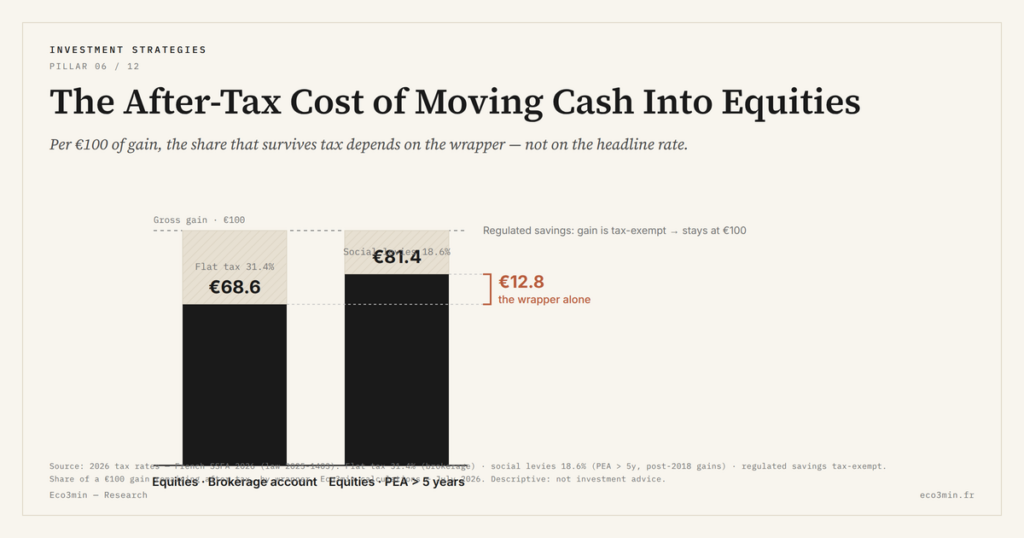
- An equity gain in a taxable account bears the 31.4% flat tax; in a five-year-plus tax-sheltered plan, it bears only the 18.6% social levies.
- The honest comparison is the after-tax, after-inflation return, weighed against a capital-loss risk the savings account does not carry.
Comparing a savings account’s yield with an equity return at their headline rates is a false calculation: it ignores tax, which does not hit the two the same way. A regulated savings rate is net; an equity portfolio’s return is gross, and the wrapper decides what survives. This piece quantifies the gap after tax, wrapper by wrapper, to make the comparison honest. Using French savings products and equity wrappers as the worked case, it draws on both sides of the question without re-explaining either: the mechanics of cash and savings, set out in the reading of what protects savings by regime, and those of equity wrappers, which it folds into a single measure. This is the bridge between the two, reading the wrapper as the wrapper as a cost mechanic.
1. Why the headline yield misleads
A regulated savings rate is quoted net. France’s Livret A, set at 1.5% since 1 February 2026, is exempt from both income tax and social levies: the headline rate is the rate actually received, with no later deduction. The same holds for the companion sustainable-development passbook at the same rate, and for the means-tested popular savings account. On these vehicles, the figure quoted is the figure banked. The principle generalizes: wherever a savings instrument is tax-exempt by statute, its rate is already a net rate.
An equity return does not work this way. A portfolio’s headline return, whether a market performance or a dividend yield, is gross: it is measured before tax, and the wrapper determines what remains once taxation applies. The same 7% return does not leave the same amount depending on whether it sits in a taxable account, a young tax-sheltered plan or a mature one. Comparing that gross 7% with the savings account’s 1.5% net sets two figures side by side that are not expressed in the same unit. An honest comparison first restates the equity return as its after-tax equivalent. Restating returns net of tax is what determines where an ordinary brokerage account lands in the last rung of the priority order.
A further difference sits in the ceilings. France’s Livret A is capped at 22,950 euros of deposits, while the sheltered equity plan admits up to 150,000 euros; beyond those limits, additional cash falls into a taxable account or an ordinary deposit. The comparison therefore shifts with the amounts involved: a small balance fits entirely within the net savings vehicle, where the headline rate is the realized rate, while a larger one necessarily spills into wrappers where the after-tax arithmetic above applies. The ceiling is part of the calculation, not a footnote to it, and it means the relevant comparison depends on how much capital is in play. Raise or cut the rate on those gains and the arithmetic shifts for every holder at once, which is where capital gains tax changes meet market behaviour.
2. The after-tax return, wrapper by wrapper
In a taxable brokerage account, gains and dividends bear the 31.4% flat tax since 2026. A 7% gross return, once realized and taxed, falls to roughly 4.8% after tax, that is 7% multiplied by a coefficient of 0.686. It is this 4.8%, not the gross 7%, that compares with the savings account’s 1.5% net. The most common wrapper therefore takes close to a third of the equity return before any comparison begins. In euro terms, on 50,000 euros placed for a year, a 1.5% net savings account yields 750 euros, while a 7% gross equity return of 3,500 euros leaves about 2,400 euros after the flat tax in a taxable account. Companion analysis: how wrappers and deductions shift the bill.
A five-year-plus tax-sheltered equity plan changes the arithmetic. Gains there are exempt from income tax; only the 18.6% social levies remain. The same 7% gross return then leaves roughly 5.7% after tax, that is 7% multiplied by 0.814, or about 2,850 euros on the same 50,000 euros. The gap between the two wrappers, at an identical gross return, reaches close to a full point of after-tax return purely through the wrapper. This is the variable tier of taxation that the tax breakeven behind the gap examines, folded here into a single measure. One qualification sharpens the taxable-account figure: dividends are taxed each year as they are paid, while capital gains are taxed only when positions are sold, so a buy-and-hold portfolio that is not sold defers part of its tax and narrows the gap with the sheltered plan until a sale crystallizes it.
3. Inflation, the common denominator
A comparison of returns is complete only once inflation is subtracted, because it erodes both sides. A vehicle’s real return is its after-tax return minus inflation. For the Livret A at 1.5% net, with French inflation hovering between roughly 1% and 2% through 2026 depending on the month, the real return sits between slightly positive and slightly negative: the savings account approximately preserves purchasing power without generating a substantial real gain.
The same calculation applies to equity wrappers, on their after-tax return. A mature sheltered plan at 5.7% after tax, less 1.5% inflation, yields a real return on the order of 4.2%; a taxable account at 4.8% after tax, about 3.3%. These figures are not promises: the equity return is expected, not guaranteed, and it carries a capital-loss risk the savings account does not. The measure compares after-tax real returns; it does not compare levels of safety, which belong to a separate dimension. Moving into equities exposes capital from the outset to the sequencing risk on entry, absent from a savings account.
That asymmetry runs deeper than a single year’s figures suggest. A savings account’s net return is realized with certainty each year; an equity return is an average over time, around which individual years can swing sharply, including into loss. The after-tax gap measured here is an expected gap, not a realized one, and the order in which good and bad years arrive matters as much as their average, particularly near the start of the holding period. A favorable long-run after-tax return can still coincide with a painful first few years, which is precisely the dimension a comparison of average rates omits. Realising a loss in one of those weak years is exactly where the repurchase timing starts to matter, a constraint set by the wash sale rule applied to loss harvesting.
- A regulated savings rate is net of tax; an equity return is gross, and the wrapper decides what fraction survives taxation.
- A 7% gross return leaves about 4.8% in a taxable account after the flat tax, and about 5.7% in a five-year-plus sheltered plan.
- The honest comparison is the real, after-tax return with inflation subtracted, not the headline rates.
- The equity return is expected and carries a loss risk the net, guaranteed savings rate does not.
4. What the measure does not say
Quantifying the tax cost of moving capital does not say the move should be made. Measuring that an after-tax equity return exceeds, in expectation, a savings account’s net rate is not advice: the decision depends on the need for liquidity, the horizon, tolerance for loss and the overall composition of wealth. The measure lights up an after-tax return gap; it does not settle the trade between safety and expected return. Related coverage: our reading of pre-tax 401(k) and IRA rules.
The wider point is method: a return compares honestly only once tax and inflation are equalized across the two. A savings account’s headline rate and an equity return are not expressed in the same unit, and the wrapper is precisely what converts one into the other. The method generalizes beyond these specific products: any system that exempts a savings instrument while taxing equity returns produces the same distortion, a net rate set against a gross one. The figures change, a different exemption, a different equity rate, a different inflation reading, but the correction is identical, and restating the gross return as an after-tax, after-inflation figure is what makes any such comparison honest. This reading sits within the broader work of choosing by macro regime, where the real after-tax return is one variable among others, alongside risk and horizon.
One question remains, made visible without being settled: for a given amount of capital, does the after-tax real return gap between cash and equities justify the loss risk the move carries? The answer depends on the horizon, the tolerance for loss and the wrapper chosen. It is because it depends on all three that moving from cash into equities reads as an individual trade-off, not a general rule.
Last updated — 29 August 2026
Disclaimer – Financial Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader.
Read next
Full pillar →Beneficiary Designations, the Step-Up in Basis, and the 10-Year Rule: How US Accounts Transfer at Death
At death, most US financial accounts pass outside the will, straight to a named beneficiary, under tax rules…
The Fee Stack in Variable Annuities: M&E Charges, Riders, and Subaccount Costs
A variable annuity does not carry one fee, but a stack of them. Mortality and expense charges, subaccount…
The Conventional 401(k)-Match-First Funding Order: Where It Comes From, How It Works
The question of what order to fund accounts in usually draws a fixed list, presented as a rule…