
Sector Rotation and Style Regimes: Value, Growth and Market Cycles
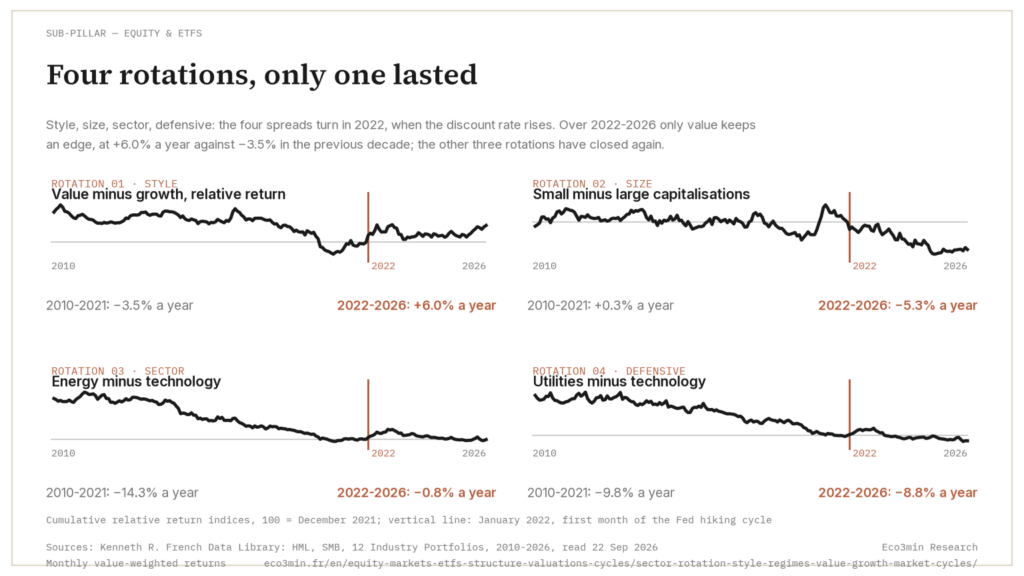
Sector rotation is not a prediction strategy: it is a reading of the market’s implicit arbitrages. When flows migrate from cyclicals to defensives, when value outperforms growth, when small caps decouple from large caps: the market is signaling its perception of the current regime. Reading these rotations means reading the cycle as institutions see it, with a lead over macroeconomic data.
In 2022, the Russell 1000 Value outperformed the Russell 1000 Growth by 22 percentage points (Russell Investments), a rotation of rare magnitude. The U.S. energy portfolio gained nearly 65% while the business-equipment portfolio (computers, software, electronics) fell 32% (Kenneth French’s industry portfolios, Ken French Data Library), a spread of nearly 97 points. Small caps (Russell 2000) underperformed the S&P 500 for the year (Russell). These three moves (value vs growth, energy vs tech, small vs large) tell the same story: the shift from a zero-rate, abundant-liquidity regime (favoring growth, tech, and long-duration assets) to a high-rate, monetary-tightening regime (favoring value, real assets, and strong balance sheets). Sector rotations are not random: they are directly observable symptoms of macroeconomic regime shifts.
Sector rotation: the cycle read through flows, with data
Sector rotation is the movement of investment flows from one sector to another throughout the cycle. The classic pattern (recovery → cyclicals, expansion → tech/growth, late cycle → defensives, contraction → cash/bonds) is real, but applying it mechanically is a mistake, because each cycle operates within a different regime of rates, liquidity, and starting valuations.
Recovery (exit from recession): flows move toward cyclicals, industrials, materials, consumer discretionary, small caps. The Russell 2000 clearly outperformed the S&P 500 between November 2020 and March 2021 (Russell Investments), and US small-cap ETFs (IWM) drew heavy inflows (Bloomberg). Materials followed the same move. Financials benefit from yield-curve steepening, as the strong rise of XLF (financials ETF) between November 2020 and March 2022 showed.
Mature expansion: tech and communication services take the lead, supported by earnings growth and risk appetite. The Magnificent 7 accounted for 60% of the S&P 500’s rise in 2023 (Goldman Sachs). QQQ (Nasdaq-100 ETF) gained 55% in 2023, against 26% for the S&P 500 including dividends (Aswath Damodaran, NYU Stern), whose equal-weight version did markedly worse. Late cycle: flows migrate toward defensives, healthcare, utilities, consumer staples. In the second half of 2022, “quality factor” ETFs (QUAL) drew inflows while growth ETFs (QQQ) saw outflows (Bloomberg). Defensive flows of that kind land on a sector whose earnings now hinge on a capital-spending cycle more than on the discount rate, which is what places the role utilities play in the energy transition at the centre of the equity debate. Utilities even gained nearly 3% in 2022, while business equipment lost 32% (Kenneth French’s industry portfolios, Ken French Data Library).
The Capital Flows sub-pillar analyzes ETF flow data that reveal these rotations in real time.
Value vs Growth: the rate regime settles the debate
The value/growth divide is not philosophical: it is an arbitrage on the discount rate. Growth stocks (high P/E, distant cash flows) are mathematically more sensitive to the discount rate than value stocks (low P/E, near-term cash flows). When the discount rate rises from 0% to 5%, the present value of cash flows 10 years out falls by ~40%: cash flows 2 years out fall by only ~10%. This arithmetic explains why growth outperforms in low-rate regimes and value in high-rate regimes. Read alongside: how value and growth compare.
The data: between 2007 and 2021 (structurally falling rates, then zero), the Russell 1000 Growth outperformed the Russell 1000 Value by a wide margin (Russell Investments). The 2010–2020 decade was the worst for value since 1927, the start of the Ken French Data Library record (Fama and French). The “value premium”, historically 3–5% per year since 1927 (Fama-French, Ken French Data Library), was negative cumulatively from 2007 to 2020, a span of 14 years.
Then the regime changed. In 2022, the Fed raised rates from 0% to 5.25% in 16 months. The Russell 1000 Value fell far less than the Russell 1000 Growth, a 22-point gap (Russell Investments). Energy (most “value” sector): nearly +65%. Business equipment (most “growth” sector): -32% (Kenneth French’s industry portfolios, Ken French Data Library). The rotation is not mysterious: it is the arithmetic consequence of a higher discount rate. Discount rates alone do not explain the long derating of oil and gas equities, which is the puzzle behind the persistent lag of energy stocks through transitions.
The allocator’s question is therefore not “value or growth?” but “which real-rate regime are we in, and which style does it mechanically favor?” As long as real rates remain meaningfully positive (TIPS >1.5%), the structural tailwind favors value. A return to zero rates (unlikely short term, possible in a severe recession) would restore growth’s advantage. The Foundations of Allocation sub-pillar integrates this framework into portfolio construction.
Since 2021: the real yield behind the style rotation
The real-rate regime in that question can be dated on the 10-year Treasury Inflation-Protected Securities yield (US Treasury, DFII10). It touched −1.19% on August 3, 2021, turned positive on a monthly average basis in May 2022 (+0.21%) and peaked at 2.52% on October 25, 2023. It closed above that peak on September 10, 2026 and stood at 2.91% on October 6, a level last seen on November 24, 2008. Over 2010-2021 the same yield averaged 0.22%, and 29.1% of trading sessions printed a negative value.
The rise is real rather than inflation compensation. The 10-year breakeven inflation rate eased from 2.56% at the end of 2021 to 2.36% on October 6, 2026. Part of the rise in long yields comes from the term premium, the extra compensation investors demand for holding a long bond rather than rolling short ones. On the Federal Reserve Bank of New York estimates from the Adrian, Crump and Moench model (October 2026), the 10-year term premium was still −0.12 point at the end of September 2024 and reached +0.89 at the end of September 2026. What has moved is the price of duration, not its volatility. Daily changes in the 10-year Treasury yield annualize to 67 basis points over the twelve months to October 6, 2026, against 68 over 2015-2019 (Eco3min calculation on DGS10). The Cboe VIX averaged 18.1 over the same twelve months against 15.1 over 2015-2019 (Cboe, via FRED).
Inside US equity indices, two movements pull in different directions: concentration by size, rotation by style. The largest companies keep pulling ahead, while the ranking between valuation styles has turned, and that shift is where a change in the cost of capital shows up first. The megacaps escape the pull of the discount rate only to the extent that their current profits, not their future ones, carry their valuation.
The link between real yields and style rotation holds only while the discount rate dominates earnings. A growth shock that pulls real yields back below their 2023 peak, a run of earnings revisions in favor of the largest companies, or a return of inflation that lets breakevens drive long-term borrowing costs, as in 2022, would weaken it. Two series separate these cases. The first is the 10-year real yield against its October 2023 peak of 2.52%: a close above that line keeps the cost-of-capital reading intact. The second is the monthly value-minus-growth factor, published with roughly a one-month lag. If value keeps outperforming while real yields rise, the rotation is following the discount rate; if it reverses while real yields keep climbing, earnings have taken over as the driver.
Inflation reshuffles sectors: in predictable ways
Inflation does not affect all sectors equally. The key discriminant is pricing power: a firm’s ability to pass higher costs onto prices without losing volume.
Inflation winners: energy (producers of the appreciating input, nearly +65% in 2022 for Kenneth French’s energy portfolio). The structural pricing-power logic behind these sector winners is examined in the analysis of corporate pricing power and margins. Materials (same logic, commodity producers). Financials (higher rates = higher net interest margins, even though Kenneth French’s financials portfolio fell 17% in the first half of 2022 along with the market). European luxury (exceptional pricing power: LVMH raised prices 8–10% per year in 2022–2023 without significant volume loss, annual reports). Losers: labor-intensive or structurally low-margin sectors, food retail (Carrefour EBIT margin ~3%), transport (fuel costs not fully transferable), low-price services. Tech has a mixed profile: low variable costs (gross margins 60–80%) but valuations highly sensitive to real rates (long duration).
Composition matters more than level. When inflation is driven by demand or by sector-specific supply constraints, some companies raise prices faster than unit costs. When it is concentrated in energy, wages or commodities, it weighs directly on the margins of sectors that cannot pass the increase through. Disinflation does not erase the gap it opened. US CPI peaked at 8.98% year on year in June 2022, averaged 8.00% that year, then 4.15% in 2023 and 2.95% in 2024 (BLS). Six points of disinflation in two years, yet highly differentiated sectors returned to their historical margins while those that take the price of their inputs did not.
Mobile inflation keeps dispersion open. US CPI climbed from 2.39% in January 2026 to 4.17% in May, before easing to 3.35% in August (BLS, year on year). Inflation moving around 3% triggers neither a uniform shock nor a rapid normalisation of costs, and that is the regime which widens sector gaps the most. It also works through the discount rate. The US 10-year real yield held a 1.67%–2.34% band in 2025, for a 1.96% average (FRED, series DFII10), and companies whose value rests on near-term recurring cash flows held up better than those dependent on long-term growth promises. The yield has since averaged 2.11% across 2026 and reached 2.68% on 18 September 2026. Moderate but persistent inflation combined with wage pressure could extend the divergence between price makers and price takers even without a fresh macro shock. A rapid fall in inflation, a negative demand shock or stricter price regulation would narrow it.
The sector inflation analysis breaks down these dynamics using historical GICS sector data in inflationary regimes. The Inflation sub-pillar provides the macro framework determining which sectors outperform depending on the type of inflation (demand-driven, cost-push, structural).
“US outperformance” is largely disguised sector outperformance. The S&P 500 allocates 32% of weight to tech + communication services (S&P Global, 2024). Europe’s STOXX 600: 8% tech, but much heavier weights in financials and industrials (STOXX/Qontigo). China’s CSI 300: 25% financials, 15% consumer (CSRC). Investing in a geographic ETF is implicitly making a sector bet.
The S&P 500 outperformed the STOXX 600 by a wide margin between 2010 and 2023. But decomposed analysis (Bridgewater, MSCI) shows that a large share of this gap is explained by sector composition (US tech overweight vs Europe financials/industrials overweight). When US tech weakens, as in 2022, the US/Europe gap narrows: that year the STOXX 600 fell markedly less than the S&P 500. The analysis of US outperformance decomposes these drivers.
The choice between a global ETF and geographic ETF allocation is structurally decisive. A global ETF (MSCI World) allocates ~70% to the US and a notable share to the Magnificent 7 alone (MSCI): an implicit sector bet on US tech, not neutral geographic diversification. Geographic ETFs allow exposure adjustments, but require conviction on future rotations.
Thematics: when narratives disconnect valuations from fundamentals
Thematic ETFs (AI, energy transition, cybersecurity, digital health, space economy) capture real structural trends, but their investment performance is systematically disappointing. The S&P Global Clean Energy index more than doubled in 2020 (S&P Global), then gave back most of that gain between 2021 and 2023. ARK Innovation ETF (ARKK), emblem of “disruption,” rose 153% in 2020, then lost more than that gain in 2022 (Bloomberg). AI thematic ETFs drew heavy inflows in 2023 (ETFGI), after Nvidia had already risen 240% that year.
The pattern is systematic and documented (Morningstar 2023, “The Big Shortcoming of Thematic Funds”): thematic ETFs launched after a trend becomes media-visible underperform broad indices in 75% of cases over 5 years. Investors arrive after the initial surge and bear the correction risk. Flows are procyclical: peak inflows at enthusiasm highs, outflows at lows. The AI ETF risk analysis and the study AI thematic ETFs: flows, valuations and hidden risks dissect this mechanism.
The core mistake: confusing a real economic trend with an attractive investment opportunity. The internet transformed the global economy, but buying the Nasdaq at its March 2000 peak delivered no real return for a long time. AI will likely transform the global economy, but that does not ensure “AI ETFs” bought after Nvidia’s +240% surge will outperform. The question is never “is the trend real?”: it is “is the trend already priced in?”.
The “small cap premium”, higher returns for smaller firms compensating higher risk, was documented by Fama and French (1992, Journal of Finance) as one of the most robust factors in empirical finance. From 1926–2010, US small caps outperformed large caps by ~2% per year on average (Ken French Data Library).
Since 2010, this premium has disappeared. The Russell 2000 underperformed the S&P 500 by a wide margin between 2010 and 2024 (Russell Investments), and the Russell 2000 / S&P 500 ratio touched multi-year lows in 2024. Structural explanations: the rise of passive investing concentrates flows in large-cap indices (S&P 500, MSCI World) → small caps, under-represented in these indices, receive proportionally fewer flows. Financing conditions weigh more heavily on small caps (credit access, refinancing costs): in high-rate regimes, small caps with weaker balance sheets suffer more than investment-grade large caps.
Yet small caps retain a powerful cyclical property: early in recoveries, operating leverage amplifies earnings rebounds, the Russell 2000 clearly outperformed the S&P 500 between November 2020 and March 2021 (Russell). The Russell 2000 as a cycle signal analyzes this property and what it reveals about liquidity conditions.
Factor ETFs: a systematic approach, with cyclical limits
Factor ETFs (smart beta) provide systematic exposure to risk factors identified by academic research: value, momentum, quality, low volatility, size. Unlike sector ETFs, they select stocks across sectors using quantitative rules. Global smart beta AUM exceeds $1.5 trillion (ETFGI, 2024).
Each factor has favorable and unfavorable regimes. Momentum (buying trending stocks) benefits from lasting trends but suffers “momentum crashes” during regime shifts: the Ken French Data Library momentum factor lost almost 43% in two months, April and May 2009. Quality (strong balance sheets, high margins) outperforms late cycle and in contractions: quality firms resist slowdowns better. Minimum volatility systematically underperforms in rallies but protects in downturns, as in 2022 (MSCI).
The value factor endured its longest underperformance in history: from its end-2006 peak, its cumulative index lost more than half its value through 2020 (Ken French Data Library), then rebounded by 22 points vs growth in 2022. Smart beta ETFs provide subtle signals on institutional positioning: factor flows reveal regime expectations.
The sector inflation analysis identifies winners and losers across inflation scenarios. The US outperformance study decomposes sector vs geographic effects. The AI ETF risks document valuation distortions driven by thematic flows. The choice between global ETFs and geographic ETFs is analyzed as a structural allocation decision.
← Back to pillar page Equities & ETFs
Last updated — 29 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Artificial Intelligence ETFs: The Risks Investors Tend to Overlook
Artificial intelligence ETFs attract massive flows, but conceal risks that are often underestimated: high concentration on a few…
AI-Themed ETFs: Hidden Concentration Risk in a Positive Real Rate Regime
Why this article matters This analysis breaks down AI-themed ETFs beyond the purely technological angle, by crossing flow…
Dividends and share buybacks are the two channels through which companies return capital to shareholders. These flows, often…