
Equity Market Valuation: Real Rates, Multiples and Earnings Dynamics
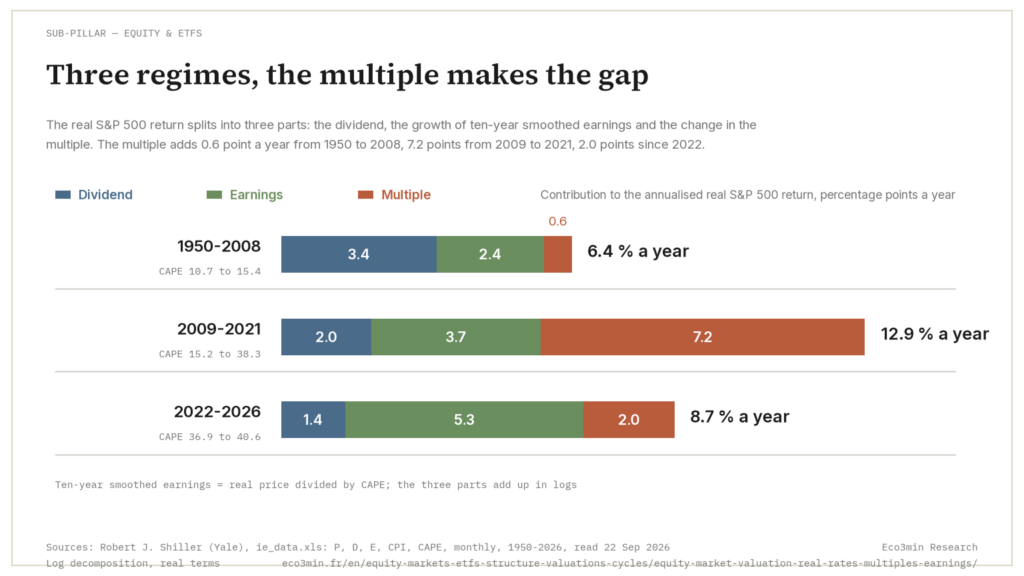
This page extends the analysis of the pillar Equities & ETFs. It formalizes the structural equity market valuation framework: performance decomposition, the relationship between real rates and multiples, earnings dynamics, and the equity risk premium. Eco3min maps this dynamic in our analysis: Equity Markets and the Economic Cycle: The Anticipation Mechanism. The Cycles & Expectations sub-pillar addresses the divergence between equity markets and the real economy; this page focuses on valuation mechanics themselves.
Valuations are not moral judgments about markets. They are a function of the monetary regime and the expected earnings trajectory. A P/E of 25 is neither “expensive” nor “cheap” in isolation: it is coherent or incoherent with a given level of real rates, expected earnings growth, and risk premium. Assessing a valuation without specifying the regime it belongs to is as meaningless as judging a temperature without specifying the scale.
The question structuring this sub-pillar is not “is the market expensive?”; it is: in which regime of real rates, earnings, and risk premium does the market operate, and are current valuations consistent with that regime?
The fundamental decomposition: the structuring equation
All equity performance decomposes into three components, and only three:
Total equity return ≈ Earnings growth + Multiple change + Dividends
Where multiple change itself decomposes into:
Multiple change ≈ Change in real rates + Change in the equity risk premium
This decomposition is not an academic exercise: it is the framework that diagnoses the nature of any equity performance. The S&P 500 delivered a 10.3% annualized total return between 1950 and 2024 (Ibbotson/Morningstar). Of that performance, earnings growth contributed about 6.8% per year (S&P Global, Shiller), dividends a smaller share (S&P Dow Jones Indices), and net multiple expansion the residual. Over the very long term, earnings growth explains more than 80% of total return variation (Bernstein Research). The same logic is developed in our study on Shiller CAPE ratio.
But over short and medium horizons, the timeframes that drive allocation decisions, multiple changes dominate. Between March 2009 and end-2021, the S&P 500 rose spectacularly. Decomposition shows earnings per share rose sharply (FactSet): exceptional growth but explaining only half the performance. The other half came from multiple expansion: forward P/E rose to 23× (FactSet), driven by the decline in real rates from +2% to −1.19% (Federal Reserve). In other words, half the rally was not fundamental wealth creation: it was a mechanical effect of the monetary regime.
Understanding this decomposition explains why the same market can deliver radically different outcomes depending on the prevailing real rate regime, and why extrapolating expected returns from 2009–2021 amounts to projecting a regime that no longer exists.
Real rates and multiples: the structuring relationship
Real interest rates, nominal rates adjusted for expected inflation, are the dominant determinant of valuation multiples. The inflation-expectations regime that shapes these real rates is examined in the complete guide to inflation. The mechanism is direct: future earnings are discounted at the market real rate. When that rate declines, the present value of future earnings rises mechanically: multiples expand. When it rises, present value falls: multiples compress.
The empirical relationship is unambiguous. The S&P 500 forward P/E and the 10-year real yield (TIPS) show a significant negative correlation over 2003–2024 (FactSet, Federal Reserve). Concretely: every increase in the 10-year real yield has historically been associated with a compression in forward P/E (Goldman Sachs, 2023). The swing in real rates between August 2021 (−1.19%) and October 2023 (+2.40%) mechanically implied a sharp P/E compression, and the market indeed saw forward P/E contract markedly (FactSet), in line with that estimate.
This sensitivity is not uniform. “Long-duration” equities, whose cash flows lie far in the future, are most vulnerable to discount-rate shifts, just like long-dated bonds. The Goldman Sachs Non-Profitable Technology Index fell 75% between its February 2021 peak and December 2022 (Bloomberg), because these firms generate no current earnings: valuations depend entirely on distant cash flows whose present value collapses when rates rise. By contrast, firms with stable present earnings (value, dividend, defensive sectors) proved more resilient: in 2022, the S&P 500 Value clearly outperformed the S&P 500 Growth (S&P Global). A related perspective: our study on the U.S. share of the world stock market and the 50% record.
The rate that matters is the anticipated real rate, not the policy rate. A nominal cut that leaves expected real rates unchanged barely alters the fundamental value of future cash flows, which is why monetary easing can coincide with valuation corrections. The discount rate also carries a term premium, compensation for uncertainty about future real rates and the inflation path. When that uncertainty rises, the premium widens and valuations compress beyond what observed real-rate moves alone would justify. A policy cut accompanied by a wider term premium can thus amount to a net tightening of financial conditions: the effective discount rate reads off the whole real yield curve.
The channel reaches beyond listed equities. Commercial real estate, infrastructure and private equity are discounted by the same mechanism, with a lag, and the exit from a regime of negative real rates exposes the distortions it had built into their valuations as well.
The transmission is not proportional. Historically, the shift from negative to positive real rates has been a major tipping point, and between 2021 and 2023 that crossing coincided with a sharp repricing of many growth segments. The 10-year real yield reached a 2022 peak of 1.74% on 3 November, then 2.68% on 16 September 2026, a level last seen in November 2008 (FRED, DFII10).
The nominal level matters as well. The same real rate weighs more heavily on indebted companies when it comes with higher inflation, because they refinance at a higher nominal rate: balance sheets carry more, and the capacity for buybacks or distributions shrinks, independently of the discounting effect. The real yield curve adds a signal of its own. An inverted real curve typically points to future growth tensions and often anticipates rate cuts, while a sharp steepening can reflect inflation expectations unfavourable to equities.
This reading fits within the framework developed in the Monetary Policy & Rates pillar.
The equity risk premium (ERP), the excess expected return of equities over government bonds, is the second determinant of multiples and the most direct gauge of market risk positioning. Which government bond is not a detail: measured against the 2-year rather than the 10-year Treasury, the equity risk premium flips sign in 68 months of the sample.
Operationally, ERP equals the earnings yield (inverse P/E) minus the 10-year real yield. With a forward P/E of 20× (earnings yield 5%) and a 10-year TIPS yield of +2%, the implied ERP is 3%. The long-term historical average ERP in the US is around 4.5–5% (Damodaran, NYU Stern). Documentation: Aswath Damodaran’s equity risk premium data (NYU Stern). An ERP of 3% signals modest compensation for equity risk: consistent with an optimistic backdrop but leaving little margin for error. More context: Earnings revisions as a leading equity signal.
ERP evolution across recent regimes is revealing. During QE (2012–2019), ERP stayed relatively elevated (4–6%) despite rising multiples, because real rates near zero preserved a comfortable gap between earnings yield and risk-free rates. By late 2021, at the bubble’s peak, implied ERP fell below 3% (Damodaran): a level offering minimal risk compensation, signaling extreme complacency. By end-2024, with forward P/E near 21× (earnings yield ~4.8%) and real rates above +2%, implied ERP returned near 2.8%: historically low, embedding strong earnings growth assumptions with limited safety buffer.
Comparing today’s P/E to the historical average (16–17×) to conclude “the market is expensive.” The 16× average reflects eras with real rates around +2%, inflation at 3–4%, and technology under 10% of index weight. Comparing current P/E to that average without adjusting for rate regime, sector composition, and margin levels is analytically meaningless. ERP, which embeds these variables, is a far more reliable gauge of relative expensiveness.
The earnings cycle: long-term engine, short-term volatility source
If multiples drive short-term performance, earnings drive long-term performance. Over horizons of 10+ years, earnings per share growth explains more than 80% of S&P 500 total return variation (Bernstein Research). No multiple expansion can sustainably offset stagnant profits, and no multiple compression can prevent a market with growing earnings from advancing over a decade. Averaging a full decade of inflation-adjusted earnings, the Shiller CAPE ratio of the S&P 500 carries that long-run earnings logic into a valuation multiple.
Why profits swing more than the economy
An equity is a residual claim on a company’s future profits, paid after wages, interest and taxes. That position amplifies: shifts in revenue or costs produce much larger shifts in what is left for shareholders, which is why modest economic variations can generate disproportionate market moves. An economy can grow with stagnant margins if revenue gains are absorbed by rising wages or commodity prices. Conversely, zero growth combined with lower unit costs can still support earnings.
Two channels loosen the link with domestic activity further. Large US-listed companies generate a growing share of their revenue outside the United States, so index earnings can hold up while the US economy slows, provided Asian or European demand stays firm. Earnings also react faster to financial conditions than to final demand. Easier credit or lower rates cut interest expense at once and make share buybacks cheaper to finance, supporting earnings per share independently of real activity. Between 2019 and early 2020, despite a perceptible slowdown, S&P 500 earnings held up on favourable financing conditions and large buyback programmes.
Margins: record highs and sustainability
S&P 500 net margins reached a record in 2021 (FactSet), far above the averages of the 1990s–2000s. This expansion reflects structural shifts: tech sector rise (25–35% net margins for mega-caps), platform scale effects, optimized global value chains, and higher operating leverage. By end-2024, net margins remained high (FactSet): well above historical norms but slightly below peak.
Margin sustainability is structurally decisive for valuations. If current margins represent a “new normal”, supported by sector composition (the tech sector’s large weight in the index) and near-zero marginal-cost models, current earnings levels are sustainable and multiples justified. If margins revert toward historical means (due to wage pressure, deglobalization, regulation, or competition) earnings are overstated and valuations doubly fragile (simultaneous margin and multiple compression). The sector-differentiated impact of inflation is a key determinant of this sustainability.
Pricing power: the dividing line in inflationary regimes
In structurally higher inflation regimes, the central diagnosis of the Macroeconomics & Geopolitics pillar, pricing power becomes the key discriminator between firms that preserve margins and those that suffer erosion. Quasi-monopolies (ASML in lithography, TSMC in foundry), network platforms (Alphabet, Meta), and essential inelastic goods producers (energy, healthcare) possess structural pricing power enabling cost pass-through without demand destruction.
By contrast, highly competitive, low-differentiation sectors exposed to substitutes (physical retail, transport, construction) face margin compression during inflation. This dichotomy partly explains performance concentration in the current regime: pricing power is the market’s implicit selection filter under rising cost environments. The same handful of firms is now also where capital spending concentrates, on the scale of Big Tech’s $1.1 trillion AI capex programme of 2025–2026.
Earnings revisions: the most reliable leading signal
Earnings revision dynamics, not absolute results, empirically provide the most reliable 3–12 month equity performance signal. Direct extension: earnings Revisions and Market Reversals: Reading the Equity Cycle Early. The revision ratio (upward revisions divided by total revisions) has consistently anticipated S&P 500 inflection points with a lead of several months (FactSet, Citi Earnings Revision Index). When this ratio falls below 0.50, indicating most analysts revise downward, the probability of S&P 500 underperformance over the next six months becomes high (Citi Research).
An important feature is asymmetric market reaction to earnings surprises across regimes. In abundant liquidity regimes (2020–2021), positive surprises were richly rewarded and disappointments quickly absorbed: markets forgave. In positive-rate regimes (2022–2024), negative surprises are severely punished (sharp same-day declines for large caps missing expectations, FactSet) while positive surprises receive modest rewards: markets demand. This behavioral shift marks regime change. Revisions as false stability signals and earnings surprises under regime change are covered in dedicated articles.
Valuation ratios: tools and limits
Valuation ratios are essential tools: provided they are used properly, meaning interpreted within the rate regime, cycle phase, and sectoral context. No ratio is self-sufficient.
The forward P/E, price relative to next-12-month expected earnings, is the most widely used professional metric. The median S&P 500 forward P/E over 1990–2024 (FactSet) serves as a benchmark. But this median misleads without context: forward P/E reached a very high level in March 2000 (dot-com bubble), fell very low in March 2009 (financial crisis), rose to 23× end-2021 (QE peak), and fell sharply again in October 2022 (tightening). Same ratio, four regimes: four meanings.
The Shiller CAPE (Cyclically Adjusted P/E), price relative to 10-year inflation-adjusted average earnings, neutralizes cyclical earnings effects. The long-run CAPE average since 1881 is 17 (Shiller). This point is examined further in the Shiller CAPE and long-term valuation. By end-2024 it exceeds 35: a level historically preceding weak real returns over the following decade (Shiller, Research Affiliates). But CAPE has limits: it does not adjust for sector composition (the growing weight of tech), margin levels, or rate regimes. Its value lies in signaling optimistic pricing, not timing.
EV/EBITDA, enterprise value relative to operating earnings before depreciation and amortization, enables cross-capital-structure comparisons and is less sensitive to accounting distortions than P/E. Median S&P 500 EV/EBITDA (Bloomberg) is a common benchmark. It is especially useful in capital-intensive sectors (industry, energy, telecoms) and cross-Atlantic comparisons (European firms may show similar P/E but higher EV/EBITDA due to leverage).
In listed software, a fourth ratio has become the implicit anchor: EV/ARR, enterprise value relative to annual recurring revenue (subscriptions and multi-year contracts billed on a recurring basis). ARR measures volume, not profitability. The same base can belong to a company already generating cash or to one still burning cash to hold it, and aggressive discounts or lower-margin renewals can keep ARR rising while future profitability erodes. During 2020–2021, with policy rates close to 0% in advanced economies, many models extrapolated ARR as a quasi-perpetual flow discounted at a very low cost of capital. The federal funds target range was raised to 5.25–5.50% in July 2023 and the ECB deposit rate to 4% in September 2023; they still stood at 3.75–4.00% and 2.50% on 6 October 2026. A given level of ARR no longer carries the same present value, especially when the company is still consuming cash, which is why net revenue retention, churn and free cash-flow margin say more about the figure than the multiple alone.
The link between corporate earnings and equity markets and the weak direct correlation between GDP growth and stock performance are explored in dedicated articles.
Three valuation regimes since 2009
The interaction of real rates, earnings, and risk premium has produced three distinct valuation regimes since the global financial crisis. our study on earnings Surprises and Financial Regime Shifts retraces the successive episodes.
2009–2019: multiple expansion driven by real rates
S&P 500 forward P/E rose sharply between March 2009 and end-2019 (FactSet). This expansion primarily reflected declining real rates toward zero and the TINA regime (There Is No Alternative) pushing investors into equities. ERP remained comfortable (4–6%, Damodaran) because near-zero real rates preserved reasonable spreads with earnings yield even at high multiples. Shiller CAPE rose from 13 to 31, doubling, signaling historically stretched valuations but justifiable under the rate regime. Judging a reading of 31 against the rate regime means setting it beside the real yield of the day, the pairing behind the dataset that tracks US real interest rates against the CAPE ratio since 1963.
2020–2021: the apex, deeply negative real rates, compressed ERP
Deeply negative real rates (10-year TIPS −1.19% in Aug-2021, Federal Reserve) propelled multiples to historical extremes. Forward P/E reached 23× (FactSet). CAPE exceeded 38: above the 2000 peak (Shiller). Implied ERP fell below 3% (Damodaran), indicating minimal equity risk compensation. Investors effectively paid prices that no longer compensated risk. This valuation regime depended entirely on sustained negative real rates: a condition removed in 2022. A broader view: the market exposure of unit-linked supports.
2022–?: structural repricing, then reconcentration
2022 tightening triggered the sharpest multiple compression since 2008. Forward P/E contracted sharply within months (FactSet). Then a notable development occurred: P/E rebounded toward 20–21× by end-2024 despite real rates remaining above +2%. This apparently contradictory re-expansion reflects concentration: the Magnificent 7, with very fast earnings growth (FactSet), lift average multiples through composition effects. Forward P/E of the S&P 493 (excluding Magnificent 7) sits markedly lower (Goldman Sachs): consistent with positive real rate regimes. The “expensiveness” of the S&P 500 is largely a composition artifact, not necessarily a broad bubble signal. Full series: Our study on the Buffett indicator of market cap to GDP since 1947.
This configuration creates a different risk: extreme index valuation sensitivity to the earnings trajectory of a handful of firms. If Nvidia, Apple, or Microsoft earnings disappoint, or AI monetization expectations reset, multiple compression in those names alone could drag the entire index lower, even if the broader market remains reasonably valued.
A market is neither expensive nor cheap in isolation. It is coherent or incoherent with a given real rate regime and earnings trajectory. Total equity performance decomposes into earnings growth, multiple change, and dividends. Over the long term, earnings dominate. Over the short term, multiples dominate, and multiples are a function of real rates and risk premium. In negative real rate regimes, multiples expand and a P/E of 23 can be justified. In +2% real rate regimes, a P/E of 21 is justified only with exceptional earnings growth: precisely what the Magnificent 7 deliver, and upon which overall index valuation sustainability now depends. The relevant diagnosis is not “is P/E above average?” but “do real rates, earnings trajectory, and implied risk premium form a coherent set, and what conditions would break that coherence?”. A complementary secular-valuation lens appears in the S&P 500 priced in gold as a secular equity-valuation gauge.
Further reading
GDP growth and stock market performance: Why correlation is far weaker than commonly assumed.
Inflation and sector-differentiated effects: Pricing power as the selection filter in inflationary regimes.
When bad news is good news for markets: Monetary expectations mechanics in data reactions.
← Back to pillar page: Equities & ETFs
Last updated — 3 November 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Earnings Surprises and Financial Regime Shifts
Earnings surprises reveal far more than a quarterly miss. They are an early indicator of the shift from…
The Limits of the CAPE: What Siegel’s Critique Changes
Recomputed on national-accounts profits, as Siegel proposes, the CAPE stood at 1.56 times its historical mean in June…
Formalized by Shiller, Black and Jivraj in their 2020 paper "CAPE and the COVID-19 Pandemic Effect," the Excess…