
Why Crypto Is So Volatile: Structural Drivers and Liquidity Regimes
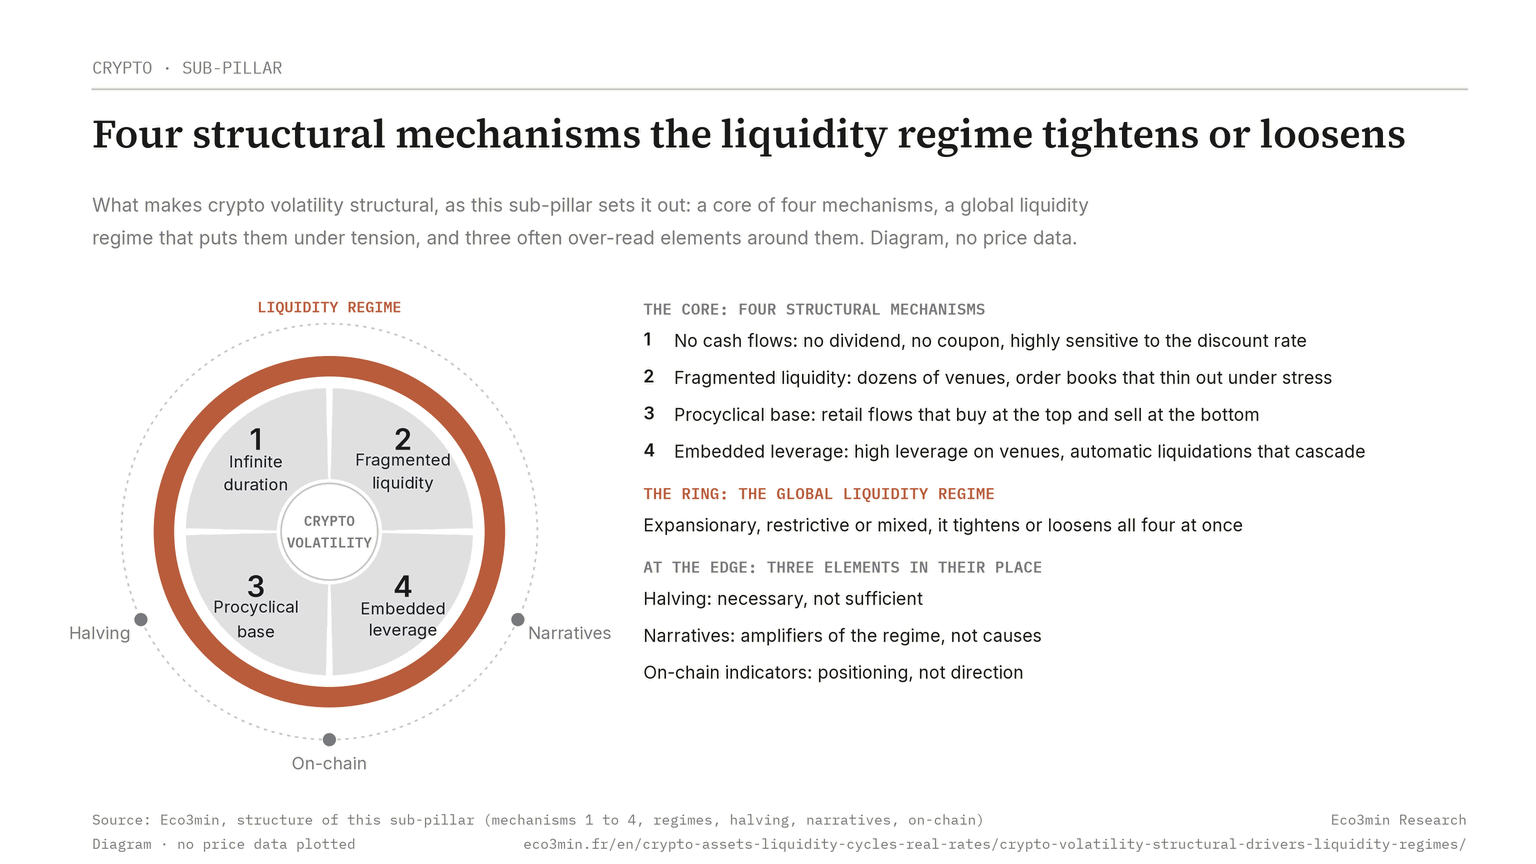
Crypto-asset volatility is not a temporary bug that will disappear as markets mature: it is a structural feature. An asset with no cash flows, a highly volatile investor base, liquidity that evaporates under stress, and a valuation entirely dependent on the global liquidity regime will structurally be more volatile than an asset that pays dividends, attracts pension funds, and benefits from bond-market dealers. Understanding this volatility means understanding why crypto cycles are several times more violent than equity cycles, and why they will remain so.
Bitcoin: annualized volatility of at least 60% over 2020–2024 (Bloomberg), several times that of the S&P 500, gold or ten-year Treasuries; Ethereum and the main altcoins are more volatile still. Solana lost most of its value between November 2021 and December 2022, then soared between January 2023 and March 2024. No traditional asset class produces comparable amplitudes. The question is not “why are crypto assets volatile?”: volatility is the logical consequence of their nature. The real question is: which structural mechanisms generate this volatility, and how do those mechanisms interact with the global liquidity cycle?
Four structural mechanisms: none fixable in the short term
1. No cash flows = infinite duration. Bitcoin pays neither dividends nor coupons. Its valuation depends entirely on expectations of future demand. This absence of cash flows makes it akin to an infinite-duration asset: the category most sensitive to changes in discount rates. When 10-year real TIPS yields move from -1.19% (Aug 2021, Fed) to +2.40% (Oct 2023), a 10-year duration asset loses ~25%. An infinite-duration asset theoretically loses far more, and Bitcoin indeed lost more than three quarters of its value between November 2021 and November 2022. The Real Policy Rates sub-pillar formalizes this sensitivity.
2. Fragmented and procyclical liquidity. Crypto assets trade across dozens of venues (Binance, Coinbase, Bybit, OKX, Kraken, plus DEXs) with fragmented order books. The bid-ask spread on Bitcoin, very tight in normal times on the major venues (Kaiko Research), widened sharply under stress (May 2022, Terra collapse); on altcoins, it becomes wide enough to make rational execution nearly impossible. Liquidity available in normal times disappears precisely when it is needed, and far more than in equity markets, where S&P 500 spreads also widen under stress, but much less.
3. Investor base dominated by procyclical retail flows. In equity markets, pension funds (~$4.1T US DB plans, Federal Reserve), insurers, and long-term institutional investors absorb shocks and dampen volatility: they are structurally countercyclical (target rebalancing). In crypto markets, despite the arrival of spot ETFs, the investor base remains retail-dominated (Binance and Coinbase each claim more than a hundred million accounts), with strongly procyclical behavior. Retail crypto flows mirrored retail equity flows (ICI data) but amplified: peak buying at the top (Nov 2021), peak selling at the bottom (Nov 2022).
4. Cascading liquidations, embedded leverage. Crypto platforms offer 5–100× leverage (Binance Futures, Bybit, OKX). When Bitcoin falls 5%, 20× leveraged long positions are liquidated → forced selling amplifies declines → triggers new liquidations → cascade. March 2020: $1.6B liquidated in 24h on BitMEX (BitMEX). In May 2021 (Elon Musk tweet, China crackdown) as in August 2024 (Nikkei flash crash, carry trade unwind), daily liquidations exceeded one billion dollars (Bybit, CoinGlass). This embedded leverage mechanism does not exist at comparable scale in regulated equity markets (margin calls handled by clearinghouses with 24–48h windows, not instant auto-liquidations). Instant auto-liquidations, absent from equity clearing, are much of what sets crypto cyclical volatility versus equities. The comparative crypto vs equities cycle analysis details these asymmetries. More context: our analysis of stablecoin run dynamics as systemic stress signals.
Anatomy of a crypto cycle: 4 phases
Crypto cycles follow a recurring sequence with striking regularity, though precise timing remains unpredictable. Data from the 2020–2023 cycle (the most documented) illustrates each phase.
Phase 1: Accumulation (Nov 2022 → Mar 2023). BTC trades far below its peak, in a narrow range (CoinGecko). The MVRV ratio (Glassnode) indicates that the average holder sits on unrealized losses. Spot volumes at their lowest since 2020. Media interest collapsed (Google Trends “Bitcoin”: 15/100 vs 100 in Nov 2021). Exchange outflows dominate (BTC moved to cold storage → accumulation signal, Glassnode). “Smart money” accumulates while retail has capitulated. NUPL (Net Unrealized Profit/Loss) in negative territory: historically associated with cycle bottoms.
Phase 2: Early uptrend (Mar 2023 → Oct 2023). BTC recovers markedly. Catalysts: anticipation of spot ETFs (BlackRock filing, June 2023). On top of that, net Fed liquidity improved: the reverse repo fell by $1.5T, a net injection. Moderate volumes. Limited media coverage. Prevailing skepticism. MVRV rebounds into the neutral zone. Long-term holders (>1 year) do not sell (Glassnode LTH Supply stable).
Phase 3: Euphoria (Nov 2023 → Mar 2024). BTC more than doubles. Catalyst: spot ETF approvals in January 2024, followed by massive net inflows in the following months (Bloomberg). The displayed liquidity of these spot ETFs in euphoric phases can mask structural fragility in the intermediation chain under stress: see our analysis of ETF liquidity during market drawdowns. IBIT (BlackRock) posts the fastest start ever recorded for an ETF (Bloomberg). Altcoins soar, led by Solana. Google Trends “Bitcoin” rebounds to 80/100. MVRV enters the historical overvaluation zone. Long-term holders begin distributing (Glassnode LTH Supply declines). Memecoins (PEPE, WIF, BONK) rise tenfold or more, a classic late-cycle euphoria signal.
Phase 4: Capitulation (each cycle, similar magnitude). In previous cycles, BTC lost more than three quarters of its value, in 2018 as in 2022, and altcoins most of theirs (ETH in 2018). Capitulation systematically coincides with tightening global liquidity: crypto cycles do not collapse in isolation; they collapse when the macro regime turns.
On-chain indicators: reading positioning, not predicting price
Blockchain transparency provides a unique analytical edge, but is often overinterpreted. On-chain indicators describe participant positioning; they do not predict the macro regime that determines direction.
MVRV (Market Value / Realized Value): market cap ÷ average acquisition cost of all BTC. MVRV >3.5: historical distribution zone (Mar 2021: threshold crossed, then BTC corrected by half). MVRV <1.0: accumulation zone (Nov 2022: confirmed cycle bottom). Limitation: MVRV at 2.5 can persist for months before reversal, not a mechanical signal. NUPL (Net Unrealized Profit/Loss): aggregate unrealized P/L of holders. >0.75: euphoria (historical selling zone). <0: capitulation (historical accumulation). Exchange flows: BTC inflows (deposits to sell) vs outflows (withdrawals to cold storage = accumulation). In 2023–2024: dominant outflows (Glassnode), structural accumulation confirmed.
Macro overlay is what differentiates Eco3min analysis. An MVRV below 1 (on-chain undervaluation) combined with accelerated QT and rising rates (unfavorable macro regime) can remain depressed for months, positioning signals the bottom, the regime determines when rebound begins. The same MVRV combined with a Fed pivot triggers rapid repricing. On-chain metrics without macro context are incomplete tools: crypto cycles are governed by global liquidity (very high BTC/Fed net liquidity correlation over 2020–2024), not internal protocol metrics.
Crypto cycles and macro regimes: the structural dependency
The most common mistake in crypto analysis is treating cycles as endogenous: driven by halving, adoption, or technology. In reality, Bitcoin’s correlation with global liquidity (Fed net balance sheet: total assets − Treasury account − reverse repo) is very high over 2020–2024 (Federal Reserve, CoinGecko). This is Bitcoin’s highest correlation with any macro indicator, stronger than its correlations with the Nasdaq, gold or the dollar (DXY).
Three regimes identified:
Expansionary regime (QE + zero rates): Mar 2020 → Nov 2021. Fed balance sheet $4.2T → $8.97T. Fed funds 0.25%. TIPS -1.19%. M2 +40% in 18 months. BTC rises more than tenfold, ETH far more. In this regime, Bitcoin markedly amplifies risk-asset gains.
Restrictive regime (QT + rate hikes): Nov 2021 → Nov 2022. QT launched ($95B/month runoff). Fed funds 0% → 4.00%. TIPS -1.19% → +1.72%. BTC and ETH lose more than three quarters of their value, altcoins even more. FTX, Celsius, Terra, Three Arrows → bankruptcies. Liquidity contraction did not cause frauds; it exposed them (Buffett: “Only when the tide goes out do you discover who’s been swimming naked”). What the tide also exposed was where those platforms were domiciled, a geography examined in the concentration of the crypto industry in a handful of hubs.
Mixed regime (QT ongoing + rising net liquidity): Nov 2022 → Mar 2024. Fed balance sheet declines ($8.9T → $7.5T), but reverse repo falls $2.5T → $0.5T → ~$2T net liquidity injected. BTC more than quadruples. The driver is not the gross balance sheet but net liquidity. The Liquidity & Financial Conditions sub-pillar is essential for interpreting crypto cycles. The liquidity and rates cycle analysis formalizes the relationship.
Halving: necessary but not sufficient, and not the dominant driver
Halving cuts new BTC supply by 50% roughly every four years. After the April 2024 halving: issuance fell from ~900 BTC/day to ~450 BTC/day. Relative to daily spot market volumes (CoinGecko), this reduction is a tiny fraction of trading. Mechanical price impact is arithmetically modest.
History: After each of the 2012, 2016 and 2020 halvings, BTC multiplied several times over in the following twelve to eighteen months. Striking sequence, but all three halvings coincided with highly favorable liquidity regimes. 2012: QE3 ($85B/month purchases). 2016: Fed funds 0.50%, massive ECB/BoJ QE. 2020: unlimited QE, zero rates, $5T fiscal stimulus. The 2024 halving occurs with Fed funds at 5.25%, TIPS +2.0–2.5%, QT ongoing: a fundamentally different regime.
Attributing post-halving rallies to halving alone is a classic attribution error (correlation ≠ causation). Halving creates a necessary condition (reduced marginal supply), but the macro regime determines whether it produces meaningful effects. A halving under abundant liquidity and negative rates (2020) yields radically different outcomes from a halving under constrained liquidity and positive real rates (2024). The programmed scarcity analysis deconstructs this link.
Narratives as amplifiers: not causes
Each crypto cycle has dominant narratives: “digital gold” (2020–2021), “Web3” (2021), “DeFi Summer” (2020), “NFTs” (2021–2022), “decentralized AI” (2023–2024). These narratives create focal points that concentrate attention and capital, but they do not explain cycles. The “digital gold” narrative did not protect Bitcoin from a fall of more than three quarters in 2022. The “Web3” narrative did not prevent trillions of dollars in crypto market cap losses.
Narratives function as amplifiers of the prevailing regime, not independent causes. In expansionary regimes (abundant liquidity), narratives channel euphoria into specific sectors: NFTs in 2021 (OpenSea volume collapsed between January 2022 and January 2024, Dune Analytics), memecoins in 2023–2024 (PEPE went from zero to a market cap on the order of a billion dollars within weeks, CoinGecko). In restrictive regimes, narratives protect nothing: crypto AI projects (FET, RNDR, TAO) fell sharply in each 2024 correction despite intact narratives. The AI altcoin analysis documents these dynamics.
The crypto vs equities cycle comparison quantifies structural asymmetries. The liquidity and rate cycle study formalizes the BTC/monetary conditions relationship. The programmed scarcity analysis deconstructs the link between fixed supply and price formation.
← Back to the pillar page Crypto-assets
Last updated — 6 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Crypto Seasonality: Why the Signal Is Weaker Than It Looks
Crypto’s cyclical regularities, monthly seasonality or the four-year cycle, rest on a very small number of observations. That…
Bitcoin Halving: How the Programmed Supply Cut Works
The halving writes bitcoin’s scarcity into an immutable rule, applied without exception since 2012. It shapes the pace…
Crypto Cycles: Why Their Amplitude Dwarfs Equity Swings
From cycle peak to trough, bitcoin lost more than three quarters of its value in each of its…