
Financial Innovation, Market Infrastructure and Systemic Risk
Technologies, infrastructures, and new economic models: the structural transformations reshaping capital flows, market architecture, and risk transfer.
Financial innovation is not measured by novelty: it is judged by its ability to reduce individual frictions without creating collective fragilities.
Financial innovation becomes systemic when it homogenizes behaviors, turning individual efficiency gains into macroeconomic fragilities during periods of stress. Every major crisis of the past 30 years involved a financial innovation that functioned perfectly in normal times.
Index ETFs sharply reduced management fees (Morningstar). They then concentrated 30% of the S&P 500 into a handful of companies (Magnificent 7, S&P Global 2024), creating an invisible concentration risk rooted in how passive management allocates capital through index weighting mechanisms. Algorithmic trading reduced bid-ask spreads from 6 cents to the role of clearing houses in derivatives markets becomes structural.
This sub-pillar analyzes financial innovation not as linear progress but as a friction transformation mechanism: every friction eliminated is replaced by a new fragility, often invisible until the next crisis. The analysis focuses on tools, technologies, and business models transforming intermediaries and infrastructure. Monetary and global liquidity issues belong to the Monetary Policy pillar; decentralized monetary architectures to the Crypto-Assets pillar.
What distinguishes structural innovation from hype
A financial innovation is not merely a new technology; it combines three elements: a technical infrastructure that reduces frictions, a viable business model, and real adoption by users or institutions. An innovation that fails any of these three criteria remains experimental or speculative.
An innovation only “passes” when all three hold together
Remove a single one and the innovation stays experimental or speculative: this filter is what separates a structural shift from hype.
Technical infrastructure
A mechanism that genuinely reduces a friction: automated index replication, microsecond latency, instant settlement, distributed ledger.
Viable business model
An economics that holds at scale, without permanent subsidy: fees sustainable by volume, reduced float costs, profitable market making.
Real adoption
Observable mass usage, not a promise: $11T in ETF assets, 60-70% of US equity volume, 30% of SEPA transfers, versus <$1B in non-crypto tokenized assets.
Examples that pass the filter: ETFs (infrastructure: automated index replication; model: low fees viable at scale; adoption: $11T global AUM, ETFGI 2024). Instant payments (infrastructure: SEPA Instant, FedNow; model: reduced banking float costs; adoption: 30% of SEPA transfers in 2024, ECB). Algorithmic trading (infrastructure: co-location, microsecond latency; model: automated market making; adoption: 60–70% of US equity volume, SEC). Examples that do not (yet) pass: real-estate asset tokenization (functional infrastructure; fragile business model; marginal adoption,
Infrastructures that have already transformed the system
Financial infrastructures (historically centralized, slow, and costly) have undergone three measurable structural transformations.
Instant payments: SEPA Instant in Europe (10 seconds, 24/7, €100k cap, ECB), FedNow in the US (launched July 2023, 800+ participating institutions by end-2024, Federal Reserve). Impact: interbank settlement shifts from T+1/T+2 to near-instant, reducing counterparty risk and collateral needs. But settlement time also served as a liquidity buffer: banks had 24–48h to cover funding gaps. With instant settlement, liquidity stress spreads in minutes rather than days. The analysis of instant payments details the impact on bank margins.
Securities settlement cycle reduction: the shift from T+2 to T+1 in the US (May 28, 2024, SEC) reduced counterparty risk estimated at $1.4T/day (DTCC), but compressed margin call windows (48h to 24h), increasing intraday liquidity pressure on participants. Interoperability via open APIs: PSD2 in Europe (2018) forced banks to open customer data access (many fintechs connected via API). The “Banking as a Service” model allows non-banks (Revolut: 35M clients, Apple: Apple Savings) to distribute financial services without a full banking license, transferring credit and liquidity risk to less regulated entities. Risk that moves to a less supervised node does not leave the system, it merely changes address: the reach of an operational outage at a small firm into a systemic market.
The passive revolution: the deepest structural transformation
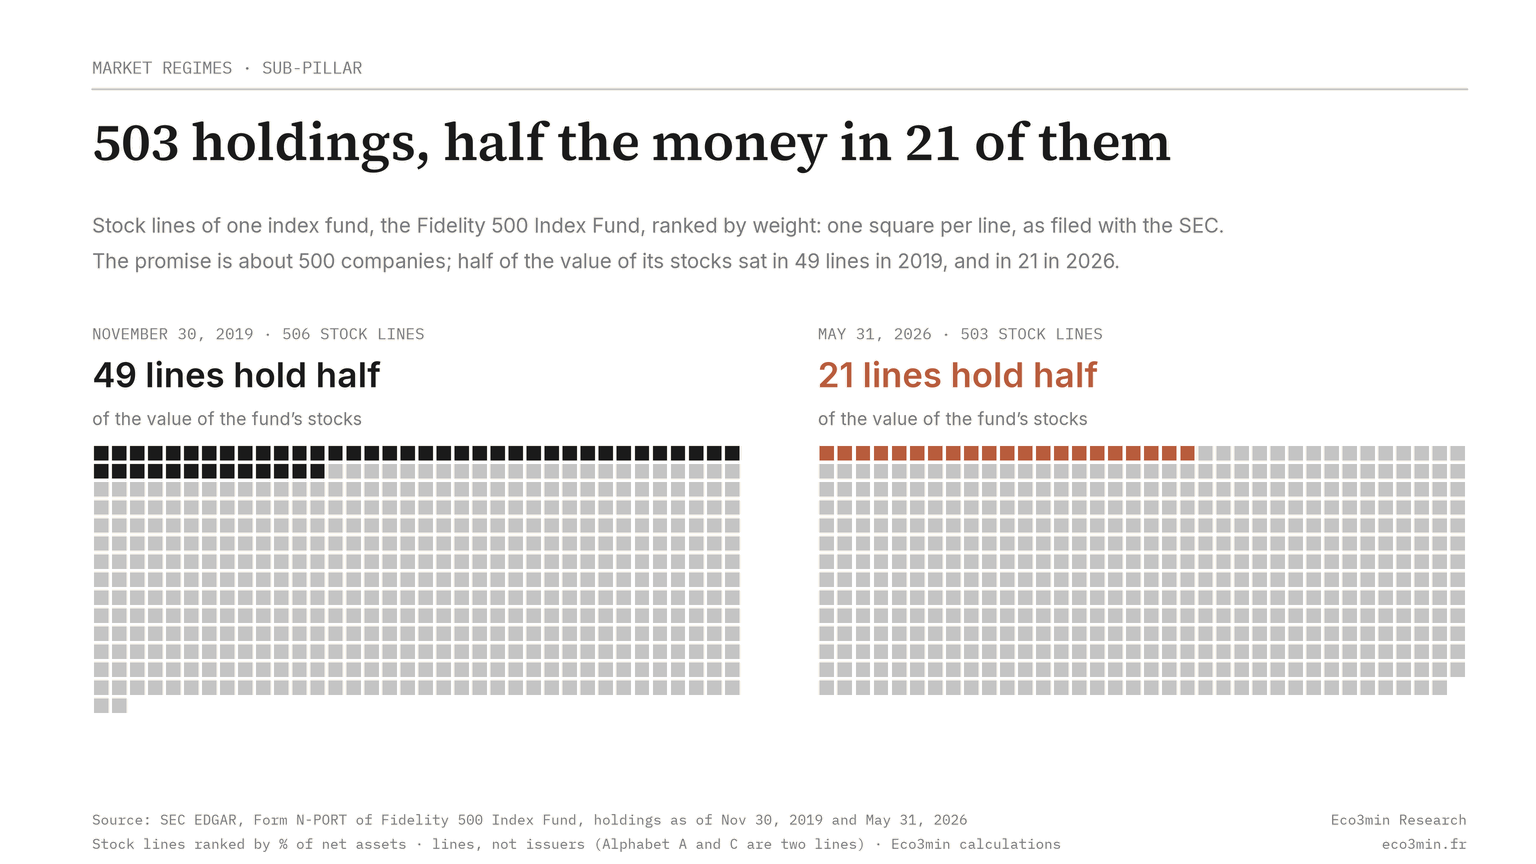
The shift from active to passive management is the most consequential financial innovation of the past 25 years: in scale, impact on price formation, and systemic effects. Global ETF and index fund assets reach considerable levels (ETFGI/Morningstar, 2024). In the US, passive management holds >50% of equity market capitalization (Morningstar). In 2023, US passive funds saw net inflows, while active funds faced outflows (Morningstar). The holdings an index fund files with the SEC show where that money ends up. In the Fidelity 500 Index Fund, half of the value of its stocks sat in 49 of its 506 stock lines on November 30, 2019, and in 21 of its 503 lines on May 31, 2026 (SEC EDGAR, Form N-PORT). See also, on financialization in a commodity market, the role of certified stocks in cocoa futures.
The cost that collapses
Management fees fell sharply between active funds and index ETFs.
- Over the long run, the annual fee gap erodes a notable share of accumulated capital (reverse compounding).
- The vast majority of active funds underperform their benchmark over the long run after fees (SPIVA, S&P Global).
- Net returns for the average investor have objectively improved.
The concentration that builds up
“Blind” flows buy in proportion to index weights, regardless of valuation.
- 30% of every dollar in an S&P 500 ETF flows to the Magnificent 7.
- “I own 500 companies” masks “30% of my capital is in a handful of US tech firms”.
- In outflow episodes, selling is indiscriminate: strong but low-weight firms face the same pressure as distressed ones.
AI and automation: micro gains, macro fragility
Financial artificial intelligence operates on two levels with opposite systemic implications.
Back office (real gains, limited risks): compliance automation (KYC/AML), credit risk modeling, fraud detection. JPMorgan estimates saving a very large number of hours each year via its COIN program (Contract Intelligence, JPM annual report). Global bank compliance costs (~$270B/year, LexisNexis) could be materially reduced through automation. These gains are real and largely uncontroversial.
Front office (ambiguous gains, systemic risks): algorithmic trading (60–70% of US volume, SEC) tightened spreads and reduced transaction costs, but created ephemeral liquidity that disappears within milliseconds under stress. Standardized risk models (VaR, stress tests) homogenize decisions: when 80% of risk desks use similar models, 80% of institutions reduce exposure simultaneously when thresholds are breached, amplifying moves instead of dampening them. The analysis of AI and structural finance transformation develops this micro-gain / macro-fragility distinction. The study on the new financial AI regime examines implications for margins and allocation.
Tokenization and decentralization: the infrastructure / model / adoption test
Asset tokenization, the digital representation of financial or real assets on distributed ledgers, is the innovation with the widest gap between promise and reality. BlackRock launched its tokenized fund BUIDL (March 2024): the first meaningful institutional vehicle. JPMorgan tokenized $300B in repo transactions via its Onyx platform (JPMorgan 2024). Yet non-crypto tokenized assets total
Decentralization as a technical architecture (not as a monetary project, strict editorial boundary with the Crypto-Assets pillar) offers real strengths: native transparency, technical resilience, permissionless access. Limitations are operational: complex governance (who decides when the protocol has a bug?), diffuse liability (who compensates after a hack?, $3.8B stolen in DeFi hacks in 2022, Chainalysis), unstable regulatory frameworks (MiCA in Europe, uncertain SEC classification in the US). Tokenization will likely work for standardized institutional assets (bonds, repo, money market funds): it will remain marginal for complex assets (real estate, private equity) until legal frameworks stabilize.
The valuation trap: when ARR masks the absence of profit
Financial innovation has also transformed valuation metrics themselves, creating analytical blind spots. ARR (Annual Recurring Revenue) has become the dominant metric for valuing fintech and financial SaaS firms. Problem: ARR measures recurring revenue growth, not profitability, not free cash flow, not business model sustainability. In the zero-rate regime (2015–2021), investors paid very high multiples of ARR for unprofitable firms (Adyen: 60× ARR peak 2021, Bloomberg). In a high-rate regime, these multiples compressed sharply (Adyen: marked peak-to-trough decline 2021–2023). Focusing on ARR without factoring cost of capital produced massively inefficient capital allocation: billions directed toward models whose viability depended on a rate regime that no longer exists.
Same fintech, two rate regimes: the ARR multiple inverts
ADYEN CASE · BLOOMBERG · EMPIRICAL OBSERVATIONARR measures recurring-revenue growth, not profitability or free cash flow. Read without the cost of capital, it fueled an allocation massively dependent on a rate regime that no longer exists.
Why homogenization persists once it sets in
The fragility builds through a loss of decisional diversity. In a first phase, broad adoption of comparable “optimised” strategies looks like success: volatility recedes, performance dispersion narrows and flows stabilise, so the calm is read as validation of the model. The same compression can instead be the trace of standardised approaches. It only shows when the cost of capital rises, an exogenous shock hits or expectations are sharply revised, and repositioning then happens in concert on the same segments.
Persistence comes from incentives. Solutions are often adopted because they reduce divergence from peer practice, whatever their intrinsic merit, and the innovation turns into a tacit compliance framework. Departing from it stops being strategic risk-taking and becomes relative risk: appearing less compliant or more exposed than peers. As long as the collective framework holds, alignment offers a form of institutional protection, and no single participant gains from breaking the convergence.
Durably restrictive real rates narrow the room for manoeuvre further, tilting strategies toward short-term optimisation and lower apparent volatility rather than structural adaptation. The mechanism has limits. It supplies neither a crisis calendar nor a turning-point signal, and it does not make every innovation harmful. It describes a condition, mass adoption of the same rules, under which individual efficiency stops guaranteeing collective efficiency.
The central paradox: every friction eliminated creates a new fragility
Financial innovation presents a structural paradox documented by every crisis of the past 30 years: it reduces individual frictions while creating collective fragilities. CDOs reduced mortgage credit costs → but concentrated systemic risk. ETFs reduced management fees → but homogenized allocation behavior. HFT reduced spreads → but made liquidity ephemeral. 0DTE options reduced intraday hedging costs → but created hedging flows that amplify volatility. Applied to bond ETFs, the same trade-off is where hidden fragilities emerge in ETF liquidity and credit.
This paradox is not an argument against innovation: efficiency gains are real and measurable. It is an argument for evaluating each innovation through a dual lens: what individual risk does it reduce? And what systemic risk does it create when widely adopted? Innovations that reduce perceived individual risk while increasing collective risk are the most dangerous, because they accumulate invisible fragility until stress reveals it. When fragility surfaces, moves toward safe havens (dollar, Treasuries, yen) intensify abruptly: precisely because innovations removed shock-absorbing mechanisms.
Three analyses that extend this sub-pillar
AI & structural transformation
The micro-gain / macro-fragility distinction applied to financial artificial intelligence.
Read the analysis →Instant payments
The settlement detail that transforms bank margins and removes a liquidity buffer.
Read the analysis →Asset tokenization
The infrastructure / model / adoption filter applied to the widest promise-reality gap.
Read the study →← Back to the pillar page Financial Markets
Last updated — 20 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Instant Payments: The Detail Reshaping Bank Margins
Instant payments: the real shock building for banks, fintechs, and payment margins across Europe, and what it means…
Volmageddon 2018: when innovation amplifies volatility
Products that rebalance daily turn a rise in VIX futures into forced purchases of more VIX futures, at…
Artificial Intelligence and Systemic Financial Risk
Artificial intelligence is reshaping the architecture of the global financial system. But microeconomic efficiency gains do not automatically…