
Rental Property Returns: From Gross Yield to Net-Net Profitability
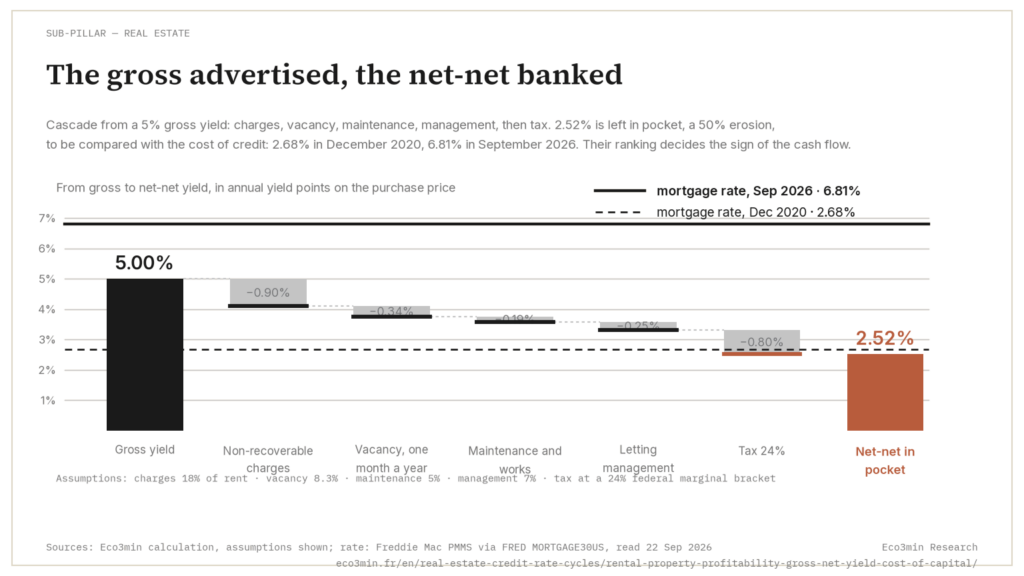
Real estate is not a yield asset: it is a credit asset. The advertised rental yield depends more on the interest-rate regime than on rent levels. A 5% gross yield turns into 2–2.5% net-net after taxes for an investor in an average marginal tax bracket, and that residual depends entirely on financing conditions. When mortgage rates exceed net yield, leveraged rental investment generates negative cash flow. Headline yield is an illusion; only what actually remains in pocket matters.
In January 2022: average mortgage rate in France very low over 20 years (Crédit Logement/CSA Observatory). Average gross rental yield well above the cost of credit (MeilleursAgents/SeLoger). Positive spread: leverage works, borrowing at a very low rate for an asset yielding 3% net creates value. In December 2023: average mortgage rate 4.24% across all maturities (Crédit Logement/CSA Observatory), a much higher level in under two years. Mortgage production collapsed: -40% in volume between 2022 and 2023 (Banque de France). Existing-home prices: -4% nationally, -5 to -8% in Île-de-France (INSEE/Notaries). Number of transactions fell from 1.2 million (2021 peak) to ~870,000 in 2023 (CGEDD/Notaries): a 28% drop.
The same property, the same rent, the same tenant, the same location, but a different rate regime. It is this regime shift that transformed the arithmetic of rental investment, not a deterioration in real-estate fundamentals. Rental yield cannot be read as an isolated ratio: it must be read as the outcome of a chain of economic, tax and financial frictions in which the cost of capital is the primary determinant. The link between credit and asset valuation is the central mechanism: credit as the engine of economic cycles provides the macro framework.
From Gross to Net-Net: 50% Documented Erosion Line by Line
Gross yield, annual rent ÷ purchase price, is the figure highlighted by sellers, developers and tax-optimization platforms. It is also the most misleading. The erosion cascade between gross yield and what actually remains in pocket is fully documentable. That thread runs through the gross-to-net path of US rental returns as well.
Layer 1: Non-recoverable charges (15–25% of gross rent). Property tax: national average ~1 month of rent for a one-bedroom (DGFiP), but large dispersion, €800–1,200/year in provinces, €1,500–3,000 in Île-de-France depending on municipality. Non-recoverable condo charges (owner share: major works, property manager fees, building insurance): 15–25% of total condo fees (ARC/CLCV). Non-occupant landlord insurance: €150–300/year (FFSA). Management fees if outsourced: a percentage of collected rents (FNAIM). Total layer 1: a 5% gross yield falls to 3.8–4.2% after charges. Related reading: how REITs and physical real estate compare.
Layer 2: Vacancy (5–10% of annual rent). Even in tight markets, assuming 100% occupancy is unrealistic. Average reletting delay: 1–3 months between tenants (refurbishment, marketing, screening). Residential vacancy rate in France: 8.3% of total stock (INSEE 2023), highly variable, <3% in inner Paris, 10–15% in cities with demographic decline. Conservative assumption: 1 month vacancy/year = 8.3% loss. Yield after charges and vacancy: 3.5–3.8%. A related comparison of vehicles appears in unlisted real estate funds set against rental property.
Layer 3: Maintenance and works (5–10% of annual rent). Properties age. Repainting: €3,000–5,000 every 5–7 years for a one-bedroom. Equipment replacement (water heater, ventilation, appliances if furnished). Emerging factor: energy-efficiency compliance, properties rated G banned from rental since 2025, F from 2028, E from 2034 (Climate & Resilience Act). Energy-renovation cost: €200–400/m² to upgrade from G/F to D/C (ADEME/France Rénov’). For a 40 m² unit: €8,000–16,000. Prudent annual provision: 5–10% of rents. Yield after charges, vacancy and maintenance: 3.0–3.5%, net yield before tax. The analysis of hidden frictions quantifies each component.
The scissors between rents and costs. The three layers do not stay fixed over time, because rents and operating costs follow different paths. Between 2020 and 2025, French private-sector rents rose 8.6% (Eurostat, HICP actual rentals, annual averages), sometimes held back by rent caps, while energy, maintenance and insurance kept pushing operating costs up. The share of collected rent absorbed by charges therefore rises mechanically, and the gross yield displayed at purchase overstates the net yield a few years later.
Taxation: The Final, and Heaviest, Layer of Erosion
Rental income taxation turns a 3.0–3.5% net yield into a 2.0–2.5% net-net yield for most investors.
Unfurnished rental: real regime: property income taxed at marginal tax rate + 17.2% social contributions. 30% bracket → total levy 47.2%. 41% bracket → 58.2%. 45% bracket → 62.2%. The empirical side is documented in this analysis of estate taxes high net worth. A net property income of €5,000/year taxed at 30% leaves €2,640 after tax: a net-net yield of ~2.0–2.2% on a €120,000–150,000 purchase price. How listed real estate absorbs rate moves extends this reading to securitized real estate. Micro-property regime: flat 30% allowance on gross income (cap €15,000/year), simpler but rarely optimal if charges are high.
Furnished rental: LMNP status: more tax-efficient thanks to accounting depreciation of the property (excluding land), furniture and works. Depreciation creates a deductible non-cash expense: taxable income often nil or very low for 20–30 years. Trade-offs: mandatory business accounting (cost €300–800/year), heavier management (inventory, faster wear, more frequent turnover). The LMNP advantage is real but conditional: it defers taxation; it does not create yield. The net rental yield analysis details tax trade-offs.
Financing Cost: The Variable That Changes Everything
Rental investment is debt-financed in ~80% of cases (Banque de France). Financing cost, absent from gross yield, determines whether the operation creates or destroys value.
Low-rate regime (2015–2022): average mortgage rate very low over 20 years (Crédit Logement Observatory). Net yield before tax: 3.0–3.5%. Positive spread of 1.5–2.5 points → leverage creates value. Loan maturities extended (25 years common) → low instalments → maximum affordability. This regime supported prices for 15 years, not because fundamentals were exceptional, but because capital cost was artificially low. The link between credit expansion and growth illusion formalizes this mechanism.
High-rate regime (2023+): average mortgage rate much higher over 20 years (Crédit Logement Observatory). Net yield before tax still 3.0–3.5%. The spread is zero or negative. Systematic negative cash flow. Required monthly savings effort: €200–400/month for an Île-de-France one-bedroom financed at 80% LTV. The investor is betting exclusively on future capital gains: a bet requiring prices to rise enough to offset years of negative cash flow + acquisition costs (~8% in existing property). The nonlinear credit-cycle reversals explain why this bet can fail.
Opportunity Cost: The Comparison Nobody Makes
Evaluating a rental investment in isolation is a methodological error. The question is not “does it yield?” but “does it yield more than alternatives, risk-adjusted, liquidity-adjusted and time-adjusted?”
10-year French government bonds: yield ~3.0% (Banque de France, early 2025), comparable to net real-estate yield, no management, no vacancy, no maintenance, liquid within 48h. Euro life-insurance funds: average yield 2.5–3.0% in 2024 (ACPR), favorable tax after 8 years, capital guaranteed. REIT funds (SCPI): average yield 4.5% in 2023 (ASPIM-IEIF), but high subscription fees, limited liquidity, significant outflows in the first half of 2024. S&P 500 (ETF): ~10% average annual total return over 30 years (S&P Global, dividends reinvested), marked volatility, fees 0.03–0.30%/year, immediate liquidity. A related angle is available in our comparison of bond ETFs by rate regime.
Direct rental investment is justified only if it offers a meaningful excess return compensating for illiquidity (resale 3–6 months, 8% costs), rental risk (arrears ~2–3% of leases, ANIL; damage; litigation), and management time (several hours a month when managed directly). This excess return has narrowed significantly with rate normalization. Where rental investment fits within the broader wealth architecture, alongside primary residence and emergency savings, is examined in primary residence, savings and investing as wealth functions.
Concentration adds a risk that a yield-to-yield comparison leaves out. For total financial wealth of €100,000, committing €80,000 of equity to a single property ties most of it to one asset. A vacancy, damage to the property or a regulatory change then weighs on the whole of that wealth.
Segment Differentiation: Generalizations Mislead
Inner Paris: a low gross yield, offset by near-inexhaustible demand (vacancy <2%, INSEE), superior resale liquidity, strong historical capital gains. Major regional metros: intermediate gross yield, solid demand, prices correcting since the 2022 peak. Mid-sized cities and periphery: higher gross yield, but higher vacancy in declining areas, weak resale liquidity, uncertain capital gains.
Furnished vs unfurnished: higher gross yields, but more frequent turnover, faster wear, heavier management. Short-term rentals: potential yield well above long-term rentals in tourist zones, but tightening regulation, seasonality, incompatible with passive investing. Energy rating (EPC) (emerging discriminant: inefficient units discounted 5–15%) opportunity for investors able to finance renovations.
The 2025–2026 Dilemma: Buying Under Regime Uncertainty
Prices down 4–8% from peak, but rates still well above their pre-2022 levels. Mortgage production slowly recovering but still well below 2022 levels. The dilemma is profile-dependent: equity >30%, horizon >10 years, ability to absorb negative cash flow → discount opportunities. High leverage, horizon <5 years, fragile demand area → substantial risk. The buy or wait analysis details scenarios. The real-time credit cycle monitor provides leading indicators.
The hidden frictions analysis quantifies each erosion layer. The net rental yield study details tax trade-offs. The buy or wait analysis details decision criteria.
← Back to the pillar page Real Estate
Last updated — 20 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Regulated and tax values: the rates, indices, caps and brackets with legal effect cited on this page are set by official decision, change over time and apply according to individual circumstances. Only the official publication in force on the relevant date is authoritative (for example the Journal officiel, INSEE, Banque de France, the IRS or the Social Security Administration). To revise a rent, sign or challenge a contract, or file a return, check the value at the source or with a professional.
Read next
Full pillar →Rent Pass-Through: How Lease Structure Decides If Inflation Reaches the Landlord
US rents adjust to inflation only when a lease resets, not continuously. Fixed terms, renewal smoothing and survey…
US Rental Property Real Yield: What Cap Rate and NOI Actually Leave You
A rental listing leads with a yield. Divide the annual rent by the price and the number looks…
Cap Rate Spread: What Rental Yield Pays Over the 10-Year Treasury
A 5% cap rate sounds attractive. But 5% against what? A risk-free 10-year Treasury yielded 4.47% on average…