
Commodities as Macroeconomic Regime Signals: Cycles, Inflation Transmission, and Strategic Power
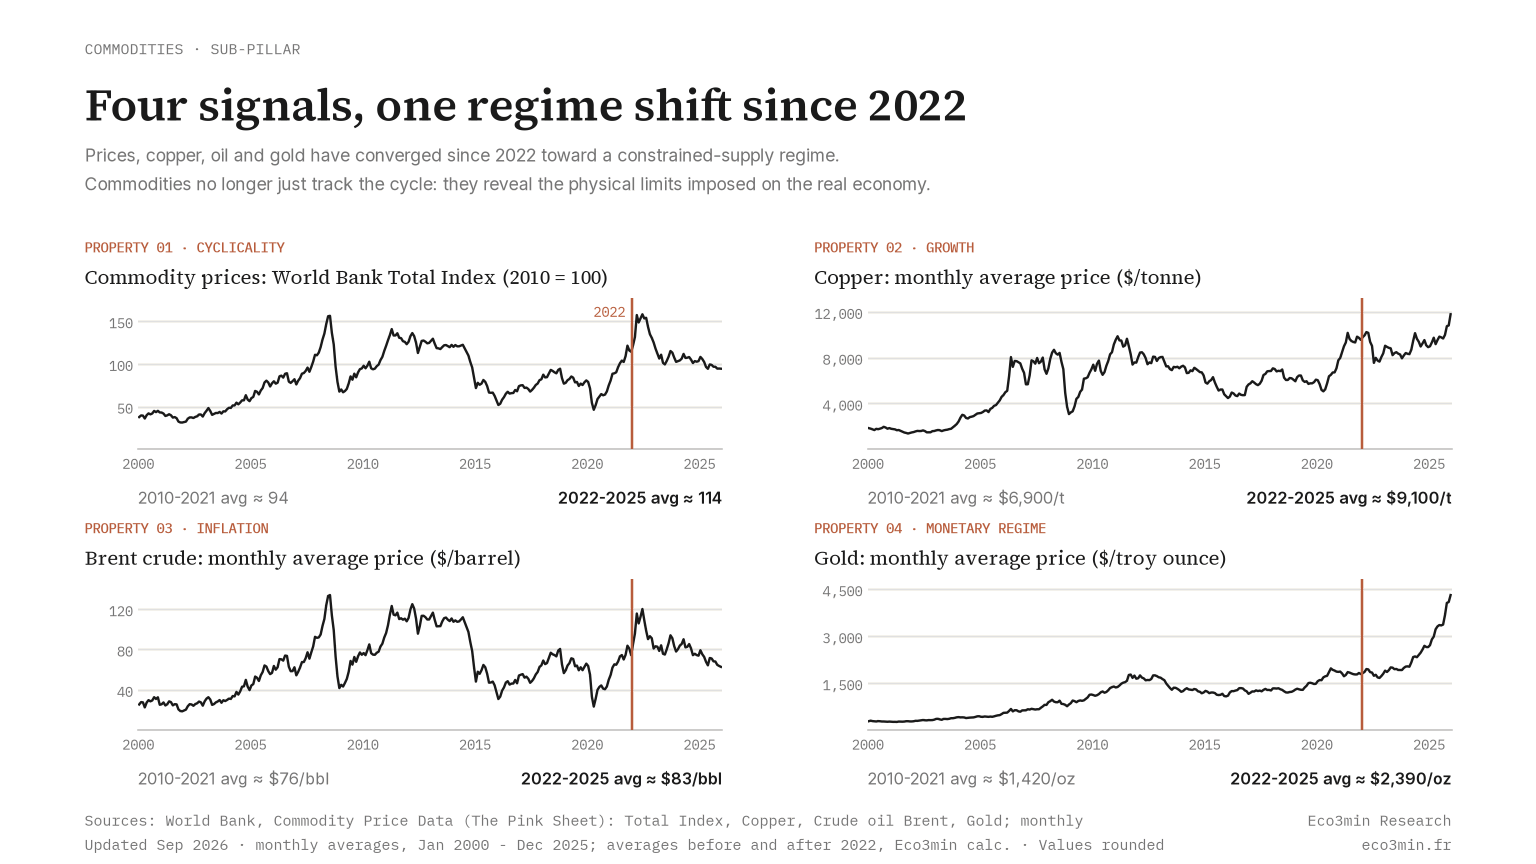
Commodities no longer just track the cycle: they reveal a constrained-supply regime: upstream underinvestment, structurally higher price levels and systemic monetary reassessment by central banks.
This page is a focused branch of the Commodities pillar. It formalizes the role of commodities as macroeconomic regime signals: structural cyclicality, transmission to inflation and growth, and their use as instruments of economic policy. The Price Formation sub-pillar covers market mechanics; this page focuses on their articulation with the macro-financial cycle.
Commodities are not merely assets: they are leading signals of macroeconomic regimes. They reveal cycle shifts, inflationary pressures, and geopolitical fractures before these materialize in official statistics. The structural inflation regime they signal is examined in the analysis of inflation as a deglobalization regime. Copper is nicknamed “Dr. Copper” because its price movements anticipate turning points in global industrial production with an empirical lead of 3 to 6 months (IMF Working Paper, 2019). Oil is the primary transmission channel of supply shocks into inflation: every $10/barrel increase in Brent adds 0.2 to 0.4 percentage points to headline inflation in importing countries over a 6–12 month horizon (ECB, Economic Bulletin). Gold acts as a barometer of confidence in the monetary system: its rise from $1,076 an ounce in December 2015 to $2,690 in October 2024, in monthly averages (World Bank Pink Sheet), reflects the gradual repricing of monetary fragmentation risk. Data: the World Bank Pink Sheet.
The question structuring this sub-pillar is not “where are commodity prices heading?”; it is: what do commodity markets tell us about the prevailing macroeconomic regime, the phase of the cycle, and the structural constraints facing the real economy? See also: our analysis of the disinflationary regime.
The structural cyclicality of commodities
Commodities are inherently cyclical, and their cyclicality stems from a fundamental mechanism: the temporal asymmetry between demand response (fast) and supply response (slow). This mechanism produces documented “supercycles” lasting 10 to 30 years, alternating between phases of structural upswings (underinvestment → deficits → high prices) and structural downswings (overinvestment → surpluses → low prices). Also relevant: our study on real commodity prices since 1960 across food and energy.
Recent history illustrates this mechanism clearly. The 2000–2011 supercycle was triggered by China’s industrialization: Chinese copper demand increased fivefold between 2000 and 2015 (ICSG), oil demand more than doubled (IEA), and steel demand surged (World Steel Association). The Bloomberg Commodity Index tripled between 2001 and 2008. The 2012–2020 downturn resulted from overinvestment in the prior decade: oil exploration and production investment peaked at $700 billion per year in 2014 (IEA), creating structural oversupply that drove Brent from $115 to $26 between June 2014 and January 2016 (daily spot prices, EIA). Directly related: Eco3min’s inventory of historical crises.
The current regime, documented in the Macroeconomics & Geopolitics pillar, is characterized by chronic underinvestment in production capacity. Oil exploration investment fell sharply after 2014 and has recovered only partly since (IEA), insufficient to offset natural decline in existing fields (IEA). Mining investment (copper, lithium, nickel) is rising but remains below levels required to meet energy-transition demand: the IEA estimates a large cumulative investment gap in critical minerals by 2030 (Critical Minerals Market Review, 2024). This underinvestment forms the foundation of the next upswing cycle. A detailed analysis is provided in Why commodities are inherently cyclical.
Supply abundance
Overinvestment in the 2000s saturates capacity.
- Oil exploration peak: $700bn/year (2014)
- Structural surplus → Brent from $115 to $26 (2014–2016)
- Low prices, ample capacity, little tension
Supply constraints
Chronic underinvestment narrows the margin.
- Exploration fell to $370bn (2020), only partly recovered to $500bn (2024)
- Natural field decline of 4–5%/year left unmet
- Critical-minerals investment gap: $360bn by 2030
Commodities and growth: the physical link
Commodity demand is a direct indicator of productive activity, in some cases more reliable than GDP metrics, which include a growing services and financial component. One regime switch made that visibility brutal, reconstructed in the 2020 Covid shock and its disinflationary slowdown. The “commodity intensity” ratio, the quantity of commodities consumed per unit of GDP, evolves with the stage of economic development and is a structural driver of commodity markets. the copper-gold ratio as a macro signal retraces the successive episodes.
China consumes 55% of global copper and a notable share of coal and oil (USGS, IEA). It also produces more than half of the world’s crude steel: about 980 million of 1,900 million tonnes in 2025, according to U.S. Geological Survey estimates. These physical demand patterns by commodity are detailed in our physical commodity markets sub-pillar. China’s manufacturing PMI (Caixin) and its copper demand show significant correlation (IMF). When China slows, industrial commodities signal global deceleration before GDP statistics confirm it, as in 2015 (China slowdown, copper -25%, Brent -50%) or mid-2022 (China property tightening, iron ore -30%).
But the link between commodities and growth is being reshaped by the energy transition. Oil demand may plateau in the 2030s (IEA, World Energy Outlook 2024), while demand for copper, lithium, nickel, and cobalt is structurally accelerating. The IEA estimates that copper demand linked to “clean technologies” (EVs, grids, renewables) will double by 2040 (Critical Minerals Market Review). This rotation, from fossil energy to metals, is redefining what commodities signal about growth. Another regime shift read through its indicators is documented in the 2000 dot-com crash read through the indicators.
Transmission to inflation: the most direct channel
Commodities are the primary transmission channel of supply shocks into inflation: a mechanism obscured during the “Great Moderation” decade and abruptly revived in 2021–2023. For the broader picture: our study on when commodities actually diversify a stock portfolio.
The 2021–2022 sequence is a textbook case. Between January 2021 and their 2022 peaks, in monthly averages, European natural gas prices rose nearly tenfold, Brent more than doubled, US wheat jumped about 60%, and urea more than tripled (World Bank Pink Sheet). For oil producers’ earnings, the doubling of Brent was only half the equation, the other half being the refining margin, a stronger driver of oil profits than the barrel price. Europe’s additional energy bill exceeded €200bn in 2022 (Bruegel). Euro area HICP reached 10.6% in October 2022 (Eurostat), US CPI 9.1% in June 2022 (BLS), and UK CPI 11.1% (ONS). Energy alone accounted for 3–4 percentage points of headline inflation at the peak (Eurostat, BLS). Companion analysis: the limits of the commodity lead.
But commodities do not transmit inflation uniformly, and this differentiation is structurally important. Energy acts as a classic supply shock: it raises production costs economy-wide and passes rapidly into consumer prices (6–12 months). Cocoa recently offered a textbook case on this point, covered in cocoa’s West African supply concentration. Industrial metals act with longer lags (12–24 months) and more targeted effects: via manufacturing, real estate, and automotive sectors. Agricultural commodities generate food inflation with high political sensitivity: the 2008 food riots (FAO) and North African instability in 2011 were directly linked to grain price spikes. Which inflation gauge captures that transmission is a question of its own: see a 65-year comparison of PCE and CPI inflation gauges.
The current regime is characterized by “structurally higher” inflation than the prior decade: a diagnosis partly grounded in physical constraints documented in the Macroeconomics & Geopolitics pillar. The ECB estimates that supply-chain fragmentation and energy constraints add 1–2 percentage points of structural inflation per year (Economic Bulletin, 2023). A differentiated analysis is provided in Why commodities react differently to inflation.
The policy response: tightening into a supply shock
The split between headline inflation, which includes energy and food, and core inflation, which excludes both, is where the policy response is decided. In June 2022, US headline CPI stood at 9.1% against 5.9% excluding food and energy (BLS). A gap of that kind leaves the central bank with a demand tool aimed at a supply problem. Raising rates does not lower crude prices when OPEC cuts output or a conflict disrupts shipping. It makes credit more expensive, slows investment and consumption, and eases overall price pressure only through those indirect channels, at the cost of a slowdown, often a recession.
What the central bank targets in such episodes is the second round: inflation expectations, wage negotiations and firms’ pricing power, so that a physical shock does not become embedded. The cost is easy to underprice. Tightening cycles triggered by commodity shocks have historically produced sharper slowdowns than those driven by demand overheating, because the instrument is poorly calibrated for the shock it is asked to absorb.
Three US episodes trace the same arc, from commodity shock to monetary tightening. When OPEC quadrupled crude in 1973-1974, US inflation rose from 3.4% in December 1972 to 8.7% a year later and 12.3% in December 1974 (CPI-U, BLS). The Fed under Arthur Burns moved too late and too little, expectations came unanchored, and the regime took a decade to break. Against inflation of 14.8% in March 1980, the Volcker tightening pushed the effective fed funds rate above 20% on twenty-seven sessions between December 1980 and July 1981, up to 22.36% on 22 July 1981. Inflation was defeated, at the cost of two consecutive recessions. The post-Covid episode combined a logistics shock, the energy surge linked to the war in Ukraine and massive fiscal stimulus. Central banks first called the inflation “transitory”; the fastest hiking cycle in modern history followed.
Commodities as regime signals
Beyond their cyclical role, commodities act as markers of macroeconomic regime shifts: signals that traditional financial indicators fail to capture because they reflect irreducible physical constraints. The historical record behind it is laid out in the copper-gold ratio against bond yields.
Three active constraint signals
Structural underinvestment
Undersized production capacity (oil exploration $700bn → $370bn → $500bn; a $360bn critical-minerals gap by 2030). Signals a regime of durable supply constraints: the opposite of the 2014-2020 abundance. Related coverage: our study on how commodities stopped being a reliable diversifier after 2008.
Physical growth constraints →Central bank gold purchases
Above 1,000 tonnes a year from 2022 to 2024, more than double the 2010-2021 average (WGC). Signals a systemic reassessment of monetary risk and gradual reserve de-dollarization.
Critical-minerals concentration
China: 60% of rare earths, 70% of refined cobalt, 80% of graphite; Congo: the bulk of cobalt mining (USGS/IEA). Turns commodities into geopolitical leverage.
The reference article Commodities: regime real assets and leading signals of the economic cycle develops this interpretive framework in depth.
Commodities as instruments of economic policy
States use commodities as economic policy levers, often indirectly and discreetly: sanctions, export quotas, subsidies, environmental standards, and strategic stockpile policies. China restricted gallium and germanium exports in August 2023 (MOFCOM), and graphite exports in December 2023, critical inputs for semiconductors and batteries, in response to US chip restrictions. Indonesia banned raw nickel ore exports in 2020 (Ministry of Energy and Mineral Resources) to force domestic refining and capture value-added: Indonesia’s share of global nickel refining rose from 6% to 40% in five years (USGS). The wider context: our study on every oil shock since 1973 and what U.S. inflation did next.
OPEC+ actively manages oil supply: cumulative production cuts reached 5.86 mb/d in 2024 (OPEC+). That is more than 5% of world production of petroleum and other liquids, 103 mb/d that year according to the EIA. US Strategic Petroleum Reserves (SPR) were heavily used in 2022 (180 million barrels released per DOE, the largest drawdown in history) as a price policy and anti-inflation tool. This strategic use of commodities as economic policy levers is analyzed in Commodities as instruments of indirect economic policy and in The role of producing countries in price cycles.
Commodities are not assets like others: they are signals of physical constraints imposed on the economic system. Their cyclicality stems from the structural asymmetry between slow supply (years, decades) and fast demand (months, quarters). They are the primary transmission channel of supply shocks into inflation and a leading indicator of the global industrial cycle. The deepest historical stress-test of those signals is retraced in the 1929 crash and the Great Depression. A useful reference here: how wind and solar overtook coal in the U.S. power mix. The current regime (chronic underinvestment, extreme geographic concentration, and strategic use as power levers) signals the return of physical constraints to the real economy after a decade of abundance. The relevant diagnosis is not “what is the oil price?” but “what do commodity markets reveal about supply regimes, structural constraints on the real economy, and the geopolitical power dynamics shaping access to resources?”.
Further reading
Commodities: regime real assets and leading signals of the cycle, The reference article on commodities as macro regime markers.
Why commodities are inherently cyclical: The fundamental mechanism of supercycles.
Why commodities react differently to inflation: Differentiated transmission by family and regime.
Commodities as instruments of indirect economic policy: The strategic use of resources as power levers.
The role of producing countries in price cycles: OPEC+, geographic concentration, and market power.
← Back to pillar page Commodities
Last updated — 29 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Reading the refinery utilisation rate: the threshold, the season, the turnarounds
A refinery runs full near ninety percent, not a hundred: the last slice of nameplate capacity is a…
The 2022–2023 refining golden age: anatomy of an episode
In 2022, refined fuel prices climbed faster than crude. That gap, measured by the 3-2-1 crack spread, reached…
Diesel versus gasoline: why the two crack spreads diverge
The 3-2-1 crack blends gasoline and distillate into a single number, and that convenience hides something the market…