
Dividends and Share Buybacks: Total Shareholder Yield and Distribution Cycles
Dividends and share buybacks are the two channels through which companies return capital to shareholders. These flows, often overlooked in standard equity analysis, represent a major component of long-term total returns. But their sustainability depends on the profit cycle, financing conditions, and balance-sheet constraints, not on short-term valuation levels.
S&P 500 companies returned roughly $1.7 trillion to shareholders in 2022, through share buybacks and dividends (S&P Global). That is more than Australia’s GDP. Share buybacks have become the largest source of net demand in the U.S. equity market since 2011 (Federal Reserve Flow of Funds), exceeding purchases by pension funds, households, and foreign investors combined. Apple alone repurchased more than $625 billion of its own shares between 2013 and 2024 (SEC filings): equivalent to the market capitalization of the vast majority of S&P 500 companies.
These figures are not statistical curiosities: they determine the very structure of returns. Over 1926–2023, reinvested dividends account for roughly 53% of the S&P 500’s total return (Hartford Funds/Morningstar). Ignoring distributions in equity return analysis means ignoring more than half the return. The reference framework is developed in our study of total shareholder yield.
Dividends: recurring income, confidence signal, and potential trap
A dividend is the portion of earnings distributed to shareholders. For investors, it is tangible income, independent of price fluctuations, and historically the dominant component of total return. The S&P 500’s average dividend yield has fallen sharply since the 1970s–80s (S&P Global), not because companies distribute less in absolute terms, but because valuations have surged and buybacks have taken over.
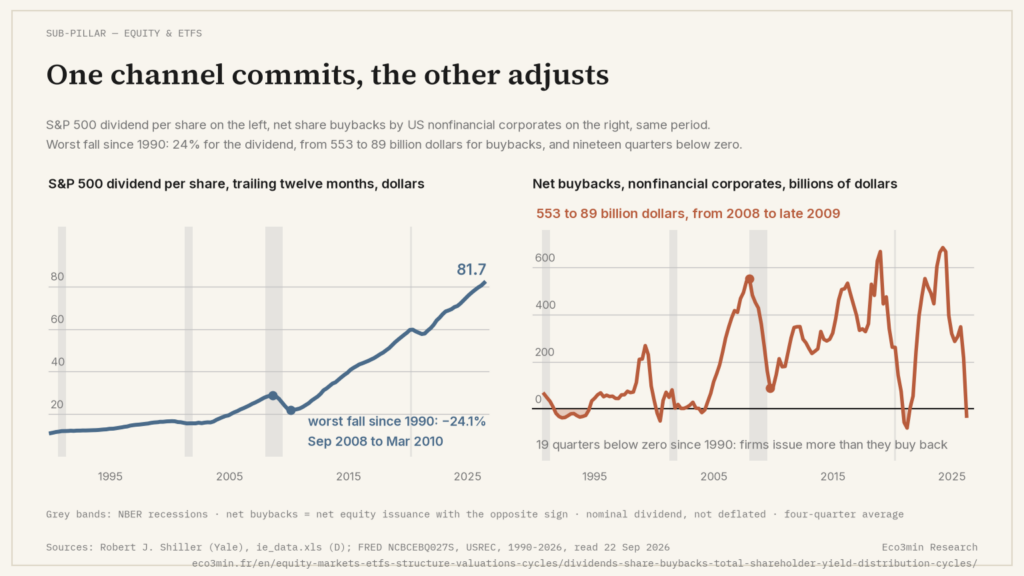
Dividends act as a signal. A company that initiates or raises its dividend signals confidence in the durability of earnings: executives are reluctant to cut dividends because market penalties are immediate (on average −3% to −7% on announcement day, Grullon & Michaely 2002, Journal of Finance). This rigidity creates commitment effects: companies prefer to borrow to maintain dividends rather than send a negative signal. In 2020, S&P 500 dividends fell only slightly despite recession (S&P Global), while buybacks, which are more flexible, dropped sharply. Once those dividends reach the investor, how they are taxed varies by bracket: see The flat-versus-progressive breakeven by bracket.
The yield trap is the most common mistake: a high dividend yield can result from a price collapse anticipating a future cut. Structurally challenged sectors (post-COVID commercial real estate, U.S. regional banks in 2023, overleveraged utilities) may show apparently attractive 6–10% yields, masking 30–50% capital loss risk. SVB Financial’s 8% yield in January 2023 (before its March collapse) signaled distress, not value. Dividend sustainability always matters more than headline yield. Reading a company through its distribution yield rather than its operations is a habit shaped by the rising share of financial activity in the economy.
Share buybacks have become the dominant shareholder return channel in the U.S.: a historic reversal that occurred during the 2000s. S&P 500 buybacks reached very large amounts in 2022 and 2023 (S&P Global). Mechanism: the company repurchases its own shares and retires them → shares outstanding fall → earnings per share (EPS) rise mechanically even without total earnings growth → the stock price rises (all else equal).
Advantages vs dividends: buybacks offer greater flexibility (suspension without negative signaling, S&P 500 buybacks fell sharply in Q1–Q2 2020 without market penalty). Tax treatment is often more favorable (capital gains vs income). Firms can modulate repurchases depending on valuation, buying more when prices are low, less when high (in theory).
In practice, buybacks are heavily procyclical. Firms repurchase more when prices are high (confidence + abundant cash) and less when prices are low (caution). S&P 500 buybacks hit a record in Q4 2021 (S&P Global): at the market peak, before the 2022 correction. They fell sharply in Q2 2022: near the trough. Companies buy high and scale back when cheap: the opposite of rational capital allocation.
Debt-financed buybacks are the key structural risk. In the low-rate regime (2009–2021), borrowing at 2–3% to repurchase shares yielding 5–8% appeared arithmetically rational. U.S. corporate bond issuance financed a significant share of buybacks: non-financial corporate debt rose from $6tn (2010) to $10tn (2023, Federal Reserve). In a high-rate regime (2022+), refinancing costs rise: firms that optimized balance sheets for buybacks face more expensive debt service, reduced flexibility, and greater vulnerability if profits slow. Leverage amplifies returns in favorable phases but weakens balance sheets in adverse phases: a mechanism developed in the analysis of leverage effects and diffuse risk.
Dividend yield alone is incomplete now that buybacks dominate. Total shareholder yield adds dividends + net buybacks (repurchases − new issuance), divided by market capitalization. This metric reveals realities masked by dividend yield alone.
Apple: dividend yield 0.5%, but net buybacks ~3.5%/year → total shareholder yield ~4% (SEC filings, 2023). Meta: dividend yield 0.4% (initiated 2024) + net buybacks ~4% → shareholder yield ~4.4%. By contrast, Tesla: 0% dividend, negative net buybacks (dilution from stock-based compensation ~2%/year, SEC filings) → negative total shareholder yield. Tesla shareholders receive nothing: they are diluted. Tech giants with apparently low yields (dividend yield <1%) actually return 3–5% annually via buybacks: comparable to high-dividend utilities. Related framing: a screening grid for dividend stocks.
Identifying hidden dilution is essential. Many tech firms (Salesforce, Palantir, Snowflake) issue large volumes of stock options and RSUs that dilute existing shareholders by 3–8%/year (SEC filings). A nominal 5% buyback can be offset by 6% issuance, producing zero real return. Net shareholder yield (buybacks − issuance + dividends) is the only metric capturing effective capital return. Net of issuance, the measure only makes sense if shareholders are treated as the residual owners of the cash: the premise of the norm that ranks shareholders first in capital allocation.
A scan of 2024-2025 annual reports shows where that dilution sits. Beyond technology, where several cloud infrastructure and cybersecurity names print more shares than they retire over multi-year windows, mature sectors (utilities, consumer staples, traditional energy) use equity compensation sparingly: their buybacks translate almost fully into a smaller float, and the gross figure is a reasonable proxy for the actual return. Large US banks sit in between, pairing large buyback envelopes with regular issuance linked to deferred bonus plans. The numbers that settle the question rarely reach earnings releases. Stock-based compensation has its own line in the consolidated cash flow statement, and the change in diluted share count sits deeper in the 10-K, in the equity reconciliation table. Shareholder-yield projections relayed by financial media generally start from announced envelopes without expected issuance, a bias largest in the equity-compensation-heavy sectors that dominate index weight in 2026.
Distribution sustainability: the metrics that matter
The central question for distribution analysis: can the company maintain this level of payout during a downturn?
Payout ratio (dividends / net income): the S&P 500 average payout ratio is moderate and sustainable (S&P Global, 2023). A ratio >80% signals limited safety margin; >100% means the firm distributes more than it earns: unsustainable without debt or reserves. Some REITs (required to distribute 90% of income) and utilities structurally operate at 70–90%: normal for their models but vulnerable to revenue shocks.
Dividends / free cash flow (more conservative than accounting payout ratio): >70% suggests limited buffer to absorb cash-flow shocks. Total distributions / free cash flow (dividends + buybacks / FCF): when >100%, payouts are debt-funded, a warning signal in any regime, critical in high-rate regimes. Net debt trajectory: simultaneous increases in buybacks and debt signal leverage-financed distributions, sustainable only while refinancing conditions remain favorable.
Dividend Aristocrats (S&P 500 Dividend Aristocrats Index: companies with a long record of consecutive dividend growth, S&P Global) offer stronger visibility on sustainability, but are not immune. AT&T cut its dividend by 47% in 2022. General Electric eliminated its historic dividend in 2018. Longevity raises probability of continuity: it does not guarantee it.
Distributions follow the cycle: with a lag
Distribution policies are procyclical with significant lag, creating traps for investors who extrapolate past payouts.
Expansion: profits rise → cash accumulates → firms gradually raise dividends and buybacks. S&P 500 buybacks increased every quarter from Q3 2020 to Q4 2021 (S&P Global), aligned with recovery. Late cycle: distributions peak. Buybacks reached a quarterly record in Q4 2021 (S&P Global): just before the market correction. Executives, confident in profit durability, maintain or raise payouts, sometimes adding leverage at the worst moment.
Contraction: profits fall but distributions adjust with delay. Typical sequence: (1) buybacks cut first (flexibility) → S&P buybacks fell sharply in Q1–Q2 2020; (2) firms draw reserves to maintain dividends; (3) dividends cut only as last resort, S&P 500 dividends fell only marginally in 2020 despite recession. Dividend cuts often occur after market troughs, when markets already rebound, because boards react with 6–12 months lag.
Recovery: firms rebuild balance sheets before restoring payouts. Buybacks resume first (flexibility) → a sharp rebound from Q3 2020 to Q4 2021. Dividend growth resumes with 2–3 quarters lag. Rate regimes determine pace: in low-rate regimes (2020–2021), near-zero refinancing costs enabled immediate buyback resumption. In high-rate regimes, payout recovery will be slower, refinancing costs constrain leverage rebuilding. A parallel read: Buybacks versus dividends, by the data.
Netting issuance sharpens the contraction picture. Companies suspend or scale back buyback programmes, but shares from compensation plans already granted keep vesting, so the net balance can turn negative precisely as the share price falls, compounding the drawdown. For debt-funded programmes, exposure in a downturn depends on maturity as much as on leverage. A seemingly reasonable overall ratio can hide a heavy concentration of short-term maturities, and the shorter the average maturity, the sooner the company refinances at potentially higher rates. One comparison separates the two engines of per-share growth: when EPS grows much faster than total net income, the buyback effect on reported earnings is likely material.
United States vs Europe: two distribution cultures
In the United States, buybacks dominate: the largest share of total shareholder return (S&P Global). U.S. firms prioritize flexibility and tax efficiency. The S&P 500’s average dividend yield is low, but total shareholder yield (dividends + net buybacks) is much higher. Tech giants (GAFAM) pay symbolic dividends (Apple yield 0.5%) but repurchase heavily (~3.5%/year of shares).
In Europe, dividend culture remains stronger. The STOXX 600’s average dividend yield is ~3.5% (STOXX/Qontigo, 2024). European investors (notably pension funds, insurers, and income funds) expect regular and growing distributions. Buybacks are expanding (TotalEnergies, LVMH, Shell launched major programs) but remain below U.S. levels. Special dividends are more frequent in Europe than in the U.S.
Geographic yield comparisons based only on dividend yield overstate real gaps. The S&P 500’s total shareholder yield is comparable to the STOXX 600’s: the difference lies in composition, not magnitude.
The reference framework on total shareholder yield develops the full analytical structure. The Capital Flows sub-pillar analyzes buybacks as the primary source of net equity demand. The Asset Allocation Foundations sub-pillar integrates shareholder yield into portfolio construction frameworks.
← Back to pillar page Equities and ETFs
Last updated — 29 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Dividend yield alone underestimates what equity holders actually receive. Adding net buybacks reshuffles the comparison between US and…
Passive management: how ETFs are transforming market structure
Passive management has profoundly transformed the structure of financial markets. What was a marginal innovation in the 1970s…
Companies and Economic Sectors: Structural Drivers of Competitiveness and Value Creation
Economic cycles, cost of capital, innovation and regulation: the structural forces that determine competitiveness, margins, and long-term corporate…