
Real Estate and Inflation: Credit, Real Rates and the Protection Paradox
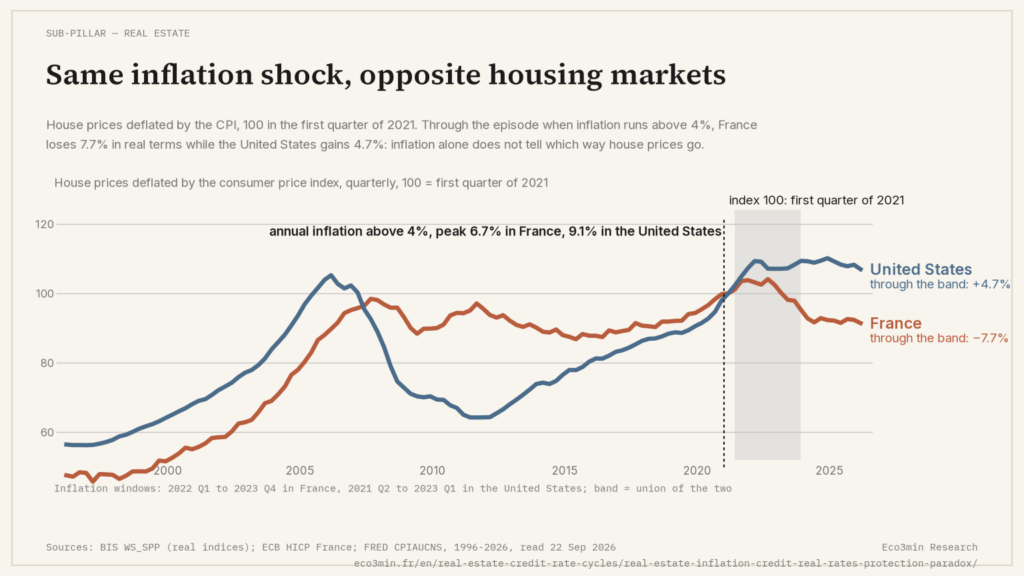
Inflation alone does not push real estate higher: credit does. Real estate provides protection against inflation only under specific conditions: contained real rates, preserved access to credit, and effective rent indexation. These regime conditions are framed in the complete guide to inflation. When inflation triggers abrupt monetary tightening, that protection becomes illusory: the negative effect on borrowing capacity outweighs the theoretical positive effect of indexation. The 2022–2023 episode demonstrated this: inflation reached 40-year highs while property prices corrected.
Factual sequence. In June 2022, euro area inflation reached 8.6% year-on-year (Eurostat), then the highest since the creation of the euro. France: 6.1% (INSEE). The ECB raised policy rates from 0% to 4.50% in 14 months (July 2022 → September 2023): the fastest tightening in ECB history. The average mortgage rate in France reached 4.24% in December 2023 (all maturities), far above its pre-shock level (Crédit Logement/CSA Observatory). Average household borrowing capacity fell sharply at constant monthly payments (Crédit Logement simulation). Mortgage production: -40% in volume (Banque de France). Existing-home prices in France: -4% nationally, -5 to -8% in Île-de-France (INSEE/Notaries). Sweden: -15% (SCB). Germany: -10 to -15% in major metropolitan areas (Bundesbank). China: sales down -27% in 2022 (NBS) → Evergrande crisis → systemic contagion.
Result: countries experiencing high inflation saw property prices fall simultaneously. The paradox is only apparent; it reveals the central mechanism: property valuation depends on available credit, not on consumer-price inflation. When inflation triggers higher interest rates, credit contraction outweighs theoretical indexation. The link between credit and asset valuation is the mechanism governing everything. Credit as the engine of economic cycles provides the macro framework.
The Theoretical Mechanism: and Why It Only Half Works
The argument for real estate as an inflation hedge rests on two theoretical pillars. First pillar: rents are indexed to consumer prices, preserving the purchasing power of rental income. In France, the IRL (Rent Reference Index) tracks inflation excluding tobacco and rents: a real and functional mechanism. See also the role of lease structure in passing inflation to rent. Second pillar: property value in current currency tends to follow the general price level over the long term. Historical data: real (inflation-adjusted) property prices in France rose ~2.5% per year between 1997 and 2007 (INSEE/Notaries), then stagnated in real terms between 2007 and 2022, nominal increases reflected inflation, not real value creation. Background: the reading that sorts hedges by real-rate environment.
These two mechanisms operate under moderate inflation and stable real rates, that is, when price increases do not trigger abrupt monetary reactions. In this regime (2000–2021, inflation 1–2%, policy rates 0–2%), real estate indeed behaves like a real asset that gradually adjusts to prices. But this mechanism rests on an implicit assumption: that financing conditions remain supportive. That assumption breaks precisely when inflation accelerates: the core paradox. For context: the Eco3min reading of REIT repricing.
The High-Inflation Paradox: When “Protection” Destroys Value
The 2022–2023 episode is the most documented textbook case of the paradox.
Observed causal chain: energy shock (Ukraine invasion, Feb 2022) → imported inflation (surge in European gas prices, TTF) → ECB response (rates 0% → 4.50% in 14 months) → much higher mortgage rates in France → reduced borrowing capacity → mortgage production -40% → transactions -28% (1.2M → 870k) → prices -4 to -8%. Meanwhile, rents rose +3.5% (IRL cap, INSEE): indexation worked, but rental income growth (+3.5%) did not offset capital losses (-4 to -8%). This articulation is mapped in the guarantee’s real-return limits.
Country magnitude: Sweden -15% (market largely variable-rate → immediate transmission, SCB). Germany -10 to -15% in major metros (Bundesbank): investor-heavy rental market sensitive to relative yields. Netherlands -6% (CBS). Canada -15 to -20% in major metros (CREA). United States: correction limited to -5% thanks to 30-year fixed mortgages (57% of outstanding loans, Federal Reserve) protecting existing owners, but new buyers excluded by collapsing affordability (NAR Affordability Index: lowest since 1989).
The real estate and inflation protection sub-pillar expands on these dynamics. Nonlinear credit-cycle reversals explain why corrections occur with surprising brutality.
Real Rates: The Determinant Markets Ignore
The concept of the real interest rate, nominal rate minus expected inflation, is decisive for understanding the real estate/inflation relationship. It is the real rate, not the nominal rate, that determines the effective cost of credit and household purchasing power. Worth reading alongside: buying versus renting, by the data.
Negative real rates (2015–2022): nominal very low, inflation 1–2% → real rate ~0% or negative. Borrowers are in an exceptional position: monetary erosion reduces the real weight of debt. A €200,000 loan at a -1% real rate loses ~€2,000/year in real value: a transfer from savers to borrowers. This configuration mechanically supports prices and strengthens the protective effect. But it creates an illusion of wealth growth: price increases reflect financing effects, not real value creation. The real policy rates sub-pillar formalizes this mechanism across assets.
Positive real rates (2023+): nominal sharply higher, inflation 2–3% → real rate +1.0 to +2.0%. The real debt burden increases. A €200,000 loan at a +1.5% real rate effectively costs ~€3,000/year in purchasing power: a transfer from borrowers to savers. Real estate ceases to protect against inflation and can amplify wealth losses. Severe historical precedents (Japan in the 1990s, property -60 to -70% between 1991 and 2004, BoJ; post-2008 Spain, -37% over 2008–2014, INE; post-2008 Ireland, -50%, CSO) illustrate phases of deleveraging and prolonged stagnation following credit excesses.
Rent Indexation: Income Protection, Not Capital Protection
For rental investors, rent indexation is the most direct, and most overestimated, protection mechanism. In France, the IRL allows annual rent revisions based on consumer prices excluding tobacco and rents.
What works: in normal regimes (inflation 1–3%), the IRL preserves rental income purchasing power. An €800/month rent indexed at 2%/year becomes €816, then €832, etc.: modest but cumulative growth. Over 10 years at 2% inflation: final rent ~€975, +22%, a real mechanism.
What does not work: in high inflation periods, governments cap the IRL. A 3.5% cap was introduced in 2022 and maintained until 2024, while inflation reached 5–6%. Cumulative gap: rents under-indexed by 3–5% relative to actual inflation. Indexation applies only to future income, not to capital value. Owners can see rents rise +3.5%/year while property value falls -8%: capital loss outweighs several years of indexation. The capped years show up plainly in the quarterly history of France’s rent reference index, where 2022 to 2024 sit at the 3.5% ceiling.
Indexation protects income: imperfectly. It does not protect capital, which depends on financing conditions, not rent levels.
Nominal Price per Square Meter: The Indicator That Misleads Everyone
Observing nominal prices leads to erroneous conclusions. A nominal price increase does not imply a gain in real wealth: it may simply reflect monetary erosion.
Paris example: average price per m² in 2000: ~€3,000. In 2023: ~€9,500 (Notaries-INSEE). Nominal increase: ×3.2 in 23 years. Cumulative inflation: ~45%. Real price (inflation-adjusted): ×2.2, still impressive, but one-third of the apparent increase reflects inflation only. Provincial example: average existing apartment price outside Île-de-France: ~€2,200/m² in 2023 vs ~€2,000 in 2010. Nominal +10% in 13 years. Cumulative inflation: ~20%. Real price: -8 to -10%, investors who believed they preserved wealth actually lost purchasing power.
Moreover, average price per m² aggregates heterogeneous properties whose quality evolves. Price increases may reflect a composition effect, sales concentrated in higher-quality units, rather than appreciation of the entire stock. Hedonic indices (INSEE/Notaries) partially correct this bias, but headline prices do not. The price-per-square-meter as misleading indicator article deconstructs these biases.
Rents, Discount Rates and Expenses: Three Clocks Out of Sync
The IRL cap is only one source of lag. Consumer prices can accelerate while rents react several quarters later, held back by multi-year leases, partial indexation and, above all, the solvency of households. High inflation does not mechanically raise real incomes. When wages trail prices, tenants’ capacity to absorb higher rents deteriorates, which limits the transmission of inflation to rental flows. Euro area inflation peaked at 10.6% in October 2022 (Eurostat).
The discount rate. The German 10-year yield went from -0.38% in December 2021 to 2.82% in October 2023, held between 2.41% and 2.81% in 2025 and reached 3.19% in August 2026 (ECB long-term interest rate statistics). The asset is real, but its value is discounted at a higher rate. In France, the average rate on new housing loans excluding renegotiations rose from about 1.1% in January 2022 to 4.2% in January 2024 (Banque de France), which cuts the amount borrowable over 20 years at a constant monthly payment by about 25%.
Expenses. Charges can rise faster than incomes even while inflation runs high. In France, the legal revaluation of property-tax bases, indexed on the HICP, reached 7.1% in 2023 and 3.9% in 2024 (article 1518 bis of the tax code). For companies in the sector, operating costs can outpace collected rents.
The 2026 sequence. Euro area inflation returned to 2.0% in December 2025, then climbed back to 3.8% in September 2026 (Eurostat). The ECB raised its deposit rate from 2.00% to 2.25% on 17 June 2026 and to 2.50% on 16 September. Financing costs reprice at the ECB meeting. The French rent index, built on a twelve-month average of prices, rose only 1.15% in the second quarter of 2026 (INSEE), so the three clocks drift further apart.
Housing Inside the Price Index: One Word, Two Measures
The link between housing and inflation also runs the other way: housing is part of the index that measures inflation, with a very different weight on each side of the Atlantic. According to the Bureau of Labor Statistics relative importance table, shelter accounted for 35.625% of the US consumer price index (CPI-U) in December 2025. Most of it is not rent actually paid. Owners’ equivalent rent, an estimate of what homeowners would pay to rent their own home, weighs 26.204%, against 7.840% for rent of primary residence, paid by tenants.
The euro area’s harmonized index (HICP) has excluded owner-occupied housing since it began, treating it as an investment rather than consumption. Only actual rentals remain, at 5.85% of the basket in 2026 according to Eurostat’s HICP item weights; housing in the broad sense, water and household energy included, reaches 14.6%. The same pace of rent increases therefore weighs six times more in the US index. The usual reading attributes the persistence of US inflation in 2023-2024 to a tighter housing market than Europe’s. Part of the gap comes from how the indexes are built.
A slow index by construction. The US measure tracks rents on units already leased, many of which have not changed hands in months, so a turn in market rents feeds into the index only as leases renew. Shelter inflation peaked at 8.2% year over year in March 2023 (CUSR0000SAH1), then came down slowly: 5.6% in March 2024, 4.0% in March 2025, 3.4% in August 2026.
A gap that turned negative. Through 2023-2025, US shelter rose faster than headline inflation: the gap was +3.3 points in March 2023, flipped in March 2026 and stood at −0.28 point in August. Euro-area rents moved from 1.3 points above headline HICP in January 2026 to 0.6 point below it in August. Housing did not suddenly give way. Headline inflation rose instead, driven by energy, while housing kept easing slowly. The gap between housing and headline inflation in each region, published monthly by the BLS and Eurostat, shows which engine is driving prices.
The Four Conditions for Effective Protection
Historical analysis identifies conditions under which real estate effectively protects against inflation. These conditions form a cluster, if one is missing, protection becomes uncertain.
Condition 1: Low or negative real rates. Protection holds when the real cost of credit remains contained. Significantly positive real rates (>1.5%) → heavier real debt burden → downward price pressure. Condition 2: Preserved credit access. Even with low rates, tighter lending standards (higher equity requirements, shorter maturities, stricter solvency criteria) contract demand. A credit crunch can trigger corrections regardless of inflation. Condition 3: Effective rent indexation. IRL caps → only partial protection. Condition 4: Long investment horizon (>10–15 years). Over very long periods, real estate tends to preserve purchasing power. Over short horizons (
The real-time credit-cycle monitor helps assess whether these conditions hold or are deteriorating.
Domestic vs Imported Inflation: Two Regimes, Opposite Outcomes
The nature of inflation changes everything. Two inflation regimes produce radically different real-estate outcomes.
Domestic inflation (demand and wage-driven): household incomes rise with prices → purchasing power preserved → housing demand holds. If real rates remain contained, property prices follow, or exceed, inflation. Example: France 1970–1982 → real property price gains.
Imported inflation (supply shock without income growth): prices rise without matching wage growth → purchasing power compressed → borrowing capacity reduced → housing demand contracts. Tight monetary response worsens compression. Example: 2022–2023 → property price corrections across Europe. History shows the most severe crises follow easy-credit phases. The Macroeconomics & geopolitics pillar details inflation regimes.
The analysis of real estate as an imperfect inflation hedge expands on these mechanisms. The price-per-square-meter as misleading indicator article deconstructs analytical biases.
← Back to the pillar page Real Estate
Last updated — 27 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Regulated and tax values: the rates, indices, caps and brackets with legal effect cited on this page are set by official decision, change over time and apply according to individual circumstances. Only the official publication in force on the relevant date is authoritative (for example the Journal officiel, INSEE, Banque de France, the IRS or the Social Security Administration). To revise a rent, sign or challenge a contract, or file a return, check the value at the source or with a professional.
Read next
Full pillar →The Real Estate Credit Cycle: Credit, Volumes and Price Dynamics
Reading framework This page develops one analytical strand of the Real Estate pillar. It formalizes the central mechanism…
Interest Rates and Real Estate Purchasing Power: The Mortgage Capacity Mechanism
Reading framework This page is a focused branch of the Real Estate pillar. It formalizes the arithmetic relationship…
Rental Property Returns: From Gross Yield to Net-Net Profitability
Real estate is not a yield asset: it is a credit asset. The advertised rental yield depends more…