
Crypto Regulation: What It Changes, What It Doesn’t, and Where Risks Remain
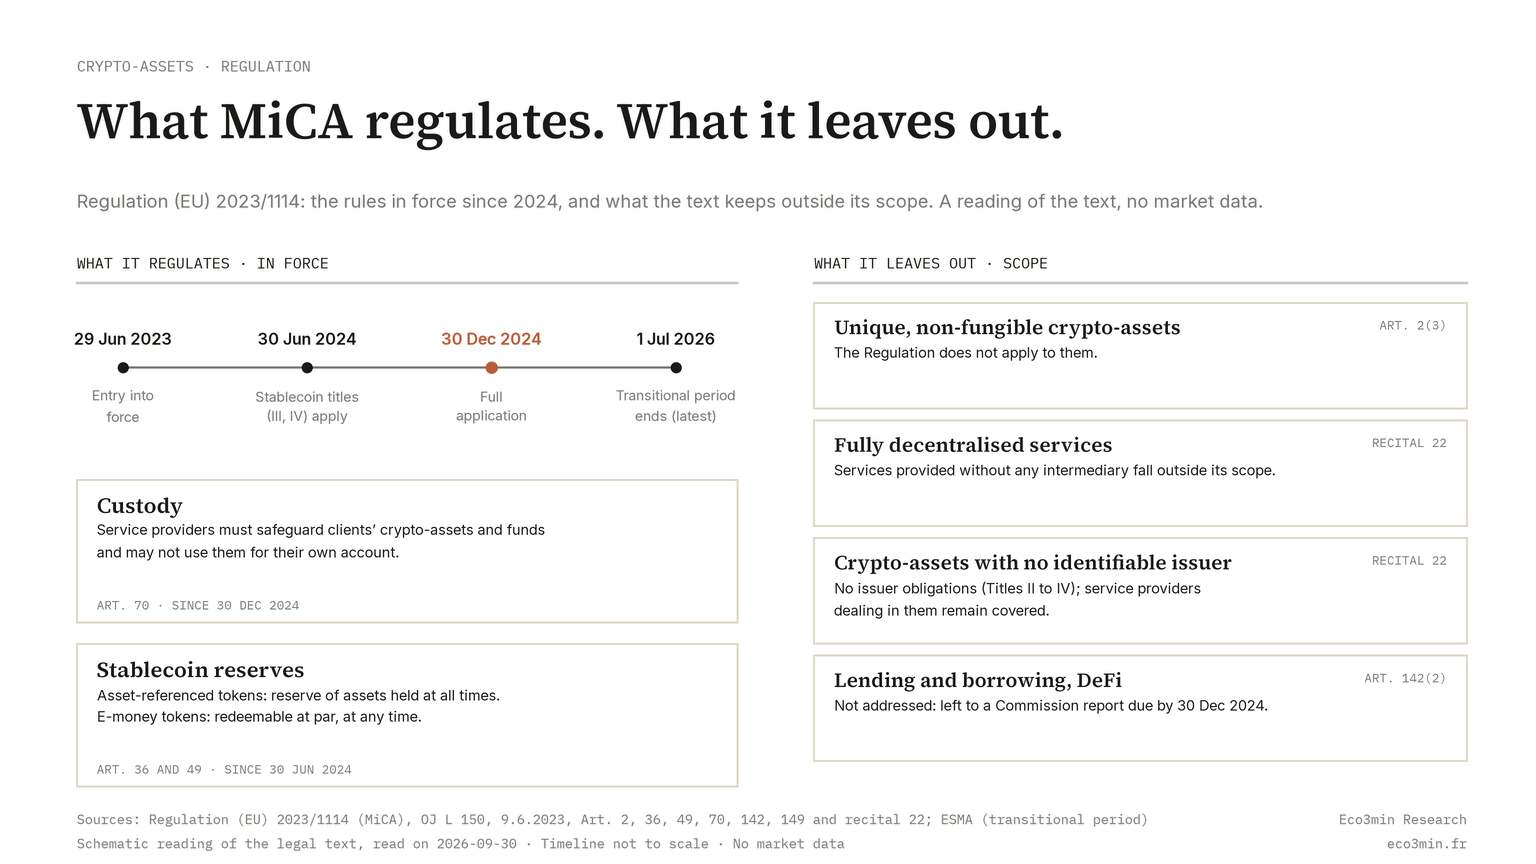
Sources: Regulation (EU) 2023/1114 (MiCA), OJ L 150, 9.6.2023; ESMA (transitional period) · Eco3min Research.
Regulation can curb the most blatant excesses: it cannot transform the nature of crypto-assets into stable and predictable instruments. Structural risks (procyclical liquidity, concentration, volatility) persist beyond legal frameworks. Normalization reshapes risks; it does not eliminate them.
In November 2022, FTX, then one of the world’s largest crypto exchanges by volume (CoinGecko), collapsed in 10 days. Six months earlier, its investors (Sequoia, SoftBank) had valued it at $32 billion. Estimated balance-sheet hole: $8–10 billion in misappropriated customer funds (liquidator John Ray III report, Delaware court). The same year: Celsius (bankruptcy, $4.7B liabilities, SDNY court), Voyager Digital (bankruptcy, $1.3B), Three Arrows Capital (bankruptcy, $3.5B). In May 2022, the algorithmic collapse of Terra/Luna had already erased tens of billions of dollars in market cap within days (CoinGecko). Total ecosystem losses between November 2021 and November 2022: close to three quarters of market capitalization destroyed (CoinGecko). None of these failures were caused by a lack of technical regulation: all resulted from the absence of oversight over centralized intermediaries.
Eighteen months later, in January 2024, the SEC approved 11 spot Bitcoin ETFs. IBIT (BlackRock) posted the fastest launch inflows ever recorded for an ETF (Bloomberg). By March 2024, total crypto market cap had moved back close to its November 2021 peak (CoinGecko). The same institutional investors who had exited the ecosystem after FTX returned through regulated vehicles. This reversal illustrates the core thesis: regulation does not eliminate cycles, it changes the channels through which capital flows, the intermediaries that process it, and the protections (or lack thereof) available to investors.
MiCA: the European framework, what it covers, what it doesn’t
The European Union moved first with the MiCA (Markets in Crypto-Assets) regulation, implemented in two phases: stablecoins in June 2024, full scope in December 2024. The world’s first harmonized crypto-asset framework, MiCA covers 27 member states and ~450 million citizens (Eurostat).
What MiCA requires: three asset categories with specific obligations, asset-referenced tokens (indexed to baskets of assets: 100% reserves, regular audits, ESMA authorization), e-money tokens (fiat-pegged stablecoins: 100% reserves in bank deposits or liquid assets, issuer must be a licensed electronic money institution), other crypto-assets (mandatory white paper, issuer liability). Service providers (CASPs: Crypto-Asset Service Providers) must obtain authorization from national regulators (AMF in France) with AML obligations, investor protection, operational resilience, and segregation of client assets. Segregation directly responds to the FTX model (client funds commingled with platform capital). Segregation rules of that kind are the precondition regulators set before tokenized securities issued under a licensed framework can scale.
What MiCA does not cover: pure DeFi (protocols without identifiable intermediaries, such as Uniswap), non-fungible NFTs, and Bitcoin itself (which fits none of the three categories). Enforcement depends on national authorities: interpretation divergences are likely between AMF (France), BaFin (Germany), and CONSOB (Italy). The ability to enforce rules on entities based outside the EU (Binance: Cayman HQ, Tether: BVI domicile) remains the decisive test.
United States: the SEC, ETFs, and regulatory asymmetry
In the United States, the regulatory approach remains fragmented among the SEC (Securities and Exchange Commission), CFTC (Commodity Futures Trading Commission), FinCEN, OCC, and state regulators. The SEC adopted an aggressive stance under Chair Gensler (2021–2025): most crypto-assets other than Bitcoin are treated as securities subject to the 1933 and 1934 Acts. This expansive interpretation led to enforcement actions against the major platforms: Coinbase, despite being publicly listed, Binance and Kraken. Binance paid a $4.3B fine (DOJ/CFTC/Treasury, November 2023), Kraken a $30M settlement (SEC, February 2023).
The approval of spot Bitcoin ETFs (January 2024) created a historic regulatory asymmetry: Bitcoin now has an institutional access channel (regulated ETFs, tens of billions of dollars in assets within a year, Bloomberg), while most altcoins remain in legal uncertainty. Spot Ethereum ETF approval (May 2024, SEC) partially extended this channel, but only for ETH, not for DeFi tokens built on Ethereum. Congress is debating bills (FIT21, Stablecoin Act) to clarify SEC/CFTC jurisdiction and establish a stablecoin framework: the outcome will determine whether the U.S. maintains its lead in institutional crypto infrastructure or cedes it to Europe and Singapore.
Regulation stabilizes channels: not prices
Beyond constraint, regulation produces observable implicit stabilization effects. Legal clarity reassures institutions: ETF flows are structurally more stable than direct retail flows (massive net Bitcoin ETF inflows in the three months after launch, Bloomberg, versus Binance retail flows swinging sharply from month to month, CoinGecko). Stablecoin reserve transparency requirements (MiCA mandates monthly audits, 100% liquid reserves) reduce rumor-driven panic risk. Client asset segregation rules would theoretically have prevented the FTX structure.
But stabilization is partial. Liquidity cycles will continue to drive valuations: BTC/net Fed liquidity correlation is very high (Federal Reserve/CoinGecko, 2020–2024), independent of regulation. Bitcoin’s annualized volatility remains at least 60% (Bloomberg), several times that of the S&P 500. No regulation can reduce the volatility of a zero-cash-flow asset whose valuation depends entirely on future expectations and liquidity regimes. What such rules can and cannot reach is exactly the question of the scope of the US stablecoin framework. The analysis of regulation as an implicit stabilizer details these mechanisms. The Liquidity and Financial Conditions sub-pillar provides the macro framework governing crypto cycles beyond legal oversight.
Calmer swings, older causes. Where Bitcoin’s price swings have narrowed, the chronology points away from regulation. The easing began long before MiCA applied or spot ETFs existed, and reading the rules as its cause confuses concomitance with causality. The drivers sit on the market side: deeper liquidity, a broader base of participants, developed derivatives markets and, above all, a larger capitalization, which shrinks the percentage move a flow of given size can produce. Regulation then formalizes the filtering of the most fragile actors more than it starts it.
Two limits frame that reading. Realized volatility measures the average amplitude of past moves and nothing else: counterparty and fraud risk stay outside it, so a less volatile asset is not a safer one. And the 2022 collapses, violent inside the ecosystem, were absorbed without spreading to the traditional financial system, which is why no single crisis marks the passage to a calmer regime. A crypto shock that did propagate beyond the ecosystem would signal that the filtering of fragile actors had not worked.
The illusion of permanent liquidity
Crypto markets create the illusion of permanent liquidity: 24/7 trading, visible order books, stablecoins seemingly convertible anytime. This perception masks documented fragility.
Crypto liquidity is procyclical with a 3–5× amplification factor relative to traditional markets. In May 2022 (Terra/Luna collapse), Bitcoin bid-ask spreads widened sharply on non-US platforms (Kaiko Research), on Binance and even more on less liquid venues. Altcoin spreads reached 2–5%, making rational execution impossible. In March 2020, forced liquidations on BitMEX totaled $1.6B in 24 hours (BitMEX). In August 2024, liquidations exceeded one billion dollars in a single day during the Nikkei/carry trade flash crash (CoinGlass). Further on this: how the UST/Luna collapse reshaped crypto regulation.
Bitcoin ETFs, despite regulated structures, face similar risks: under extreme stress, share creation/redemption depends on authorized participants (APs) being able to buy/sell physical BTC on spot markets. If APs withdraw (as traditional market makers do during equity flash crashes), ETF prices can decouple from NAV: just like bond ETFs in March 2020 (dislocations of several percentage points between price and NAV in HYG and LQD for five days, Bloomberg). The ETF liquidity under stress analysis provides a framework applicable to crypto ETFs.
The concentration paradox: promised decentralization, real centralization
The crypto ecosystem presents a structural paradox: technologies designed to decentralize financial power have produced growing concentration at every layer.
Exchanges: Binance represents a dominant share of global spot volume (The Block, 2024). The top five platforms (Binance, Coinbase, Bybit, OKX, Kraken) account for the bulk of volume (CoinGecko). ETF custody: Coinbase Custody holds Bitcoin for most of the approved spot ETFs (SEC filings), a massive operational single point of failure for tens of billions of dollars in assets. Ethereum staking: Lido controls just under a third of staked ETH (Dune Analytics, 2024); the top three operators (Lido, Coinbase, Binance) control about half. DeFi: the top five protocols (Lido, Aave, EigenLayer, Maker, Uniswap) hold about half of total value locked (TVL, DeFiLlama 2024).
The FTX collapse demonstrated the consequences of such concentration: instant contagion to Alameda Research (trading arm), Genesis (lender), BlockFi (retail lender), all interconnected. Regulation (MiCA, SEC) raises compliance barriers → reinforces concentration among the most capitalized players (Coinbase, Binance) → the paradox deepens. The events that pushed regulators toward MiCA and the GENIUS Act are mapped in the digital shadow banking fragility framework from our depeg study. Promised decentralization gives way to institutional centralization: safer than FTX-style centralization, but centralization nonetheless.
Taxation: the tightening framework
Crypto taxation is becoming clearer and stricter across most jurisdictions. In France: individual capital gains are subject to the 30% flat tax (12.8% income tax + 17.2% social contributions) or, optionally, progressive income tax. Crypto-to-crypto trades are not taxable events, only fiat conversion is. Professionals (mining, frequent trading): BIC or BNC regimes depending on activity. Mandatory reporting of foreign exchange accounts (Form 3916-bis): €750 fine per undeclared account (€1,500 if value >€50,000). In the United States: crypto-assets are taxed as property, every transaction (including crypto-to-crypto) is a taxable event (IRS Notice 2014-21).
The international framework is tightening through CARF (Crypto-Asset Reporting Framework, OECD): automatic tax information exchange covering crypto transactions. Adopted by 48 jurisdictions (OECD, 2024), first implementation planned for 2027. EU platforms must already report under DAC8. Tax anonymity, long a feature of the ecosystem, is disappearing for users of regulated platforms.
Airdrops: apparent free gains, real costs
Airdrops, free token distributions, attract users with the promise of riskless gains. In practice, they involve documented risks. Adverse selection: airdrops attract users seeking immediate profit rather than project value, post-airdrop selling pressure is systematic (Uniswap’s UNI after the September 2020 airdrop and Arbitrum’s ARB after the March 2023 one both fell sharply in the following months, CoinGecko). Security risks: scam sites proliferate around popular airdrops, malicious contracts draining wallets, targeted phishing. Taxation: in some jurisdictions (US, UK), free tokens are taxable at market value upon receipt, investors may owe taxes on tokens whose price falls before filing. The airdrop analysis deconstructs these mechanisms.
The analysis of regulation as implicit stabilization details how oversight reshapes market dynamics. The ETF liquidity under stress study provides a framework applicable to crypto ETFs. The AI altcoins analysis documents risks of narratives detached from fundamentals.
← Back to pillar page Crypto-assets
Last updated — 20 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Regulated and tax values: the rates, indices, caps and brackets with legal effect cited on this page are set by official decision, change over time and apply according to individual circumstances. Only the official publication in force on the relevant date is authoritative (for example the Journal officiel, INSEE, Banque de France, the IRS or the Social Security Administration). To revise a rent, sign or challenge a contract, or file a return, check the value at the source or with a professional.
Read next
Full pillar →Stablecoin Reserves: What US Backing Rules Actually Require
The GENIUS Act sets what must sit behind every US payment stablecoin: a one-to-one reserve in high-quality liquid…
US Stablecoin Rules: How the Federal and State Framework Works
The GENIUS Act, signed into law on 18 July 2025, created the first comprehensive federal framework for payment…
Bitcoin and Liquidity Cycles: Real Rates, Macro Regimes, and Market Behavior
Fed total assets and net liquidity, Wednesday levels, January 2020 to October 2026. Sources: Federal Reserve Board, H.4.1…