
WALCL: Meaning of the Fed Balance Sheet, FRED Calculation, Assets and Liabilities

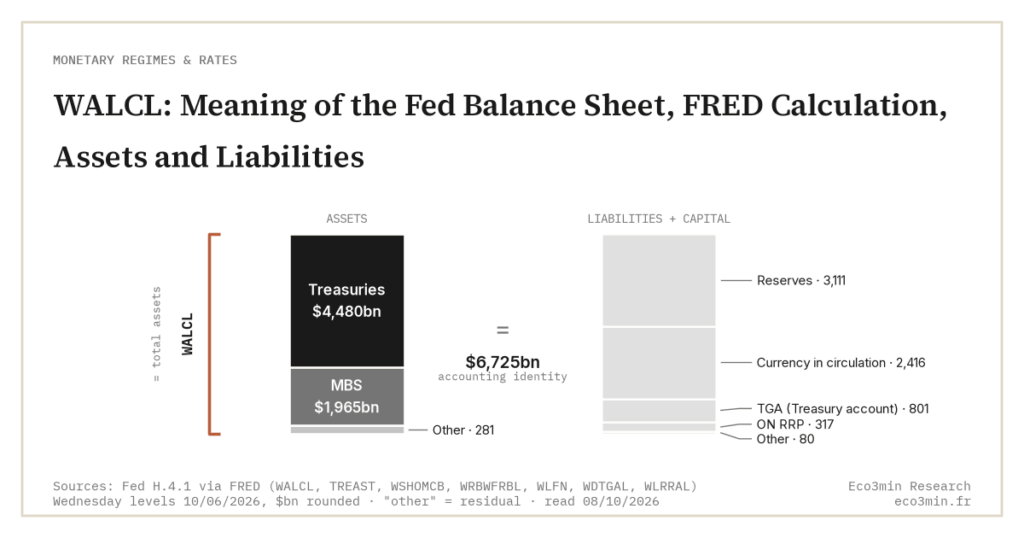
The WALCL ticker published weekly by FRED measures precisely the total assets held by the consolidated Federal Reserve System. This strict definition excludes the liability side, flows, and three objects regularly conflated with it: M2, monetary base, and market liquidity.
TL;DR
WALCL reports the book value of total Federal Reserve assets each Wednesday, yet it is routinely conflated with M2, the monetary base, and system liquidity, three things it never measures.
- The series comes from the H.4.1 release published every Thursday by the Board of Governors; FRED diffuses its Total Assets line as a weekly series running since December 2002.
- WALCL carries securities at amortized cost, not market value, so the $1.08 trillion of unrealized SOMA losses at end-2022 ($948 billion at end-2023) never appears in the series.
- M2 (M2SL) fell 4.8% from its April 2022 peak to its October 2023 trough and was back at its end-2021 level by December 2024, while WALCL dropped 23% from its April 2022 peak to end-2024, a structural decoupling rather than a statistical artifact.
- In December 2025 the monetary base sat about $1.2 trillion below WALCL, because ON RRP and the Treasury General Account fall on the liability side.
Three analytical conflations drive the most common misreadings of the ticker. Dispelling them requires returning to the exact technical perimeter of the Board of Governors’ H.4.1 release.
WALCL is a FRED acronym that expands as Total Assets of the Federal Reserve. The series is fed by the H.4.1 release (“Factors Affecting Reserve Balances of Depository Institutions and Condition Statement of Federal Reserve Banks”) published every Thursday by the Federal Reserve System’s Board of Governors. FRED at the St. Louis Fed extracts the Total Assets line and diffuses it as a continuous weekly series, available since December 2002. This technical genealogy conditions everything the ticker can, and cannot, mean.
Before examining the recurring conflations that distort its reading, the strict definition needs to be isolated: it excludes the liability side of the Fed balance sheet, monetary flows within a period, and three economic aggregates that general media routinely treat as equivalent to WALCL even though they measure distinct objects. The relevance of WALCL as a monetary-stance indicator only fully crystallizes once these boundaries are drawn.
The exact technical perimeter of the series
WALCL aggregates every asset held by the twelve consolidated Federal Reserve Banks, expressed in book value as of the Wednesday of the reference week. The H.4.1 release details five main categories: Treasuries (Bills, Notes, Bonds, TIPS and FRNs), agency MBS (Fannie Mae, Freddie Mac, Ginnie Mae), repurchase agreements, primary credit via the discount window, and a residual line grouping gold, special drawing rights, interbank balances and special facilities. The sum of these lines, net of internal accounting offsets, constitutes the WALCL ticker. As of June 10, 2026, WALCL stood at $6,725 billion, including $4,480 billion of Treasuries and $1,965 billion of MBS; on the liability side, reserve balances ($3,111 billion) and currency in circulation ($2,416 billion) made up most of the total.
Frequency and timing matter. The data reflects a stock snapshot taken at the close of Wednesday, communicated late Thursday afternoon Eastern time. It does not register the daily flows of purchases or sales: open-market operations conducted between two Wednesdays only appear net in the following week’s balance sheet. Tracking fine policy flows requires supplementing WALCL with the quarterly SOMA (System Open Market Account) reports and the operation calendars published by the NY Fed. Related Q&A: reading the Fed balance sheet beyond QE headlines.
The liability side of the Fed balance sheet (bank reserves, ON RRP, Treasury General Account, currency in circulation, foreign and institutional accounts) sits in the same H.4.1 release but constitutes a separate section. WALCL does not re-aggregate any of these lines. By accounting identity, total assets = total liabilities; but the distribution across asset lines and the distribution across liability lines are two independent variables that monetary policy can move separately. This independence is crucial for understanding what the ticker omits about market liquidity.
FRED also maintains several derived or parallel series that must be distinguished from WALCL to avoid misreadings. WSHOSHO measures the SOMA portfolio alone, excluding facilities. WALCL includes SOMA but adds repos, primary credit and facilities. WLCFLPCL measures primary credit extended to depository institutions through the discount window and is a subset of WALCL. Professional reading of Fed data requires selecting the series that exactly matches the question being asked. For direct time-series access and methodological notes, the FRED H.4.1 dataset page provides the canonical entry point.
One additional technical subtlety deserves attention: the H.4.1 release records securities at face value and reports unamortized premiums and discounts on a separate line included in the total, so WALCL tracks amortized cost, not market value. This accounting convention means WALCL does not capture unrealized capital losses on the Fed portfolio during rate-hiking cycles. According to the Reserve Banks’ combined financial statements for 2023, the fair value of the SOMA portfolio stood $1,080 billion below amortized cost at end-2022 and $948 billion below at end-2023, none of which appears in the WALCL series. For analysts comparing the Fed balance sheet to commercial bank balance sheets (which mark a fraction of holdings to market), this convention difference is material. Related coverage: WALCL-to-GDP: the Fed balance sheet ratio in international comparison.
Three analytical conflations to dispel
The first conflation equates WALCL with the M2 monetary aggregate. M2 measures liquid holdings of the non-bank private sector: currency in circulation outside banks, demand deposits, savings deposits, retail money market funds, certificates of deposit under $100,000. This aggregate is published monthly by the Fed in the M2SL series and reflects the money stock held by US households and non-financial corporates. WALCL, in contrast, measures the stock of financial assets held by the central bank itself. The two variables do not move in parallel. M2 fell 4.8% between its April 2022 peak and its October 2023 trough, then was back by December 2024 at its end-2021 level ($21,488 billion against $21,503 billion), while WALCL lost 23% between its April 2022 peak ($8,965 billion) and end-2024 ($6,886 billion). The decoupling is structural, not a statistical anomaly.
The second conflation equates WALCL with the monetary base. The monetary base stricto sensu consists of the Fed’s monetary liabilities alone: currency in circulation plus bank reserves. The Fed publishes this concept in the H.6 release (series BOGMBASE), distinct from H.4.1. In December 2025, the monetary base ($5,374 billion) was roughly $1.2 trillion smaller than the monthly average of WALCL ($6,571 billion), because the ON RRP and TGA, which sit on the liability side of the Fed balance sheet, do not constitute monetary base in the classical monetarist sense. Conflating the two leads to overestimating the quantity of money injected into the commercial banking system.
The third conflation, and probably the most damaging for market analysis, equates WALCL with the financial system’s effective liquidity. Research published notably by NY Fed staff on the ample reserves regime since 2018 has established that the liquidity accessible to market participants depends primarily on liability-side variables of the Fed balance sheet, bank reserves and ON RRP, and on variables external to that balance sheet (money market fund positioning, hedge funds’ collateral demand, foreign bank balances). Aggregate WALCL captures none of these dimensions directly. The distinction between financial conditions and systemic liquidity is precisely what a raw reading of WALCL erases.
Reading “the Fed balance sheet reaches $X trillion” as “the Fed injected $X trillion of liquidity into the system” is the most common extrapolation. The gap between asset side (WALCL) and monetary liabilities (base, reserves) can reach 30 to 40% (39% in October 2022, about 18% at end-2025): translating an asset move into a liquidity effect requires unpacking liability components.
Practical consequences of the strict definition
First consequence: a weekly WALCL variation never translates directly, on the same time horizon, into an effect on monetary aggregates or on effective liquidity. The transmission belt passes through relays with their own lags: several weeks for short interbank-rate adjustment, several months for broad monetary aggregates, several quarters for bank credit volumes. An instantaneous reading of the ticker is only relevant for variables whose adjustment is itself immediate: term premia on the Treasury curve, large-cap credit spreads, repo-market funding conditions. This finding is put in perspective by the Eco3min frame for financial conditions.
Second consequence: comparing WALCL across periods requires neutralizing composition changes. Comparing WALCL in 2014 (between $4,020 and $4,510 billion) with WALCL in 2025 (between $6,540 and $6,850 billion) only carries analytical meaning once changes in the instrument-level distribution are neutralized, which is precisely what the instrument-by-instrument breakdown of assets develops. Reading by total size alone masks doctrinal shifts.
Third consequence: international comparisons of WALCL in raw value carry no relevant economic information. They require either GDP normalization or relative variation over homogeneous periods. This methodological discipline applies to Fed-vs-ECB, Fed-vs-BoJ, or Fed-vs-BoE comparisons, but also to comparing the Fed with itself across periods with different underlying economic structures.
Finally, the strict definition imposes specific vigilance during transition periods. When a new temporary facility program opens (BTFP in March 2023 for example, or the March 2020 Covid facilities) WALCL mechanically integrates loans extended under the program, but this integration does not reflect a balance-sheet expansion intent: it reflects emergency funding demand from counterparties. Reading a WALCL jump in these circumstances as a discretionary emergency QE misreads the program’s nature. Conversely, when these facilities close or are fully repaid, WALCL falls without signaling a discretionary QT.
A fourth, often overlooked, consequence concerns the relationship between WALCL and Treasury market microstructure. When the Fed conducts large open-market operations, the impact on Treasury yields depends not only on the quantity transacted but also on the maturity bucket targeted, the auction calendar of new Treasury issuance, and the positioning of primary dealers. None of these microstructure dimensions appears in WALCL, which only records the resulting stock change. Analysts who treat WALCL as a sufficient proxy for the Fed’s influence on Treasury yields systematically underestimate the role of these intermediation variables.
A fifth consideration concerns the political and institutional dimension. WALCL is reported in nominal dollar terms with no automatic adjustment for inflation, growth of the underlying economy, or shifts in the composition of bank balance sheets. A balance sheet of $4 trillion represented roughly 23% of US GDP in 2014; the same nominal amount would represent only about 12% of GDP in the second quarter of 2026. For long-run institutional analysis, this matters: the Federal Reserve’s footprint on the economy is not a function of absolute dollar size but of size relative to the system it influences. The strict definition of WALCL provides the raw input; meaningful interpretation requires the contextual variables that the ticker alone does not supply.
Professional reading of WALCL therefore requires disciplined attention: recognizing the exact perimeter, refusing implicit substitution with M2 or monetary base, and always cross-checking with liability components and NY Fed operational flows. Without this discipline, the ticker lends itself to all possible interpretations, which makes it, paradoxically, one of the most misread indicators in contemporary macro-finance.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →WALCL — Fed Balance Sheet, Monetary Signal and Systemic Liquidity Indicator
Since 2008, the Federal Reserve's balance sheet aggregated in the WALCL ticker has become the Fed's effective monetary…
Central Banks Diverge: Fed, ECB, BoE and BoJ After the Easing Cycle
After a shared easing cycle, the Fed and the ECB are hiking again, the BoE hesitates and the…
The Yield Curve: What the Level Says That the Slope Doesn’t
A flat curve can sit at 1.5% or at 4.2%: the slope is the same, but the cost…