
Gold and Central Banks: The Record Buying Wave 2022-2026 and the Slow De-Dollarization

Net seller until 2009, the global official sector became a structural gold buyer from 2022 onward, with annual volumes (roughly 1,080 tonnes in 2022) doubling those of the prior decade.
TL;DR
Net seller until 2009, the global official sector turned structural gold buyer from 2022, absorbing roughly 1,080 tonnes that year, close to a quarter of global demand.
- Three years of rupture: more than 1,000 tonnes a year from 2022 to 2024, between 1,051 and 1,092 t in the World Gold Council’s revised figures, versus 473 t/year on average over 2010-2021.
- A concentrated core of emerging-market buyers: Turkey added 148 t in 2022, Poland 130 t in 2023, China declared ~316 t from late 2022 to April 2024.
- The early-2022 freeze of roughly $300 billion in Russian reserves is inferred as the trigger, gold escaping freeze risk because it is held physically in national vaults.
- The dollar's share of COFER reserves fell from 71.0% (end-1999) to 56.7% (Q2 2026), a slow de-dollarization that gold purchases, excluded from COFER, do not capture.
This buying wave constitutes an underestimated driver in macro analyses of gold prices, and a signal of slow reserve de-dollarization readable in IMF COFER data.
For three decades, central banks represented the blind spot of gold price analysis. Net sellers from the 1990s through the GFC, their return as structural buyers from 2010 was first read as a post-crisis normalization. The near-instantaneous doubling of volumes in 2022 changes the nature of the phenomenon: what was a marginal diversification becomes a structural driver of price formation. To situate this driver within the complete analytical grid, the global monetary signal reading of gold makes it one of the three central channels. This article deploys the application angle: who buys, how much, why, and with what consequences on the international monetary system.
From Net Seller to Structural Buyer: the 1990-2024 Sequence in Four Phases
The trajectory of the official sector on the gold market organizes into four clear phases, each bracketed by datable institutional inflections.
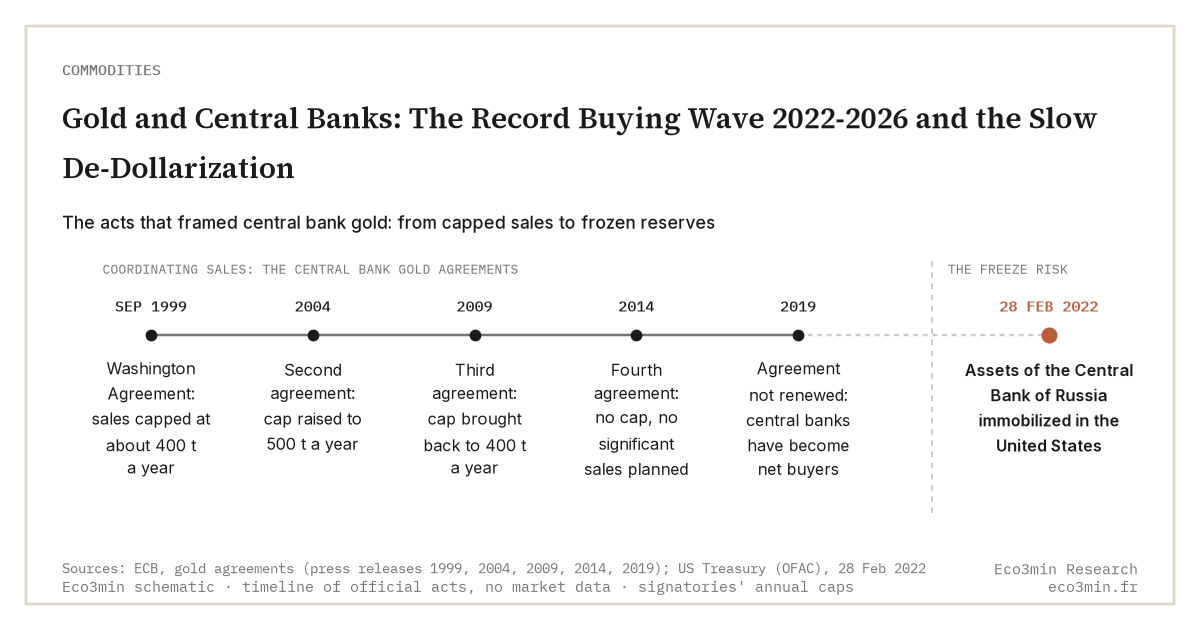
Phase 1 (1990-2009): net seller. Over this period, central banks are net sellers of several hundred tonnes a year. The most emblematic disposals of the decade are those of the Bank of England, which sells 395 tonnes between 1999 and 2002, the Brown Bottom sequence, since it coincides with the price trough of $256 an ounce on average in July 1999 (World Bank). The September 1999 Washington Agreements cap annual sales by European signatories (primarily eurozone central banks plus Sweden and Switzerland) at approximately 400 tonnes per year over five years. The 2004 Central Bank Gold Agreement raises the cap to 500 tonnes, and the 2009 agreement brings it back to 400 tonnes (ECB). These caps, designed as a market-stabilization measure, in fact mark the last act of the net-seller regime. The fourth agreement, of 19 May 2014, sets no cap at all: its signatories state they have no plans to sell significant amounts of gold. On 26 July 2019 they decided not to renew it, noting that central banks had become net buyers (ECB). The wider context: the real-rate sensitivity of gold.
Phase 2 (2010-2021): return to moderate net buying. From 2009-2010, in the immediate wake of the GFC, the official sector flips. Emerging economies (China, Russia, India, Turkey, Kazakhstan primarily) initiate sustained buying programs. Over the decade, average annual net purchases come to 473 tonnes per the World Gold Council. That level has little visible effect on price formation: the classical two-variable grid (real yields plus dollar) suffices to account for moves observed 2010-2021.
Phase 3 (2022-2024): quantitative break. The sequence shifts brutally from 2022 onward. Annual official-sector purchases double, and the doubling persists for three consecutive years: more than 1,000 tonnes each year, between 1,051 and 1,092 tonnes in the revised figures of the World Gold Council’s Gold Demand Trends reports. These volumes represent between 21% and 23% of annual global gold demand, OTC included (roughly 4,750 to 4,960 tonnes depending on the year).
Phase 4 (2025-2026, ongoing): purchases still elevated but lower, at 863 tonnes in 2025 and 345 tonnes in the first half of 2026, the weakest first half since 2022 (World Gold Council). Both remain above the 2010-2021 average pace of 473 tonnes a year. The question of durability beyond 2026 remains open and is the subject of conflicting analyses.
The Record 2022-2024 Volumes: What the WGC Numbers Show
Figures published by the World Gold Council in its quarterly Gold Demand Trends reports and its annual report constitute the reference source for global official flows. The WGC cross-references IMF official declaration data (each signatory central bank publishes its reserves monthly in the International Financial Statistics) with its own field analyses and confidential sources at refineries and bullion banks.
The distinction between declared and inferred purchases is analytically important. Declared purchases correspond to gold reserve variations published to the IMF; they are audit-quality but may omit operations not booked as official reserves (for instance purchases held in distinct sovereign entities, sovereign wealth funds, or off-balance-sheet central bank accounts). The WGC adds to the declarations an estimate of unreported purchases, which has become the majority: IMF data reflected only 47% of its estimated total in 2023 and 34% in 2024, and the unreported share reached 57% in 2025 (World Gold Council). The WGC does not break this share down by country: the Chinese purchases it cites are those the PBoC publishes.
The breakdown between net buyers and net sellers is also instructive. Over 2022-2024, some central banks remain sellers (Kazakhstan, the largest seller in 2022 and 2023, Uzbekistan, the Philippines in 2024, the Bundesbank for a few tonnes tied to coin minting), but the global net balance remains massively buyer. The break is therefore not a binary flip but a shift in the weighted average toward buying.
Concentrated Buyers: an Identifiable Core and Partial Declarations
Over the 2022-2024 sequence, the main declared buyers concentrate within an identifiable core. Turkey’s CBRT was the largest reported buyer of 2022, adding 148 tonnes that lifted its official reserves to a record 542 tonnes, before selling in 2023 and again in the first quarter of 2026 (World Gold Council). China’s PBoC announces regular monthly purchases between late 2022 and mid-2024, totaling roughly 316 declared tonnes over that window, after a three-year pause in official declarations. India’s RBI acquired between 16 and 73 tonnes a year from 2022 to 2024. Poland’s NBP acquired 130 tonnes between April and November 2023, exceeding its stated 100-tonne target, then was the world’s largest buyer in 2024 and 2025 (102 tonnes in the latter year). Singapore’s MAS added 69 tonnes in Q1 2023 (77 tonnes over the year), the only buyer among advanced economies. The Czech National Bank completes the group with steady accumulation, around 20 tonnes a year in 2024 and 2025. A complementary angle: the physical pull of gold toward China and India.
This core shares two characteristics. First characteristic: the buyers are predominantly central banks of emerging or semi-emerging economies, with the notable exceptions of Singapore and Poland. Second characteristic: their prior gold exposure, measured as a percentage of total reserves, was substantially below historical European levels (typically 5-15% versus 60-70% for France, Italy, Germany, or 75% for the United States). A significant portion of the 2022-2024 purchases can therefore be read as convergence toward historical ratios of large economies, but stated motivations often exceed this technical rebalancing.
Motivations: Diversification, Sanctions, Dollar Expectations
Official statements from buying central banks converge on three logics, with weightings varying by country.
First logic: reserve diversification within the context of growing awareness of dollar concentration. This logic is systematically mobilized in official communications because it is technically unimpeachable and politically neutral. It invokes classical portfolio-management principles applied to sovereign reserves: reduced concentration on a single asset, search for low correlation with existing holdings.
Second logic: response to financial sanctions. This logic never appears explicitly in official statements, but it is inferable from time sequences. The case is built out in this analysis of central banks gold accumulation. The post-Crimea annexation sequence in March 2014 marked a first trigger, with an acceleration of Russian and Chinese purchases over 2014-2018. The early-2022 freezing of Russian dollar and euro reserves, roughly $300 billion immobilized in Western central bank accounts, constitutes the phase 3 trigger: it signals to non-Western central banks that reserve assets denominated in adversarial-jurisdiction currencies carry tangible and activatable geopolitical risk, no longer merely theoretical. In the United States the freeze dates from 28 February 2022, when the Treasury’s Office of Foreign Assets Control prohibited transactions with the Central Bank of Russia. Its assets held in the United States or by US persons were in effect immobilized. The arbitrage channel between sanctionable and non-sanctionable assets structurally reorients toward gold, which cannot be frozen since it is held physically in national vaults or in vaults for buyer-country accounts. This analysis is also consistent with the international arbitrage channel between gold and the dollar which then deploys differently from prior cycles.
Third logic: expectations regarding the dollar’s structural role in the international monetary system on decadal horizons. This logic invokes a long-term scenario in which the dollar progressively loses its position as sole reserve currency in favor of a heterogeneous basket. It is more rarely owned publicly by buyers but transpires in some political statements, notably Chinese and Russian, on the internationalization of the yuan or the development of settlement channels that bypass the dollar. Each option is weighed on its own terms in our dollarization-versus-de-dollarization comparison.
The Slow De-Dollarization of Reserves: What COFER Shows
The massive gold purchases deploy within a broader macro frame: the slow de-dollarization of global FX reserves. According to IMF COFER (Composition of Official Foreign Exchange Reserves) data, published quarterly with a lag of roughly one quarter, the dollar share of allocated foreign-exchange reserves stood at 71.0% at end-1999 (start of the series), at 64.2% at end-2015 and at 56.7% in Q2 2026. These are the revised data released on 30 September 2026: a cumulative erosion of roughly 14 percentage points over twenty-six and a half years.
Several analytical caveats apply to this series. First caveat: COFER measures only foreign-currency assets (cash, deposits, sovereign and corporate securities), and explicitly excludes gold. The complete balance dollar plus gold plus other currencies therefore does not read in a single series. Second caveat: the composition reported to the IMF is partial, and the IMF now imputes it for countries that do not report it, 10.6% of reserves in Q2 2026. Third caveat: the 14-point dollar decline has been absorbed by several sources, euro, yuan, other emerging-market currencies, and off-COFER gold. The exact share attributable to gold remains estimative. Further detail: gold measured in March 2026 dollars.
The pace of this de-dollarization remains slow. Over the period, 14 points represent roughly 0.5 points per year on average. The recent pace, roughly 0.6 points a year from end-2021 to Q2 2026, remains close to that average. Extended as is, it would take the dollar below 50% in eleven to twelve years. This inertia is analytically important: it distinguishes effective de-dollarization (slow, observable in the data) from de-dollarization expectations (potentially rapid, embedded in gold prices).
What This Wave Means for Price Formation
The analytical contribution of the 2022-2024 buying wave to the gold price reading is threefold.
First contribution: a structural demand floor. An annual flow of 1,000 to 1,100 tonnes represents 27% to 30% of global mine output (3,650 to 3,670 tonnes a year in 2024-2025 per the WGC) and more than a fifth of total demand. This flow mechanically constitutes a demand base that did not exist in prior cycles. That base does not set a particular price, but it reduces the potential downward pressure in case of rising real yields, as the 2022-2024 decorrelation illustrated.
Second contribution: a signal on long-term expectations. Central banks manage their reserves over multi-decadal horizons, with real-value preservation rather than short-term performance objectives. Their massive purchases signal a collective anticipation on the structural trajectory of the dollar and the international monetary system, independent of short rate cycles.
Third contribution: a potential instability trigger if the wave reverses. If official purchases return to 2010-2021 levels (473 tonnes a year on average), the structural demand floor erodes and the price becomes fully exposed again to the classical real yields plus dollar channel. The quarterly share of official purchases in total demand published by the WGC is the indicator that tracks such a regime correction. For the reading of the current regime and its conditional fragility, the $3,000+ regime and the institutional floor proposes a complete interpretive reading.
To situate this wave in the broader macro panorama of effects from a durable strong-dollar regime, the safe-haven myth empirical examination connects with the broader debate on gold’s role under regime shifts. The page on the physical-commodity geoeconomics editorial space aggregates connected analyses.
- Net seller until 2009 (Brown Bottom, 1999 Washington Agreements), the global official sector became a structural buyer from 2010, then a massive buyer from 2022 (more than 1,000 t a year from 2022 to 2024, then 863 t in 2025, World Gold Council).
- The buyer core is concentrated: Poland, China, Turkey, India, Singapore, Czechia, predominantly central banks of emerging or semi-emerging economies.
- Three logics motivate the purchases: diversification (official), response to sanctions and the 2022 Russian asset freeze (inferred), long-term expectations on the dollar’s role (rarely owned).
- COFER reserve de-dollarization remains slow (56.7% in Q2 2026 versus 71.0% at end-1999), but constitutes the macro frame within which the massive gold purchases, invisible in COFER, take place.
Last updated — 6 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Gold as a Monetary Signal: Real Yields, the Dollar and Central Bank Buying
Gold prices do not track inflation: they track the monetary opportunity cost of holding, itself driven by real…
Pure-play refiners versus integrated majors: downstream margin exposure
A pure-play refiner owns only the downstream, so its earnings track the refining margin. An integrated major also…
Jet fuel, the forgotten margin: the jet crack and the aviation link
The 3-2-1 crack spread reduces the refining margin to two products, gasoline and diesel. Jet fuel sits outside…