
European Natural Gas: Low Storage Pushes the Strain Into the Next Winter
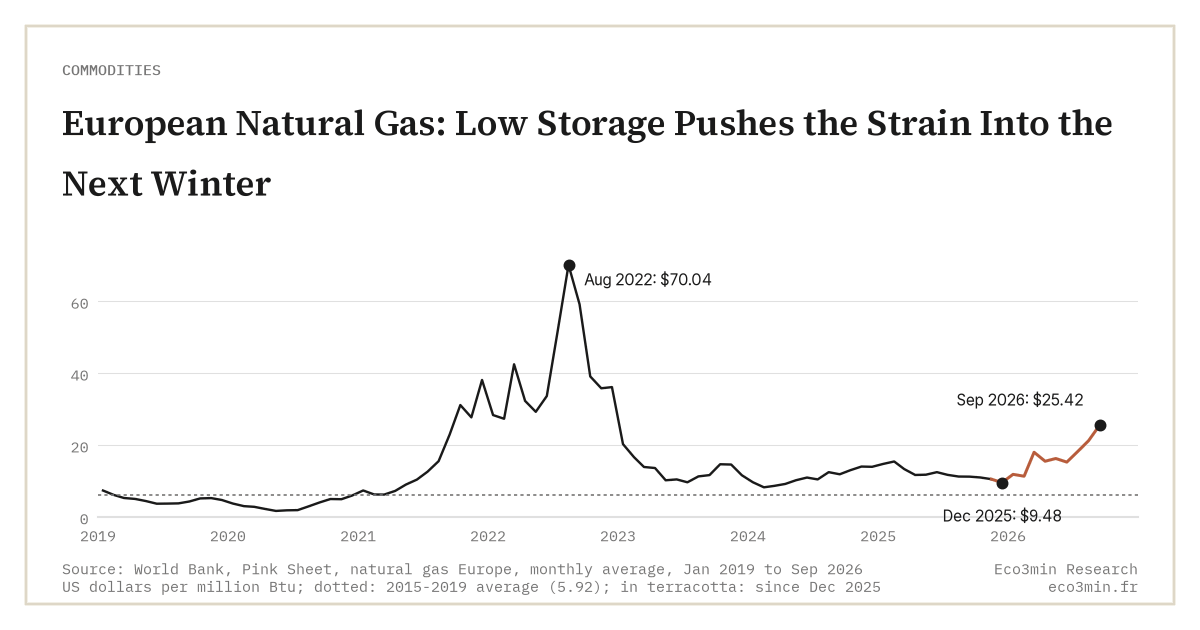
Europe entered the 2025-2026 winter with storage 82.8% full against a 92.3% average, and its gas price has risen 2.7-fold since.

European gas storage acts as a buffer between imports that arrive year-round and consumption concentrated in winter. When it comes out of a winter low, purchases the following summer rise, and the cost of refilling is carried into the next season.
In autumn 2025, European storage was already well below its five-year average. The 2026 shock turned that shortfall into a price surge, while US gas stayed cheap.
TL;DR
A winter that starts with low storage is paid for the next summer: Europe entered 2025-2026 at 82.8% full, and its gas price has risen 2.7-fold since.
- EU storage was 82.81% full on November 1, 2025, against a 2020-2024 average of 92.33% (GIE AGSI).
- It fell to 27.62% on March 31, 2026 and was only 72.97% full on October 6, 17.6 points below the average for that date.
- European gas cost $9.48 per million Btu in December 2025 and $25.42 in September 2026, 8.6 times the US Henry Hub price (World Bank, EIA).
A winter that began below average
According to filling data published by Gas Infrastructure Europe (GIE, AGSI platform), EU gas storage peaked for 2025 on October 12, at 83.15% of capacity. On November 1 it stood at 82.81%. Across 2020 to 2024, the average for that date was 92.33% (Eco3min calculation on AGSI data).
The prevailing view at the time saw a calm market: moderate prices and storage judged sufficient. The World Bank’s Pink Sheet put European gas at $10.42 per million Btu in November 2025 and $9.48 in December, against $15.34 in February 2025. Low storage and a low price are not contradictory. They can simply reflect weak demand and buyers postponing purchases.
EU storage rules had in fact been relaxed. Regulation (EU) 2025/1733 of July 18, 2025 keeps the 90% target but allows it to be met at any point between October 1 and December 1, and permits a 10-point deviation under difficult market conditions.
The winter that drained reserves
Withdrawals over winter 2025-2026 ran deep. Storage was 40.53% full on February 1, 2026, against a 60.11% average for that date over 2020-2024. It hit 27.62% on March 31, its low point, then 27.89% on April 1, against an average of 45.32%. The EU agency for energy regulators (ACER) notes that storage came out of winter below 30%.
The Middle East shock came on top. Following attacks on energy facilities, ACER notes that the Dutch TTF hub price rose above €60 per megawatt-hour during the winter. The Pink Sheet European price went from $11.24 in February to $17.91 in March.
An empty tank is refilled at today’s price.
The cost of refilling
Refilling storage over summer 2026 meant buying large volumes of liquefied natural gas while Gulf supply was disrupted. ACER estimated the extra filling bill at €10 to €15 billion to reach 80%, and calculated that reaching 90% would require about 13% more LNG imports than in 2025. The European Commission invited member states to consider a target lowered to 80%, which the regulation’s flexibility allows.
Prices followed. European gas cost $15.17 per million Btu in June 2026, $21.11 in August and $25.42 in September, according to the World Bank: 2.7 times the December 2025 level and more than four times the 2015-2019 average of $5.92. On October 6, 2026, EU storage was 72.97% full (an AGSI estimate), against a 90.59% average for that date over 2020-2024.
A European price, not a global one
In the US, the largest gas producer, the Henry Hub spot price published by the EIA stayed between $2.77 and $3.15 per million Btu on monthly averages from April to September 2026, after a spike to $7.72 in January. In September, European gas therefore cost 8.6 times US gas. Europe imports most of its gas and pays the price of the last LNG cargo it needs, while a producing country mainly pays its extraction cost.
- Storage levels going into winter determine how much is bought back the following summer, and thus the next season’s price.
- The EU entered winter 2025-2026 at 82.8% and winter 2026-2027 at about 73%, both times below the five-year average.
- European gas prices rose 2.7-fold between December 2025 and September 2026, while Henry Hub stayed near $3.
What would undo the carried-over strain
A mild winter 2026-2027 would reduce withdrawals and the volume to buy back in 2027. A lasting reopening of Gulf routes would bring LNG supply back to the world market. Weaker European industrial demand would work the same way. Conversely, a cold winter starting from 73% storage could take it below its March 2026 low.
The indicator to watch is the gap between the filling rate and its five-year average, published daily by AGSI: it measures how much Europe will have to buy back, more than the price of the day. The wider framework of commodity transmission is developed in our breakdown of commodities as macroeconomic regime signals, and the link from expensive gas to inflation in natural gas pass-through to European inflation.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Commodities and the Business Cycle: A Leading Indicator of Economic Regimes
Year-over-year change in the World Bank commodity price index (Total Index, 2010=100) leads US consumer price inflation by…
Pure-play refiners versus integrated majors: downstream margin exposure
A pure-play refiner owns only the downstream, so its earnings track the refining margin. An integrated major also…
Jet fuel, the forgotten margin: the jet crack and the aviation link
The 3-2-1 crack spread reduces the refining margin to two products, gasoline and diesel. Jet fuel sits outside…