
Bank Lending Channel: How Banks Shape Monetary Transmission

Monetary transmission depends on a frequently overlooked link: the banking system. Central bank decisions alter overall financial conditions, but their real impact on the economy is mediated by banks’ ability to lend: a capacity constrained by balance sheets, prudential regulation, and risk appetite.
TL;DR
Lower policy rates cut banks' funding costs, but Basel III capital ratios and risk aversion decide whether credit actually expands, so a single cut reaches large firms and SMEs unevenly.
- The average CET1 ratio of significant euro-area banks was 16.1% in mid-2025 (ECB supervisory banking statistics), yet several Southern European banks near their Pillar 2 thresholds cannot expand exposures even as rates fall.
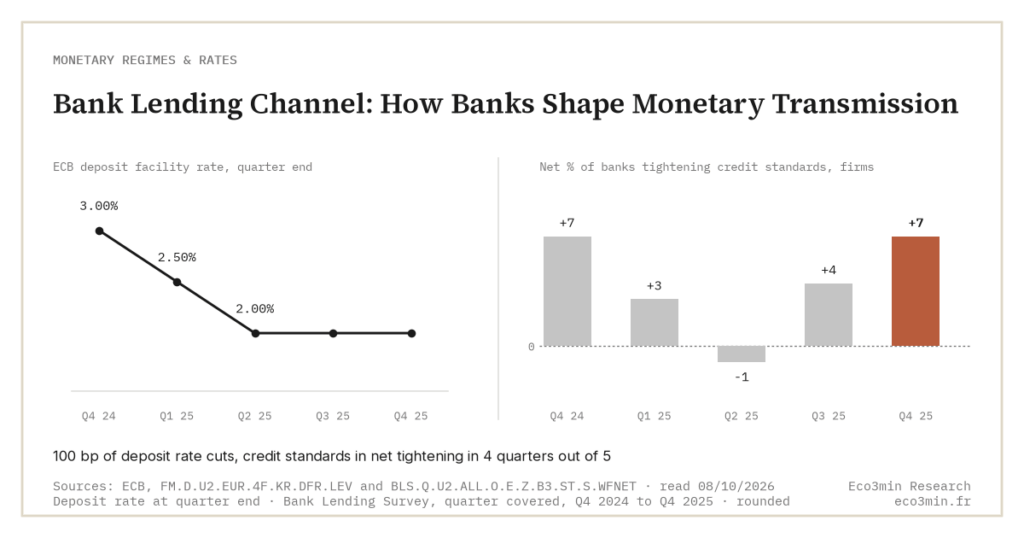
- A deposit rate cut from 3.00% at end-2024 to 2.00% in June 2025 did not stop a net 7% of banks from tightening credit standards for firms in Q4 2025 (ECB Bank Lending Survey), separating the price of credit from its availability.
- The channel can become an amplifier of inequality at the bottom of the cycle, although the gap was narrow at end-2025: in Q4 2025, the Banque de France survey on firms’ access to credit showed 91% of very small firms requesting an investment loan obtaining it in full or above 75%, against 96% of SMEs and 97% of mid-sized firms (Banque de France).
When the banking channel weakens, monetary policy loses effectiveness and becomes uneven across sectors and economic agents. Understanding this financial filter is essential to explain why a single rate decision can produce uneven macroeconomic outcomes.
The banking channel shapes monetary transmission through balance sheets, prudential constraints, and credit supply.
Monetary transmission depends heavily on banks’ capacity to extend credit. Central bank decisions affect financial conditions, but their real impact operates through balance sheets constrained by regulation and risk considerations. When credit supply contracts or becomes segmented, transmission becomes partial. A related read: The Eco3min study of how policy reaches the real economy.
This dependence on the banking system is often underestimated in monetary analysis. Examining this channel helps explain why monetary policy does not operate uniformly or with the same intensity across sectors and phases of the cycle.
Balance sheets under regulatory constraints
The prudential framework stemming from Basel III imposes capital, leverage, and liquidity ratios that limit banks’ ability to expand credit independently of policy rates. Even when central banks cut rates, a bank whose CET1 ratio approaches regulatory thresholds cannot increase its exposures.
According to ECB supervisory banking statistics, the average CET1 ratio of significant euro area banks stood at 16.1% in Q2 2025 (16.0% in Q2 2026), a seemingly comfortable level. However, this average masks significant disparities. Several institutions in Southern Europe were operating with limited buffers once Pillar 2 requirements were taken into account. The effective level of liquidity in the financial system is not sufficient to ensure smooth transmission if balance sheet constraints restrict lending.
Credit supply does not mechanically follow rates
The distinction between the cost of credit and the availability of credit is central. A rate cut reduces banks’ funding costs but does not guarantee an easing of lending standards. Perceived default risk, expected unemployment, and the quality of collateral weigh as heavily as the price of liquidity.
The ECB Bank Lending Survey showed a net 7% of surveyed banks still tightening credit standards for firms in Q4 2025, after a slight net easing in Q2 (−1%), even though the deposit rate had fallen 100 basis points in a year, from 3.00% at end-2024 to 2.00% in June 2025. The real availability of credit as a determinant of monetary impact helps explain this apparent paradox: rates decline, but lending does not expand at the same pace.
This mechanism primarily affects non-listed companies dependent on bank financing. Large corporations have alternatives (bond markets, private placements) which reduce their reliance on the banking channel. SMEs and mid-sized firms, which account for more than 60% of private employment in the euro area according to Eurostat, bear the full impact of increased lending selectivity.
Assuming that lower policy rates automatically translate into easier credit conditions. Banks adjust lending standards based on their own constraints: capital levels, sector exposure, and risk provisioning. Falling rates combined with high risk aversion can keep credit conditions tight, as 2024–2025 showed: the deposit rate fell 200 basis points between June 2024 and June 2025, while standards for loans to firms still tightened on a net basis in four of the five quarters from Q4 2024 to Q4 2025.
A channel that amplifies transmission inequalities
The banking channel does not only filter the quantity of credit: it reshapes its distribution. Differences in credit access across economic agents generate asymmetric effects that aggregate analysis fails to capture. The same rate move can simultaneously ease refinancing for a large corporation while forcing an SME to delay investment.
Available data qualify the size of this gap in 2025: in Q4 2025, the Banque de France survey on firms’ access to credit showed 91% of very small firms requesting an investment loan obtaining it in full or above 75%, against 96% of SMEs and 97% of mid-sized firms. For cash loans, the obtention rate of very small firms swung between 69% and 89% from one quarter to the next since mid-2025, on a narrow sample. This structural segmentation turns the banking channel into an amplifier of inequality, rather than a simple transmission mechanism. This is set in context in the Eco3min framework on the recession mechanism.
The time sequence through which monetary decisions reach the real economy cannot be understood without incorporating this banking filter. Scenarios that expected a rapid credit rebound following the rate cuts of 2024–2025 likely underestimated the persistence of prudent behavior in the banking sector; the ECB has since raised its deposit rate, to 2.25% in June and 2.50% in September 2026. The instruments used by central banks are precisely designed to bypass these constraints, but their effectiveness remains conditional on the responsiveness of the banking system. The structural view is set out in our read of the earnings channel of monetary policy.
Last updated — 8 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Monetary Policy Transmission: Channels, Time Lags and Real-Economy Impact
Monetary policy does not strike the economy: it soaks through it. Transmission operates by accumulation across credit, balance…
The Yield Curve: What the Level Says That the Slope Doesn’t
A flat curve can sit at 1.5% or at 4.2%: the slope is the same, but the cost…
OAT-Bund Spread: A Quiet Gauge of French Sovereign Risk
OAT-Bund spread: how this yield gap has become a key signal on French sovereign risk, fiscal policy and…