
Why Strategic Consistency Matters More Than Performance
Why an investment strategy's consistency reveals more than isolated performance points, and how to separate internal inconsistency from a broader regime change.

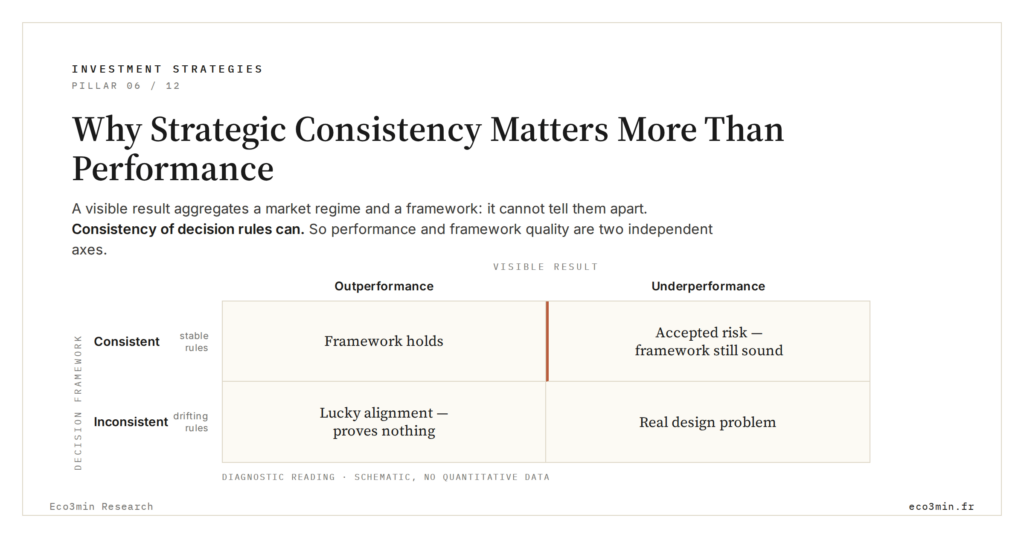
Why an investment strategy’s consistency reveals more than isolated performance points taken on their own.
TL;DR
Consistency is the constancy of a strategy's decision rules across varied contexts, a cumulative property visible only over time and invisible in isolated performance points. Related research: cycle-aware portfolio positioning.
- Consistency is asymmetric: a coherent strategy can pass through underperformance while an inconsistent one occasionally posts strong results, and that gap is what fuels diagnostic errors.
- Over short windows, performance aggregates liquidity conditions, exogenous shocks, entry and exit timing, even statistical effects, so a strong result can mark a temporary alignment rather than a coherent process.
An isolated result draws attention but does not reveal the quality of the framework that produced it. What distinguishes a robust strategy is the regularity of its decisions across varied contexts. That consistency acts as a cumulative force, visible only over time. Many still judge a strategy from a handful of visible results. That focus masks the underlying decision sequences. Examining consistency makes it possible to read the trajectory rather than just the endpoints.
When performance becomes a misleading indicator
Part of the consensus still treats recent performance as the best signal of strategic quality. Dominant projections assume that a sequence of strong results validates earlier choices ex post. This reading rests on an implicit assumption: performance would be a synthetic-enough signal to assess the relevance of a decision framework.
This interpretation is partial. Over short windows, performance aggregates heterogeneous factors: liquidity conditions, exogenous shocks, entry or exit timing, even simple statistical effects. Between 2022 and 2024, the S&P 500 fell 20.0% (FRED, series SP500, first to last trading day of 2022) then rebounded strongly in the two following years, while its realised volatility fell back sharply after 2022, from a level well above that of 2017 to 2019. In that context, a strong result can reflect a temporary alignment of factors more than a coherent strategy.
This confusion often leads to a quiet shift of the framework. What started as a stable strategy turns into successive adjustments dictated by recent results. That tactical drift blurs the reading of past decisions and weakens consistency without any explicit break being decided.
Consistency as a structural property
Consistency is not measured by a level of performance but by the constancy of the implicit rules guiding decisions. That consistency-through-constancy rather than through performance is central to our analysis of constancy versus intuition over a full cycle. It surfaces when arbitrages remain readable across changing environments: same risk criteria, same reading horizon, same accepted constraints. In other words, a consistent strategy produces comparable decisions in comparable situations, even when results differ.
This logic is asymmetric: a strategy can stay consistent while moving through a phase of underperformance, while an inconsistent strategy can occasionally post strong results. That very gap fuels diagnostic errors. The framework laid out in the analysis of strategy before performance shows that performance is a delayed consequence, not a founding criterion.
What a record of decisions shows that a return does not
Two portfolios can post identical twelve-month returns on opposite logics. One is consistent with its horizon and an accepted level of volatility; the other is the residue of successive ad hoc trades with no guiding thread. The visible result masks the fragility of the second process until a full cycle brings it to the surface. A strategy is what fixes in advance what can change, what stays stable and under which conditions an adjustment becomes legitimate.
Departing from that frame has a measurable cost. Morningstar’s Mind the Gap studies compare what fund investors actually earn with the returns of the funds they hold: the shortfall comes from mistimed purchases and sales, and it widens with turnover, narrowest on allocation funds and widest on sector equity funds. The gap tracks how often investors adjust rather than what they hold. It is the trace of a misalignment between a stated long-term horizon and an actual horizon set by short-term swings. A long-term decision then ends up judged over its observation horizon, not the horizon it was designed for.
Frequent rewrites also cost legibility. Once results aggregate several successive frameworks, a weak phase can no longer be traced to context, timing or design, and that uncertainty invites further changes in a self-reinforcing loop. A volatility regime that alternates calm years and spikes feeds the loop. Every quiet year suggests the framework works, every spike invites a rewrite, and the adjustment lands just as the framework’s logic begins to express itself.
Three markers make the reading operational without going through returns. The first is the decision turnover rate: a fast increase signals adaptation to results rather than adherence to the framework. The second is the gap between stated rules and actual decisions, which widens as the strategy grows more fragile. The third is exposure to macro regimes, checked by whether decisions stay aligned as conditions change. Consistency can also erode with no design error at all, when a strategy assumes more monitoring time or more tolerance for deviation than the person applying it actually has. Decisions are then delayed or taken on incomplete signals, and the framework drifts without anyone deciding to change it.
Why the question resurfaces now
Since 2023, the persistence of elevated policy rates has reshaped the short-term return distribution. With the cost of capital remaining above the previous decade’s level, trajectories have fragmented: rapid rebound phases, equally sharp corrections, no clear trend across several segments. This instability makes isolated performance points more visible, and more misleading.
In this environment, a strategy’s consistency becomes a more robust marker than its immediate results. It helps separate a normal materialisation of risk from a structural break in the framework: a distinction that raw figures alone cannot always deliver. Decided in advance, the size of a setback that still counts as normal turns that separation into a working test, one that belongs to a risk framework centred on avoiding permanent capital loss.
An elevated level has not meant a stable one. The upper bound of the federal funds target peaked at 5.50% in July 2023, eased to 3.75% by December 2025, then was raised again on 17 September 2026. It stood at 4.00% on 22 September 2026, against a 0.73% average over 2010–2019. The ECB raised rates on 17 June and 16 September 2026, taking back ground given up from June 2025; its deposit rate stood at 2.50% on 22 September 2026, against −0.10% on average over 2010–2019. The US 10-year real yield (FRED, series DFII10) averaged 1.91% in January 2026 and reached 2.68% on 18 September 2026, against 0.31% on average over 2012–2019. On such a path, the implicit assumption that a sound framework outperforms in every environment becomes hard to defend.
What many are really trying to understand
The real question is not so much whether a strategy « works » at a given point in time, but whether the decisions taken remain compatible with one another. Behind the focus on results often sits a simpler worry: not knowing whether weak performance reflects an expected risk event or a deeper inconsistency.
When that distinction is unclear, the temptation grows to revise the framework based on intermediate signals. Yet that implicit horizon shortening mechanically increases adjustment frequency and blurs the reading of future results.
Alternative reading and limits
This approach does not deny that some performances do signal real design problems. A lasting macroeconomic regime change, a new regulatory constraint or a technological break can render a framework obsolete. In those cases, internal consistency is no longer enough: what matters is fit with the new environment.
The challenge is therefore to distinguish internal inconsistency from external mismatch. A regime reading, such as the one offered by the macro cycle diagnostic, helps identify whether observed deviations stem from a broader transition or from a fragility specific to the strategy.
Observable economic implications
For markets, the confusion between performance and consistency fuels excessive rotation when volatility rises. For companies, it translates into strategic revisions triggered by quarterly results without any re-examination of initial assumptions. For households, it complicates the reading of past decisions and reinforces the sense of inconsistency when trajectories fluctuate.
Within the architecture of investment strategies, consistency is not a secondary criterion: it conditions a framework’s ability to remain readable and interpretable over time.
What strategic consistency truly reveals
- Consistency is judged by the constancy of decision rules, not by the magnitude of isolated results.
- Temporary underperformance can be consistent with a robust framework, while an isolated strong result validates nothing on its own.
- Separating internal inconsistency from regime change is essential to read observed trajectories correctly.
Last updated — 20 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Investment Discipline and Long-Term Portfolio Performance
Long-term portfolio performance is not driven by stock selection or market timing. It is driven by decision discipline:…
What Guaranteed Savings Products Have Paid: Fixed Annuity and Stable Value Yields Through the Rate Cycle
US guaranteed savings products credit a rate that trails the bond market rather than tracking it. Through the…
Beneficiary Designations, the Step-Up in Basis, and the 10-Year Rule: How US Accounts Transfer at Death
At death, most US financial accounts pass outside the will, straight to a named beneficiary, under tax rules…