
Time: The Most Underestimated Variable in Finance
In finance, dominant reasoning still privileges levels of rates and returns. Yet duration often weighs more than intensity: in many dynamics, it is the time of action — not the magnitude of a factor — that structures the final outcome.

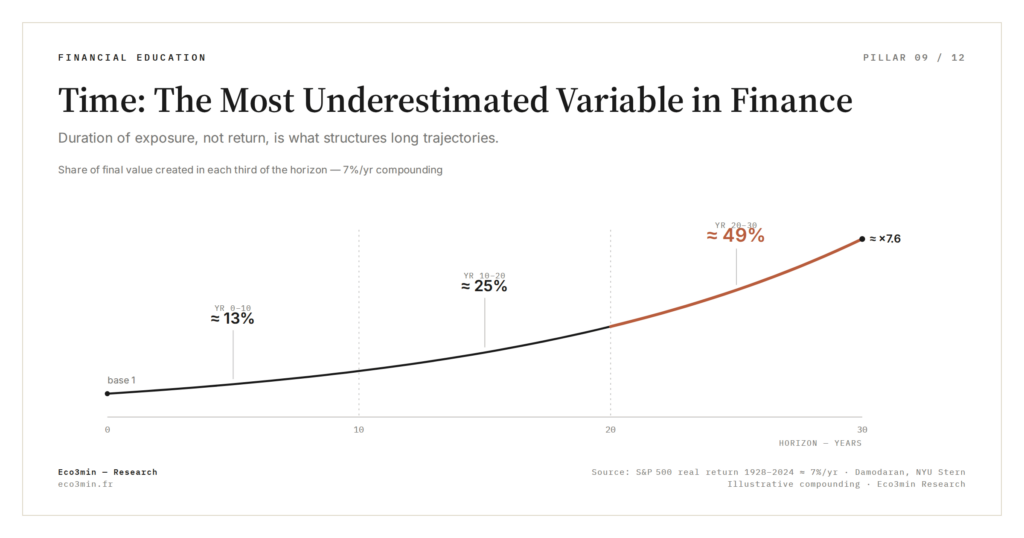
Why duration often weighs more than returns in long-term financial dynamics, and how this reshapes the reading of performance.
TL;DR
In long-horizon dynamics, duration often structures the outcome more than the level of returns, because most of the cumulative value forms late, once the base becomes dominant. In the same vein: our analysis of Eco3min’s financial tools and simulators.
- A readable benchmark is the share of gains (final value minus initial capital) generated in the last third of the horizon: 57% at 7% a year over 30 years; once it passes half, time becomes the dominant variable.
- The asymmetry is not specific to compound interest; it recurs across balance sheets, debt cycles and productive-capital dynamics, where early periods prepare and later ones concentrate the effect.
In finance, dominant reasoning still privileges levels: rate levels, yield levels, valuation levels. Time is often relegated to a mere background parameter, presumed neutral. Yet this hierarchy is misleading. In many financial dynamics, it is not the intensity of a factor that structures the final outcome, but its duration of action. In compounding the hierarchy is literal (duration occupies the exponent, intensity remains a factor), which is what makes the respective weight of rate and horizon in the formula a first-order question.
This asymmetry explains why apparently modest gaps eventually produce major divergences, without the mechanism being immediately perceived. Time does not only amplify effects: it transforms them.
Time versus rates: a poorly framed opposition
Part of the consensus still holds that returns constitute the decisive variable in financial accumulation. In this reading, time would merely execute a given rate mechanically. This assumption implicitly supposes that effects are proportional and reversible.
Experience shows the opposite: at constant returns, extending the horizon modifies the very structure of outcomes. At 7% a year over 30 years, close to the long-run real return of the S&P 500 over 1928-2024 (Damodaran, NYU Stern), capital is multiplied by about 7.6, and about 49% of the final value forms between years 20 and 30, against 13% in the first decade: a disproportionate share of the final value forms late, when the cumulative base becomes dominant. This temporal shift explains why trajectories long judged unimpressive can suddenly become decisive.
The discreet mechanism: temporal asymmetry of accumulation
The core of the phenomenon lies in a rarely articulated asymmetry: early periods play a preparatory role, while later ones concentrate most of the effect. This logic is not specific to compound interest; it appears in balance sheets, debt cycles and productive capital dynamics.
In a strictly illustrative framework, a compound interest calculator helps visualize this asymmetry: as long as the horizon remains short, the gaps appear limited; as time lengthens, the trajectory changes nature. The tool does not create the effect: it makes its temporality readable.
Why this reading remains marginal
The underestimation of time stems from a broader interpretive bias. Financial comparisons favor snapshots: annual performance, average returns, price levels. These indicators encourage a linear reading, even though the underlying mechanisms are cumulative.
This bias is reinforced by financial communication, which highlights marginal variations rather than trajectories. Within this frame, time is perceived as stable scenery rather than as an active variable.
A context that makes the error more visible
Since 2024, long-term rates have stayed high even as policy rates were cut: the 10-year U.S. Treasury yield moved between 3.63% and 4.79% over 2024-2025, before the ECB and the Fed raised rates again in 2026. That persistence has shifted attention toward the duration of financial conditions. The debate no longer concerns only the level of rates, but their persistence. This shift makes temporal effects more visible, including in mechanisms reputed to be simple.
What the reader is really asking behind this question
The implicit question is not which parameter “yields” the most, but why mathematically coherent projections produce such contrasting readings depending on the horizon. The concern relates to interpretive reliability: understanding whether a weak short-term result genuinely invalidates a longer trajectory. Settling that question starts with naming what the capital is doing, since the distinction between saving, investing and placing already fixes the horizon and the risk.
What the consensus underweights
Dominant projections often assume that adjustments in rates or returns suffice to explain future divergences. This reading neglects the cumulative role of time, which acts as a silent multiplier. The divergence is not about the figures, but about which variable is judged structural.
Counter-arguments and limits
This analysis rests on the assumption of relatively continuous trajectories. Disruptions in flows, macroeconomic shocks or regulatory changes can interrupt or distort the effect of time. Likewise, persistently unstable inflation blurs the reading by setting nominal growth against real dynamics.
Conflating high returns with favorable dynamics, without integrating the duration of exposure. This reading is misleading because it ignores that most of the cumulative effect manifests late.
A relevant reading indicator
A simple benchmark is to observe the share of gains (final value minus initial capital) generated in the last third of the horizon. At 7% a year over 30 years it reaches 57%; once it exceeds half, time becomes the dominant variable. To place this reading in a broader frame, the Financial Education pillar page synthesizes these recurrent biases tied to delays, accumulation and temporal asymmetries.
Last updated — 6 October 2026
Disclaimer – Financial and Legal Information: The analyses, commentary, and content published on eco3min.fr are provided for informational and educational purposes only. They do not constitute investment advice or a solicitation to buy or sell financial instruments. Past performance is not indicative of future results. All investment decisions involve risk and are the sole responsibility of the reader. Data, charts and calculated series are provided as is and may contain errors or lag behind their source: check any figure against the primary source cited before relying on it. Content describing laws, regulations or contracts reflects the law as of its publication date and does not constitute legal or tax advice; applying it to a specific situation requires a qualified legal or tax professional.
Read next
Full pillar →Saving vs Investing vs Placing: Understanding Risk, Time, and Liquidity
The security-liquidity-return trilemma: each function sits on a trade-off; the centre stays empty. Saving, placing, and investing refer…
How Much Cash American Households Hold: Deposits, Money Funds, and the Savings Mix
The Federal Reserve’s accounts show American households holding nearly 14.9 trillion dollars in deposits and currency and 5.3…
A high-yield savings account and a money market fund cannot be compared on their headline yield alone. The…